|
시장보고서
상품코드
2125728
유럽의 컨설팅 서비스 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Consulting Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
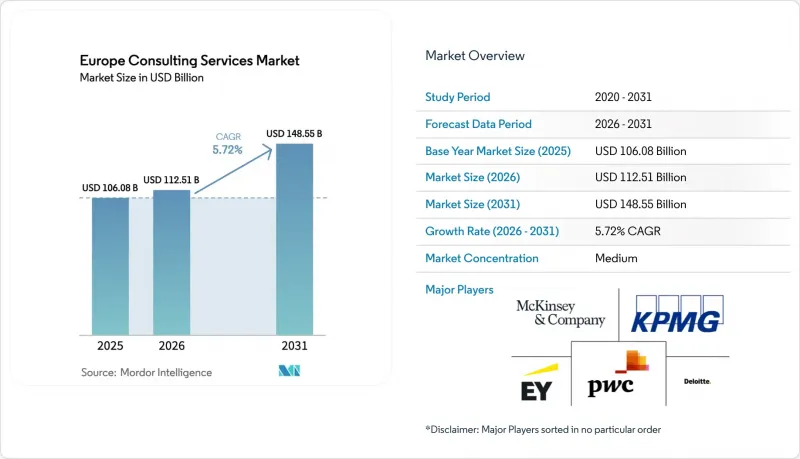
에 의하면, 유럽 컨설팅 서비스 시장 규모는 2025년에 1,060억 8,000만 달러, 2026년에 1,125억 1,000만 달러가 되어, 2031년까지 1,485억 5,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년까지 CAGR 5.71%로 성장할 전망입니다.
본 보고서는 서비스 유형(운영, 전략, 재무 자문, 기술 자문, 인사·변혁 관리, 지속가능성 및 ESG, 디지털 전환), 고객 산업(은행, 금융서비스 및 보험(BFSI), 제조, 헬스케어, 에너지 등), 기업 규모(대기업, 중소기업),제공 모델(온사이트, 원격, 하이브리드), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
유럽 컨설팅 서비스 시장 동향 및 인사이트
EU 그린딜 및 CSRD 규정 준수 압력
약 5만 개의 유럽 기업이 2025 회계연도 보고서부터 감사된 지속가능성 공시 정보를 공개해야 하며, 이는 기존 제도에 비해 10배 증가한 수치입니다. 자문 수요는 ESG 데이터 플랫폼, 스코프 3 모델링 및 보증 준비에 집중되어 있으며, 한 대기업은 2025년 CSRD 관련 업무가 전년 대비 43% 증가했다고 밝혔습니다. 법적 책임이 최고재무책임자(CFO)에게도 확대됨에 따라, ESG는 단순한 평판 제고를 위한 노력이 아니라 이사회 차원의 규정 준수 우선 과제가 되었습니다. 이 지침의 ‘이중 중요성 원칙’에 따라 기업은 기후 관련 재무 위험과 환경 발자국을 모두 정량화해야 하지만, 사내에 그러한 역량을 갖춘 기업은 드뭅니다. 독일과 프랑스는 국내에서 엄격한 시행을 통해 가장 신속하게 대응을 추진한 반면, 남유럽 및 동유럽 회원국들은 최종 지침이 나올 때까지 다소 완만한 속도로 대응을 진행하고 있습니다.
AI를 활용한 생산성 컨설팅에 대한 고객 수요 가속화
유럽 기업들의 생성형 AI 도입률은 2024년 초 12%에서 2025년 12월까지 38%로 상승했습니다. 컨설팅 업무는 현재 모델 선정, 프롬프트 엔지니어링, EU AI법 준수 대응에 이르기까지 확대되고 있습니다. 각 기업은 이용 사례 로드맵 수립, 파일럿 실시, 직원 재교육을 수년에 걸친 프로그램으로 통합하고 있으며, 성과 연계형 가격 책정에 대한 의존도가 높아지고 있습니다. 한 통합업체의 2025년 유럽 AI 프로젝트 중 62%가 성과 기반 요금제를 채택했습니다. 영국과 독일은 풍부한 인재 풀과 성숙한 클라우드 인프라를 바탕으로 지출을 주도하고 있지만, 하이퍼스케일 기업들이 거주 규정을 충족하기 위해 데이터센터를 현지화함에 따라 남유럽 시장도 가속화되고 있습니다.
고급 분석 분야의 만성적인 인력 부족
독일에서는 2025년 12월 기준, IT 및 데이터 분석 분야의 미충원 채용 공고가 12만 4,000건에 달하고, 전년 대비 17% 증가했습니다. 인력 부족은 급여를 상승시키고 프로젝트 이익률을 압박하며, 기업들이 부티크 기업을 인수하거나 니어쇼어 거점을 개설하도록 강요하고 있습니다. 영국의 이민 수용 상한선으로 인해 EU 역외에서 데이터 사이언스자의 유입이 더욱 제한되고 있어, 런던의 기업들은 업무를 더블린이나 바르샤바로 이전하고 있습니다. 북유럽 국가들의 대학에서는 현지 수요에 부응할 만큼의 컴퓨터 과학 졸업생을 배출하지 못하고 있어, 비자 규제가 완화되었음에도 불구하고 인력 부족은 심화되고 있습니다. 규제 대상인 고객사는 온쇼어 팀을 강력히 요구하는 경우가 많아, 리스크 완화 수단으로서의 오프쇼어링이 제한되고 있습니다.
부문 분석
2025년, 유럽 컨설팅 서비스 시장 매출에서 전략 컨설팅이 24.11%라는 가장 큰 점유율을 차지했습니다. 그러나 CSRD(기업 지속가능성 보고 지침)의 기한 및 이사회 차원의 기후 리스크 모니터링을 배경으로, 지속가능성 및 ESG 프로젝트는 6.81%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 디지털 전환(DX) 프로젝트는 고객이 ESG 지표를 ERP 및 고객용 대시보드에 통합함에 따라 관련 수요를 흡수하고 있습니다. 운영 컨설팅은 비용 절감 및 공급망 변동으로 인해 견조한 모습을 유지하고 있습니다. 금융 자문 부문은 재생 에너지 및 헬스케어 분야의 활발한 거래 흐름으로부터 혜택을 받고 있는 반면, 기술 및 사이버 보안 자문 부문은 더욱 엄격해진 NIS2 규제에 따라 융합이 진행되고 있습니다.
지속가능성의 기세는 고객의 지출 배분을 변화시키고 있습니다. 검증된 CSRD 조사 기법과 스코프 3 산정 효율화 도구를 보유한 기업들이 수년에 걸친 지속 계약을 확보하고 있습니다. ESG 보증과 관련된 유럽 컨설팅 서비스 시장 규모는 2031년까지 다른 어떤 하위 분야보다 빠른 속도로 성장할 것으로 예측됩니다. 한편, 성과 연동형 가격 책정은 운영 및 디지털 전환 분야에서 탄력을 받고 있지만, 전략 및 재무 자문 업무는 무형의 가치 창출이 주를 이루기 때문에 여전히 시간 및 재료비 기반의 요금 체계가 주류를 이루고 있습니다. 인사 및 변화 관리 업무는 AI를 활용한 인재 계획으로 중심을 옮기고 있으며, 2025년 프로젝트의 절반 이상에서 생성형 AI 교육이 포함될 전망입니다.
BFSI(은행 및 금융 및 보험) 부문은 바젤 IV 및 디지털 운영 회복탄력성법(DORA)의 컴플라이언스 프로그램을 주축으로, 2025년 총 보수의 19.87%를 차지했습니다. 에너지·유틸리티 분야의 프로젝트는 REPowerEU에 따른 송전망 현대화 의무화를 반영하여 6.58%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다. 제조업 고객은 인더스트리 4.0 및 순환 경제로의 전환을 위해 견조한 지출을 유지하는 한편, 의료 컨설팅은 2025년 의약품 승인 건수가 사상 최고치를 기록함에 따라 확대되고 있습니다.
유틸리티 분야 프로젝트에서는 전략 수립, 기술 로드맵 수립, 예측 유지보수 분석이 통합된 프로젝트가 증가하고 있으며, 이는 해당 부문과 관련된 유럽 컨설팅 서비스 시장 규모를 끌어올리고 있습니다. 소비재 및 소매 분야 수요는 옴니채널 통합 및 지속가능성 표시를 중심으로 회복되고 있습니다. 공공 부문 프로젝트는 정부가 디지털 서비스를 위해 RRF 자금을 투입함에 따라 확대되고 있으며, 운송 분야의 고객사는 ‘Fit for 55’의 CO2 기준에 부합하는 탈탄소화 로드맵 수립을 위해 파트너사와 협력하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the Europe consulting services market size is projected to be USD 106.08 billion in 2025, USD 112.51 billion in 2026, and reach USD 148.55 billion by 2031, growing at a CAGR of 5.71% from 2026 to 2031.
This report is Segmented by Service Type (Operations, Strategy, Financial Advisory, Technology Advisory, HR and Change Management, Sustainability and ESG, and Digital Transformation), Client Industry (BFSI, Manufacturing, Healthcare, Energy, and More), Enterprise Size (Large, and SMEs), Delivery Model (On-Site, Remote, and Hybrid), and Geography. Market Forecasts are Provided in Value (USD).
Europe Consulting Services Market Trends and Insights
EU Green Deal and CSRD Compliance Pressures
Roughly 50,000 European companies must publish audited sustainability disclosures beginning with fiscal-year 2025 reports, a tenfold increase versus prior regimes. Advisory demand centers on ESG data platforms, Scope 3 modelling, and assurance readiness, with one large firm citing a 43% year-on-year rise in CSRD-linked work in 2025. Legal liability now extends to chief financial officers, making ESG a board-level compliance priority rather than a reputational initiative. The directive's double-materiality principle requires companies to quantify both climate-related financial risk and their environmental footprint, capabilities rarely found in-house. Germany and France moved fastest due to stringent national enforcement, while Southern and Eastern members are scaling more gradually pending final guidance.
Accelerated Client Demand for AI-Enabled Productivity Consulting
Generative-AI adoption in European enterprises climbed from 12% in early 2024 to 38% by December 2025. Consulting engagements now span model selection, prompt engineering, and EU AI Act compliance. Firms bundle use-case road-mapping, pilot execution, and workforce reskilling into multi-year programs that increasingly rely on outcome-based pricing; 62% of one integrator's European AI projects in 2025 carried success-linked fees. The UK and Germany dominate spend thanks to large talent pools and mature cloud infrastructure, while Southern markets accelerate as hyperscale's localize data centers to satisfy residency rules.
Persistent Talent Deficit in Advanced Analytics
Germany reported 124,000 unfilled IT and data-analytics roles in December 2025, 17% higher than the prior year. Scarcity inflates salaries, squeezes project margins, and drives firms to acquire boutiques or open near-shore hubs. UK immigration caps further restrict non-EU data-scientist inflow, prompting London practices to shift delivery to Dublin and Warsaw. Nordic universities produce fewer computer-science graduates than local demand, exacerbating the deficit despite liberal visa rules. Regulated clients often insist on onshore teams, limiting off shoring as a mitigation lever.
Other drivers and restraints analyzed in the detailed report include:
- SME Digital-Maturity Funding via EU RRF Grants
- Regulatory Convergence for Cross-Border Services
- Fee-Compression from Procurement-Led Negotiations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Strategy consulting generated the largest 24.11% share of Europe consulting services market revenue in 2025. Sustainability and ESG projects, however, are forecast to post the highest 6.81% CAGR, propelled by CSRD deadlines and board-level climate-risk oversight. Digital transformation engagements capture adjacent demand as clients embed ESG metrics into ERP and customer dashboards. Operations consulting remains resilient due to cost-containment and supply-chain volatility. Financial advisory benefits from brisk renewable-energy and healthcare deal flow, while technology and cybersecurity advisory converge under the stricter NIS2 regime.
Sustainability's momentum is shifting wallet share. Firms with verified CSRD methodologies and Scope 3 accounting accelerators are winning multi-year retainers. The Europe consulting services market size linked to ESG assurance is projected to grow faster than any other sub-line through 2031. Meanwhile, outcome-based pricing gains traction in operations and digital transformation, though strategy and financial advisory engagements largely remain time and materials due to intangible value creation. HR and change-management practices pivot toward AI-enabled workforce planning, integrating generative-AI training in more than half of 2025 engagements.
BFSI contributed 19.87% of 2025 fees, anchored by Basel IV and Digital Operational Resilience Act compliance programs. Energy and utilities engagements are expected to log the fastest 6.58% CAGR, reflecting grid-modernization mandates under REPowerEU. Manufacturing clients sustain robust spend on Industry 4.0 and circular-economy transitions, while healthcare consulting expands alongside record drug approvals in 2025.
Utilities projects increasingly bundle strategy, technology road-mapping, and predictive-maintenance analytics, lifting the Europe consulting services market size attached to the sector. Consumer and retail demand rebounds, centering on omnichannel integration and sustainability labelling. Public-sector engagements grow as governments deploy RRF funds for digital services, and transportation client's partner on decarbonization roadmaps aligned with Fit for 55 CO2 standards.
Complete Report Scope:
- By Service Type
- Operations Consulting
- Strategy Consulting
- Financial Advisory
- Technology Advisory
- HR and Change Management
- Sustainability and ESG Consulting
- Digital Transformation Consulting
- By Client Industry
- BFSI
- Manufacturing and Industrials
- Healthcare and Life Sciences
- Energy and Utilities
- ICT and Media
- Consumer and Retail
- Rest of Client Industries
- By Enterprise Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Delivery Model
- On-site Engagement
- Remote/Virtual
- Hybrid Model
- By Country
- United Kingdom
- Germany
- France
- Benelux
- Italy
- Nordics
- Spain
- Central and Eastern Europe (incl. Poland)
- Rest of Europe
List of Companies Covered in this Report:
- Deloitte Touche Tohmatsu Limited
- PricewaterhouseCoopers LLP
- Accenture PLC
- Ernst and Young Global Limited
- KPMG International
- McKinsey and Company
- Boston Consulting Group
- Bain and Company
- Kearney
- Roland Berger
- Capgemini Invent
- BearingPoint
- Oliver Wyman
- L.E.K. Consulting
- Alvarez and Marsal
- Grant Thornton International
- BDO Advisory
- PA Consulting Group
- IBM Consulting
- Infosys Consulting
- Atos Consulting
- Wipro Consulting Services
- NTT DATA Business Solutions
- CGI Inc.
- Tata Consultancy Services (TCS) Consulting
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Regulatory convergence for cross-border services
- 4.2.2 Accelerated client demand for AI-enabled productivity consulting
- 4.2.3 EU Green Deal and CSRD compliance pressures
- 4.2.4 SME digital-maturity funding via EU RRF grants
- 4.2.5 Shift to outcome-based pricing models
- 4.2.6 Near-shoring driven by geopolitical risk in supply chains
- 4.3 Market Restraints
- 4.3.1 Persistent talent deficit in advanced analytics
- 4.3.2 Fee-compression from procurement-led negotiations
- 4.3.3 Generative-AI DIY toolkits reducing entry-level work
- 4.3.4 Regulatory scrutiny on large integrator-consultant MandA
- 4.4 Industry Value and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products and Services
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Service Type
- 5.1.1 Operations Consulting
- 5.1.2 Strategy Consulting
- 5.1.3 Financial Advisory
- 5.1.4 Technology Advisory
- 5.1.5 HR and Change Management
- 5.1.6 Sustainability and ESG Consulting
- 5.1.7 Digital Transformation Consulting
- 5.2 By Client Industry
- 5.2.1 BFSI
- 5.2.2 Manufacturing and Industrials
- 5.2.3 Healthcare and Life Sciences
- 5.2.4 Energy and Utilities
- 5.2.5 ICT and Media
- 5.2.6 Consumer and Retail
- 5.2.7 Rest of Client Industries
- 5.3 By Enterprise Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises (SMEs)
- 5.4 By Delivery Model
- 5.4.1 On-site Engagement
- 5.4.2 Remote/Virtual
- 5.4.3 Hybrid Model
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Benelux
- 5.5.5 Italy
- 5.5.6 Nordics
- 5.5.7 Spain
- 5.5.8 Central and Eastern Europe (incl. Poland)
- 5.5.9 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Deloitte Touche Tohmatsu Limited
- 6.4.2 PricewaterhouseCoopers LLP
- 6.4.3 Accenture PLC
- 6.4.4 Ernst and Young Global Limited
- 6.4.5 KPMG International
- 6.4.6 McKinsey and Company
- 6.4.7 Boston Consulting Group
- 6.4.8 Bain and Company
- 6.4.9 Kearney
- 6.4.10 Roland Berger
- 6.4.11 Capgemini Invent
- 6.4.12 BearingPoint
- 6.4.13 Oliver Wyman
- 6.4.14 L.E.K. Consulting
- 6.4.15 Alvarez and Marsal
- 6.4.16 Grant Thornton International
- 6.4.17 BDO Advisory
- 6.4.18 PA Consulting Group
- 6.4.19 IBM Consulting
- 6.4.20 Infosys Consulting
- 6.4.21 Atos Consulting
- 6.4.22 Wipro Consulting Services
- 6.4.23 NTT DATA Business Solutions
- 6.4.24 CGI Inc.
- 6.4.25 Tata Consultancy Services (TCS) Consulting
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment