

|
시장보고서
상품코드
2125518
유럽의 군용기 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Military Aircraft - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
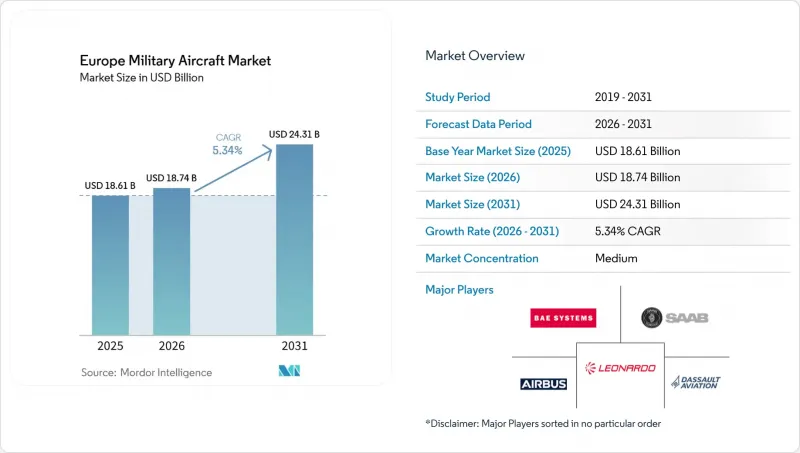
에 의하면, 유럽의 군용기 시장 규모는 2025년 186억 1,000만 달러로 평가되었고, 2026년에는 187억 4,000만 달러로 추정되고, 2026-2031년 CAGR 5.34%로 성장을 지속할 전망이며, 2031년까지 243억 1,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 항공기 유형별(고정익기·회전익기), 최종 사용자 서비스별(공군, 육군용 항공대, 해군/해병대 항공대, 통합·특수작전부대 등), 추진 방식별(터보팬, 터보제트, 터보프로프, 터보샤프트, 완전 전기/하이브리드 전기), 지역별(영국, 프랑스, 독일 등)로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
유럽의 군용기 시장 동향 및 인사이트
우크라이나 사태 이후 NATO 조달 체계의 재구축
우크라이나 분쟁으로 인해 유럽의 국방 예산은 지난 수십 년간 유례없는 속도로 재편되었으며, 유럽 군용기 시장은 그 혜택을 가장 뚜렷하게 누리고 있는 분야 중 하나가 되었습니다. 2025년, 유럽의 군사 지출은 14% 증가하여 8,640억 달러에 달하며, 해당 지역에서 사상 최고 수준을 기록했습니다. 또한, 각국 정부가 단순히 국방 예산의 기준선을 상향 조정하는 데 그치지 않고 공군력 및 장비 조달에 더 많은 자금을 배정함에 따라 지출 구성도 변화했습니다. 2026년 7월 NATO 정상회의에서 회원국들은 최대 10대의 사브(Saab)사 제작 ‘세계 아이(Global Eye)’ 구매를 결정하며, 공동 프로그램에서 유럽산 플랫폼을 명확히 우선시하는 자세를 보였습니다. 예산 증가와 공동 조달이 결합되면서 단기적인 수주 전망은 견조한 추세를 보이고 있으며, 이는 현재 예측 기간을 넘어 유럽 군용기 시장을 뒷받침하고 있습니다.
기체의 노후화와 개조·현대화를 중심으로 한 수요
기체의 노후화는 여전히 유럽 군용기 시장 전체에 걸쳐 교체 및 업그레이드 결정을 촉구하고 있습니다. 유로파이터 파트너국들은 타이푼의 생산량을 연간 14대에서 36개월 이내에 20대로, 나아가 30대로 증산할 계획인 한편, 해당 플랫폼을 2060년대까지 현역으로 유지하기 위해 중기 업그레이드도 추진하고 있습니다. 또한 독일은 새로운 유로파이터 ‘트랜치 5’의 수주와 SEAD(적 방공 제압) 업그레이드 패키지를 승인했으며, 이에 따라 신규 제조 수요와 병행하여 개조 수요도 지속되고 있습니다. 게다가 독일은 2026년에 ‘토네이도’ 전투기의 대체 기종으로 F-35A를 인도받을 예정이므로, 2세대에 걸친 전투기 조달이 동시에 진행되고 있습니다. 이러한 세대 중첩으로 인해 전투기, 항공전자 장비 관련 업무, 훈련용 자산, 지원 활동이 별도의 주기가 아닌 하나의 통합된 체계로 뒷받침되고 있습니다.
조달 비용의 인플레이션과 수명 주기 부담
조달 비용은 급격히 상승하고 있으며, 이는 유럽 군용기 시장의 발주 규모 축소로 이어지고 있습니다. GCAP의 설계 계약만 해도 18개월 단계에서 총액 46억 파운드(61억 달러)에 달하며, 6세대 기체 개발이 얼마나 고비용인지 여실히 보여주고 있습니다. 또한 유로파이터 기체군에는 아비오닉스와 소프트웨어 베이스라인이 서로 다른 트랜치 1, 2, 3 기체가 여전히 포함되어 있어 유지 비용도 상승하고 있습니다. 이로 인해 유지 관리의 복잡성이 가중되어, 예산이 제한된 소규모 NATO 회원국들에게는 수명 주기 계획 수립이 더욱 어려워지고 있습니다. 그 결과, 일부 정부는 능력 향상을 위한 자금을 확보할 수는 있더라도 희망하는 수량을 구매하는 데 여전히 어려움을 겪고 있습니다.
부문 분석
2025년 유럽 군용기 시장에서 고정익기는 62.48%를 차지했으며, 이 부문은 회전익기를 크게 앞지르고 있습니다. 고정익 항공기 중 전투기는 여전히 수요의 주요 원동력이며, 독일에 대한 F-35A 납품, 라팔의 지속적인 생산, 유로파이터의 생산 확대에 힘입어 수주 잔고 전망이 더욱 밝아지고 있습니다. 또한, 새로운 전투기 부대는 전선 배치 전에 전용 도입 훈련 능력이 필요하기 때문에 훈련기의 중요성도 높아지고 있습니다. 2025년 12월 레오나르도사가 오스트리아로부터 M-346 F Block 20 기종 12대를 수주한 것은 첨단 훈련기에 대한 수요가 전투기 부대 갱신 ‘이후’가 아니라 ‘동시에’ 발생하고 있음을 보여줍니다. 수송기 분야에서도 공동 조달로의 전환이 진행되고 있으며, 2026년 7월에는 NATO 회원국 7개국이 A400M의 공동 운용을 시작할 예정이어서, 이로 인해 소규모 국가들이 미래의 공수 수요에 대비해 예산을 편성하는 방식이 바뀔 가능성이 있습니다.
회전익기는 2031년까지 연평균 성장률(CAGR) 6.79%로 확대될 것으로 예측되며, 유럽 군용기 시장에서 가장 빠르게 성장하는 기체 유형이 될 전망입니다. 2025년 12월, 스페인이 에어버스사 헬리콥터 100대를 45억 유로(53억 달러)에 발주한 계약에는 H145M, NH90, H135, H175M 등 각 기종이 포함되어 있어, 이 부문에 다년간에 걸친 대규모 생산 기반을 마련해 주었습니다. 또한, 이 수주는 단일 조달 계획 내에서 훈련, 해상 임무, 특수 작전, 경공격의 요구를 충족시킬 수 있는 대수는 적지만 유연성이 높은 군용 헬리콥터로의 명확한 전환을 보여줍니다. NAHEMA가 2026년 4월에 발표한 NH90 블록 2에 관한 조사는 15개 운용국을 대상으로 신규 제조와 개조 두 가지 경로를 모두 아우름으로써 수요를 더욱 확대되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 주요 업계 동향
제5장 시장 구도
제6장 시장 규모 및 성장 예측
제7장 경쟁 구도
제8장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Europe military aircraft market size is expected to grow from USD 18.61 billion in 2025 to USD 18.74 billion in 2026, and is forecast to reach USD 24.31 billion by 2031, at a 5.34% CAGR over 2026-2031.
This report is Segmented by Aircraft Type (Fixed-Wing Aircraft and Rotorcraft), End-User Service (Air Force, Army Aviation, Naval/Marine Corps Aviation, Joint/Special Operations, and More), Propulsion Type (Turbofan, Turbojet, Turboprop, Turboshaft, and Fully Electric/Hybrid-Electric), and Geography (United Kingdom, France, Germany, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Military Aircraft Market Trends and Insights
NATO Procurement Rebuild After Ukraine
The Ukraine conflict reset European defense budgeting at a speed not seen in decades, and the Europe military aircraft market is one of the clearest beneficiaries. The European military expenditure rose by 14% to USD 864 billion in 2025, the highest level recorded for the region. The spending mix also changed as governments shifted more money toward airpower and equipment procurement rather than simply raising baseline defense budgets. At the July 2026 NATO summit, allies moved to purchase up to 10 Saab GlobalEye aircraft, indicating a clear preference for a European platform in a collective program. That combination of higher budgets and shared procurement keeps near-term order visibility strong and supports the Europe military aircraft market beyond the current forecast window.
Fleet Ageing and Upgrade-Centric Demand
Fleet age is still forcing replacement and upgrade decisions across the Europe military aircraft market. Eurofighter partners plan to raise Typhoon production from 14 aircraft a year to 20 within 36 months, then to 30, while also pushing a mid-life upgrade to keep the platform relevant into the 2060s. Germany also approved a new Eurofighter Tranche 5 order and an SEAD upgrade package, which keeps retrofit demand moving alongside new-build demand. Germany is also taking delivery of F-35A aircraft in 2026 to replace Tornado jets, so procurement is occurring across two generations of combat aircraft simultaneously. That overlap supports fighter jets, avionics work, training assets, and support activities together rather than in separate cycles.
Acquisition Cost Inflation and Life-Cycle Burden
Acquisition costs are rising fast enough to slow order sizes in the Europe military aircraft market. The GCAP design contract alone totals GBP 4.60 billion (USD 6.10 billion) for an 18-month phase, underscoring how expensive sixth-generation work has become. Support costs also rise because Eurofighter fleets still include Tranche 1, 2, and 3 aircraft with different avionics and software baselines. That pushes sustainment complexity higher and makes life-cycle planning harder for smaller NATO members with tighter budgets. The result is that some governments can fund capability upgrades but still struggle to buy the volumes they would prefer.
Other drivers and restraints analyzed in the detailed report include:
- FCAS and GCAP Industrial Spillover
- Indigenous Content Rules Favor European Suppliers
- Engine-Core and Avionics Supply Bottlenecks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fixed-wing aircraft accounted for 62.48% of the Europe military aircraft market in 2025, keeping this category well ahead of rotorcraft. Fighter jets remain the core demand driver inside fixed-wing, with Germany's F-35A deliveries, continuing Rafale output, and the Eurofighter production ramp all extending backlog visibility. Training aircraft are also gaining weight because new combat fleets need dedicated lead-in training capacity before frontline induction. Leonardo's December 2025 order for 12 M-346 F Block 20 aircraft from Austria showed that demand for advanced trainers is moving with combat fleet renewal rather than after it. Transport aircraft are also shifting toward pooled procurement, with 7 NATO allies launching a shared A400M fleet in July 2026, which could change how smaller states budget future airlift needs.
Rotorcraft is projected to expand at 6.79% CAGR through 2031, making it the fastest-growing aircraft type in the Europe military aircraft market. Spain's EUR 4.50 billion (USD 5.30 billion) order for 100 Airbus helicopters in December 2025 covered the H145M, NH90, H135, and H175M platforms, giving the segment a large multiyear production base. That order also shows a clear move toward fewer, more flexible military helicopters that can cover training, maritime, special operations, and light-attack needs within a single procurement plan. NAHEMA's April 2026 NH90 Block 2 study adds another layer of demand by covering both new-build and retrofit pathways across a 15-nation operator base.
Complete Report Scope:
- By Aircraft Type
- Fixed-Wing Aircraft
- Multi-Role Aircraft
- Training Aircraft
- Transport Aircraft
- Others
- Rotorcraft
- Multi-Mission Helicopters
- Transport Helicopters
- Others
- Fixed-Wing Aircraft
- By End-User Service
- Air Force
- Army Aviation
- Naval/Marine Corps Aviation
- Joint/Special Operations
- Paramilitary and Coast Guard
- By Propulsion Type
- Turbofan
- Turbojet
- Turboprop
- Turboshaft
- Fully Electric and Hybrid-Electric
- By Geography
- United Kingdom
- France
- Germany
- Italy
- Netherlands
- Russia
- Spain
- Turkey
- Rest of Europe
List of Companies Covered in this Report:
- Airbus SE
- BAE Systems plc
- Dassault Aviation SA
- Embraer S.A.
- Elbit Systems Ltd.
- Hindustan Aeronautics Limited
- Israel Aerospace Industries Ltd.
- Korea Aerospace Industries, Ltd.
- Leonardo S.p.A.
- Lockheed Martin Corporation
- Northrop Grumman Corporation
- Saab AB
- The Boeing Company
- Turkish Aerospace Industries, Inc.
- United Aircraft Corporation
- Denel SOC Ltd.
- Pilatus Aircraft Ltd.
- Thales Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 KEY INDUSTRY TRENDS
- 4.1 Gross Domestic Product
- 4.2 Active Fleet Data
- 4.3 Defense Spending
5 MARKET LANDSCAPE
- 5.1 Market Overview
- 5.2 Market Drivers
- 5.2.1 NATO procurement rebuild after Ukraine
- 5.2.2 Fleet ageing and upgrade-centric demand
- 5.2.3 FCAS and GCAP industrial spillover
- 5.2.4 Indigenous content rules favor European suppliers
- 5.2.5 Software-defined mission systems raise retrofit scope
- 5.2.6 Carbon-constrained defense procurement nudges hybrid-electric development
- 5.3 Market Restraints
- 5.3.1 Acquisition cost inflation and life-cycle burden
- 5.3.2 Engine-core and avionics supply bottlenecks
- 5.3.3 Certification delays for next-gen and retrofit platforms
- 5.3.4 Skilled labor shortages in aerospace integration
- 5.4 Value Chain Analysis
- 5.5 Regulatory Landscape
- 5.6 Technological Outlook
- 5.7 Porter's Five Forces Analysis
- 5.7.1 Threat of New Entrants
- 5.7.2 Bargaining Power of Suppliers
- 5.7.3 Bargaining Power of Buyers
- 5.7.4 Threat of Substitutes
- 5.7.5 Intensity of Competitive Rivalry
6 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 6.1 By Aircraft Type
- 6.1.1 Fixed-Wing Aircraft
- 6.1.1.1 Multi-Role Aircraft
- 6.1.1.2 Training Aircraft
- 6.1.1.3 Transport Aircraft
- 6.1.1.4 Others
- 6.1.2 Rotorcraft
- 6.1.2.1 Multi-Mission Helicopters
- 6.1.2.2 Transport Helicopters
- 6.1.2.3 Others
- 6.1.1 Fixed-Wing Aircraft
- 6.2 By End-User Service
- 6.2.1 Air Force
- 6.2.2 Army Aviation
- 6.2.3 Naval/Marine Corps Aviation
- 6.2.4 Joint/Special Operations
- 6.2.5 Paramilitary and Coast Guard
- 6.3 By Propulsion Type
- 6.3.1 Turbofan
- 6.3.2 Turbojet
- 6.3.3 Turboprop
- 6.3.4 Turboshaft
- 6.3.5 Fully Electric and Hybrid-Electric
- 6.4 By Geography
- 6.4.1 United Kingdom
- 6.4.2 France
- 6.4.3 Germany
- 6.4.4 Italy
- 6.4.5 Netherlands
- 6.4.6 Russia
- 6.4.7 Spain
- 6.4.8 Turkey
- 6.4.9 Rest of Europe
7 COMPETITIVE LANDSCAPE
- 7.1 Market Concentration
- 7.2 Strategic Moves
- 7.3 Market Share Analysis
- 7.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 7.4.1 Airbus SE
- 7.4.2 BAE Systems plc
- 7.4.3 Dassault Aviation SA
- 7.4.4 Embraer S.A.
- 7.4.5 Elbit Systems Ltd.
- 7.4.6 Hindustan Aeronautics Limited
- 7.4.7 Israel Aerospace Industries Ltd.
- 7.4.8 Korea Aerospace Industries, Ltd.
- 7.4.9 Leonardo S.p.A.
- 7.4.10 Lockheed Martin Corporation
- 7.4.11 Northrop Grumman Corporation
- 7.4.12 Saab AB
- 7.4.13 The Boeing Company
- 7.4.14 Turkish Aerospace Industries, Inc.
- 7.4.15 United Aircraft Corporation
- 7.4.16 Denel SOC Ltd.
- 7.4.17 Pilatus Aircraft Ltd.
- 7.4.18 Thales Group
8 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 8.1 White-space and Unmet-Need Assessment


