

|
시장보고서
상품코드
2125636
중동의 범죄 및 전투 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Middle East Crime And Combat - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
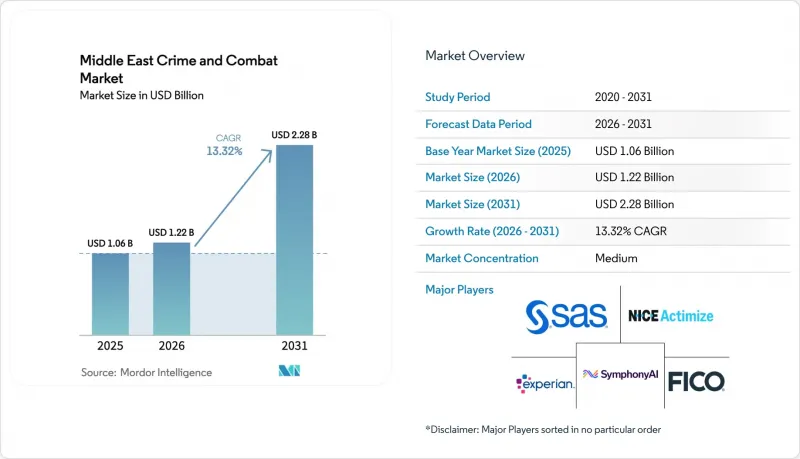
중동의 범죄 및 전투 시장 규모는 2025년 10억 6,000만 달러로 평가되었고, 2026년 12억 2,000만 달러에서 2031년까지 22억 8,000만 달러로 확대될 것으로 예측되며, 2026-2031년 연평균 복합 성장률(CAGR)은 13.3%를 나타낼 전망입니다.
본 보고서는 솔루션별(고객 확인(KYC) 시스템, 거래 모니터링, 규정 준수 보고 제품군, 감사 및 분석 등), 도입 형태별(클라우드 및 온프레미스), 최종 사용자 산업별(은행, 금융서비스 및 보험(BFSI), 정부 및 법 집행 기관 등), 용도별(AML, CTF 등), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시됩니다.
중동의 범죄 및 전투 시장 동향 및 인사이트
디지털 결제의 급속한 확산
걸프협력회의(GCC) 국가들의 디지털 결제 처리액은 2025년에 2,270억 달러에 달했고, 2030년까지 3,600억 달러를 넘어설 것으로 예측됩니다. UAE 및 사우디아라비아(KSA)의 즉시 결제 네트워크에서는 개인 간 송금이 몇 초 만에 처리되므로 심사 기간이 단축되고, 은행은 위험을 즉시 평가하는 머신러닝 엔진을 도입할 수밖에 없게 되었습니다. GCC에서 남아시아로 송금하는 이주 노동자의 송금액은 2025년에 500억 달러를 넘어섰으며, 비공식 송금 경로도 규제 대상이 되었습니다. 이러한 경로를 통해 서비스를 제공하는 핀테크 기업에는 현재 e-KYC(전자 신원 확인) 의무가 부과되고 있으며, 예측 불가능한 트래픽 급증에 대응할 수 있는 클라우드 기반 사례 관리 제품군 도입 경쟁이 치열해지고 있습니다. 이처럼 디지털 결제의 방대한 규모와 즉각성은 중동 범죄 및 전투 및 치안 유지 시장 전체의 지속적인 성장을 견인하고 있습니다.
GCC의 국경 간 무역 감시 강화
2025년, GCC와 아시아, 아프리카, 유럽 간의 상품 무역 총액은 1조 2,000억 달러에 달한 것으로 평가되었으며, 세관 당국은 청구서 사기 및 제재 회피를 적발하기 위해 무역 금융 데이터를 금융 정보 기관에 제공하기 시작했습니다. UAE의 블록체인 실증 실험에서는 선하증권을 실질 소유자 등록부와 연동하여 유령 회사를 거의 실시간으로 식별하고 있습니다. 사우디아라비아(KSA)의 2025년 시행 예정인 ‘도착 전 신고’ 규정에 따라 구조화된 컨테이너 데이터가 생성되며, 컴플라이언스 엔진이 이를 분석하여 고가의 전자 기기가 저위험 관할 구역으로 연속적으로 출하되는 등의 이상 징후를 감지합니다. 이러한 혁신을 위해서는 대행 은행의 메시지와 화물 이동 현황을 대조하는 분석 제품군이 필요하지만, 기존의 AML 도구에는 이 기능이 포함되어 있지 않아, 바로 이러한 요건이 중동 범죄 및 전투 시장의 주요 성장 동력이 되고 있습니다.
아랍어를 구사하는 컴플라이언스 분석가 부족
2025년에는 이중 언어를 구사하는 컴플라이언스 분석가의 공석률이 35%에 달하여 은행들은 외국인 직원에게 의존할 수밖에 없게 되었지만, 이들은 거래 배경에 있는 지역 고유의 뉘앙스를 간과하기 쉽습니다. 2025년 UAE와 사우디아라비아의 대학에서 금융 범죄와 아랍어 두 분야를 전공한 학위 취득자는 800명 미만이었던 반면, 시장 수요는 2,500개 이상의 직위에 달했습니다. 이집트와 쿠웨이트에서는 규제 당국에 48시간 이내에 아랍어로 작성된 보고서를 제출하도록 요구하고 있어, 인력이 제한된 팀에 과도한 부담이 가해지고 있습니다. 각 벤더사는 아랍어 자연어 처리 모델을 통합하고 있지만, 이집트와 걸프 국가들의 방언에 대한 정확도는 여전히 80% 미만에 그치고 있어, 수작업으로 인한 병목 현상이 재발하고 있으며, 이는 중동 범죄 및 전투 시장의 달성 가능한 성장률을 저해하고 있습니다.
부문 분석
2025년, 거래 감시 시스템은 중동 범죄 및 전투 시장의 38.19%를 차지했으며, 이는 모든 즉시 결제 및 무역 금융 지시에 대해 규제 당국이 제재, 자금 세탁, 테러 자금 조달의 관점에서 심사를 실시할 것을 강력히 요구하고 있음을 반영합니다. 중동의 범죄 및 전투 시장에서 합성 신원 조직이 디지털 지갑을 악용함에 따라 부정 감지 및 사례 관리 도구에 할당되는 시장 규모는 2031년까지 연평균 성장률(CAGR) 13.98%로 급증할 것으로 예측됩니다. 분석가가 AML(자금 세탁 방지)과 부정 유형을 자유롭게 전환할 수 있는 통합 대시보드는 경보 누적을 억제하고 데이터 중복을 제거할 수 있어 지지를 얻고 있습니다.
Oracle Financial Services Software와 Fiserv는 GCC(걸프협력회의) 회원국 은행들과의 오랜 계약을 활용하여, 핵심 고객 기록을 재사용하는 부정 감지 모듈의 업셀링을 추진하고 있습니다. 한편, Feedzai나 Comply Advantage와 같은 AI 네이티브 신생 기업들은 사전 학습된 모델을 제공함으로써 시스템 가동까지 걸리는 기간을 12개월에서 6개월로 단축하고 있습니다. 카타르 중앙은행이 2026년 1월부터 XML 형식의 의심 거래 보고를 의무화함에 따라, 규정 준수 보고 제품군에 대한 수요가 급속히 확대되고 있습니다. 모델의 편향성과 거버넌스를 추적하는 감사 및 분석 플랫폼은 이사회 차원의 필수 요건이 되어, 확대되는 중동 범죄 및 전투 시장에서 입지를 공고히 하고 있습니다.
UAE 및 사우디아라비아(KSA)의 데이터 상주 규정과 레거시 하드웨어에 대한 매몰 비용으로 인해, 2025년 시점에서도 온프레미스 환경은 중동 범죄 및 전투 및 대응 시장 규모의 56.71%를 차지했습니다. 그러나 리야드, 제다, 아부다비, 두바이의 하이퍼스케일 데이터센터가 주권 요건을 충족하고 모델 훈련을 위한 탄력적인 컴퓨팅을 제공함에 따라, 클라우드 구독은 2026-2031년 연평균 성장률(CAGR) 14.04%를 기록할 전망입니다.
UAE 중앙은행이 2025년 4월에 발표한 지침에 따르면, 암호화, 접근 제어 및 정보 유출 통지가 국가전자보안국(NESA)의 프레임워크를 준수하는 경우, 퍼블릭 클라우드에서의 규정 준수 워크로드가 승인되었습니다. 주요 금융 기관들은 개인 식별 가능 데이터를 온프레미스에 보관하면서 부하가 높은 분석 작업을 클라우드로 오프로드하는 하이브리드 모델을 시범적으로 도입하고 있는 반면, 핀테크 기업들은 자본 지출을 피하기 위해 클라우드 네이티브 스택으로 직접 전환하고 있습니다. 각 벤더는 멀티 클라우드 오케스트레이션, 실시간 데이터 마스킹, 저지연 리저널 존 등의 측면에서 차별화를 꾀하고 있으며, 이에 따라 중동의 향후 부정 방지 및 범죄 및 전투 시장 점유율은 구독 모델에 유리하게 기울 것으로 전망됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Middle East crime and combat market size is projected to expand from USD 1.06 billion in 2025 and USD 1.22 billion in 2026 to USD 2.28 billion by 2031, registering a CAGR of 13.3% between 2026 and 2031.
This report is Segmented by Solution (Know-Your-Customer Systems, Transaction Monitoring, Compliance Reporting Suites, Auditing and Analytics, and More), Deployment Mode (Cloud, and On-Premises), End-User Vertical (BFSI, Government and Law-Enforcement Agencies, and More), Application (AML, CTF, and More), and Geography. Market Forecasts are Provided in Terms of Value (USD).
Middle East Crime And Combat Market Trends and Insights
Rapid Digital Payments Penetration
Digital payment volumes across Gulf Cooperation Council (GCC) economies reached USD 227 billion in 2025 and are expected to exceed USD 360 billion by 2030. Instant-payment rails in the UAE and KSA settle peer-to-peer transfers in seconds, compressing review windows and compelling banks to embed machine-learning engines that score risk on the fly. Migrant-worker remittances from the GCC to South Asia surpassed USD 50 billion in 2025, bringing informal channels under regulatory purview. Fintechs serving these corridors now carry mandatory e-KYC obligations, driving a scramble for cloud-based case-management suites able to absorb unpredictable traffic spikes. The sheer scale and immediacy of digital payments, therefore, power sustained growth across the Middle East crime and combat market.
Intensifying GCC Cross Border Trade Surveillance
GCC merchandise trade with Asia, Africa and Europe totalled USD 1.2 trillion in 2025, and customs agencies have begun piping trade-finance data into financial-intelligence units to catch invoice fraud and sanctions evasion. The UAE's blockchain pilot links bills of lading to beneficial-ownership registries, exposing shell companies in near real time. KSA's 2025 pre-arrival declaration rule creates structured container data that compliance engines parse for anomalies such as serial shipments of high-value electronics to low-risk jurisdictions. These innovations demand analytics suites that reconcile correspondent-banking messages with cargo movements, a capability absent in legacy AML tools, and this requirement is a key accelerant for the Middle East crime and combat market.
Shortage of Arabic-Speaking Compliance Analysts
Vacancy rates for bilingual compliance analysts hit 35% in 2025, forcing banks to lean on expatriates who often miss regional nuances within transaction narratives. Universities in the UAE and KSA conferred fewer than 800 dual financial-crime and Arabic-linguistics qualifications in 2025 against market demand for more than 2,500 roles. Regulatory filing deadlines in Egypt and Kuwait require Arabic reports within 48 hours, stretching thinly staffed teams. Vendors are embedding Arabic natural-language models, but precision on Egyptian and Gulf dialects remains below 80%, reinscribing manual bottlenecks and tempering the Middle East crime and combat market's attainable growth rate.
Other drivers and restraints analyzed in the detailed report include:
- Mandatory e-KYC Frameworks in UAE and KSA
- AI-Driven Anomaly Detection in Tier-1 Banks
- Fragmented Legacy Core-Banking Stacks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Transaction monitoring systems held 38.19% of the Middle East crime and combat market share in 2025, reflecting regulatory insistence that every instant-payment and trade-finance instruction be screened for sanctions, structuring, and terrorist financing. The Middle East crime and combat market size allocated to fraud detection and case-management tools is forecast to jump ata 13.98% CAGR through 2031 as synthetic-identity rings exploit digital wallets. Integrated dashboards that let analysts switch between AML and fraud typologies are in favour because they suppress alert backlogs and eliminate data duplication.
Oracle Financial Services Software and Fiserv leveraged long-standing GCC bank contracts to upsell fraud modules that reuse core customer records, whereas AI-native challengers such as Feedzai and Comply Advantage compress go-lives from 12 to 6 months by shipping pre-trained models. Compliance-reporting suites are growing briskly after the Qatar Central Bank mandated XML suspicious-transaction filings in January 2026. Auditing and analytics platforms that track model bias and governance have become board-level imperatives, cementing their foothold in the expanding Middle East crime and combat market.
On-premises estates retained 56.71% of the Middle East crime and combat market size in 2025 owing to data-residency rules in the UAE and KSA and the sunk cost of legacy hardware. Cloud subscriptions, however, are on course to log a 14.04% CAGR between 2026 and 2031 as hyperscale data centers in Riyadh, Jeddah, Abu Dhabi and Dubai satisfy sovereignty mandates and provide elastic compute for model training.
The Central Bank of the UAE's April 2025 guidance approved public-cloud compliance workloads if encryption, access controls and breach notifications match the National Electronic Security Authority framework. Large lenders are testing hybrid blueprints that keep personally identifiable data on-premises while off-loading heavy analytics tasks to the cloud, whereas fintech leap directly to cloud-native stacks to avoid capital expenditure. Vendors differentiate on multi-cloud orchestration, real-time data masking and low-latency regional zones, tilting future Middle East crime and combat market share in favour of subscription models.
Complete Report Scope:
- By Solution
- Know-Your-Customer (KYC) Systems
- Transaction Monitoring
- Compliance Reporting Suites
- Auditing and Analytics
- Fraud Detection / Case Management
- By Deployment Mode
- Cloud
- On-premises
- By End-user Vertical
- Banking, Financial Services and Insurance (BFSI)
- Government and Law-Enforcement Agencies
- FinTechs and Payment Service Providers
- Designated Non-Financial Businesses and Professions
- By Application
- Anti-Money Laundering (AML)
- Counter-Terrorist Financing (CTF)
- Fraud and Cyber-Crime Detection
- Regulatory and Tax Compliance (FATCA, CRS)
- By Geography
- United Arab Emirates
- Kingdom of Saudi Arabia
- Qatar
- Egypt
- Kuwait
- Bahrain and Oman
- Rest of Middle East
List of Companies Covered in this Report:
- SAS Institute Inc.
- NICE Ltd (Actimize Solutions)
- Fair Isaac Corporation (FICO)
- ACI Worldwide Inc.
- Oracle Financial Services Software Ltd.
- Fiserv Inc.
- Experian plc
- Refinitiv Ltd (London Stock Exchange Group)
- EastNets FZ-LLC
- Tata Consultancy Services Ltd.
- Temenos AG
- Wolters Kluwer NV
- Fidelity National Information Services Inc. (FIS)
- SymphonyAI Financial Crime
- iSPIRAL IT Solutions Ltd.
- Napier AI Ltd.
- Feedzai SA
- ComplyAdvantage Ltd.
- ThetaRay Ltd.
- BAE Systems Digital Intelligence
- LexisNexis Risk Solutions Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Digital-Payments Penetration
- 4.2.2 Intensifying GCC Cross-Border Trade Surveillance
- 4.2.3 Mandatory e-KYC Frameworks (UAE, KSA)
- 4.2.4 AI-Driven Anomaly Detection Adoption in Tier-1 Banks
- 4.2.5 FATF Mutual-Evaluation Pressures Prompting Compliance Pre-Investment
- 4.2.6 Generative-AI Explainability Toolkits Slashing False Positives
- 4.3 Market Restraints
- 4.3.1 Shortage of Arabic-Speaking Compliance Analysts
- 4.3.2 Fragmented Legacy Core-Banking Stacks
- 4.3.3 High On-Premise System Switching Costs
- 4.3.4 Carbon-Border Adjustment Mechanisms Extending AML Scope to ESG Data
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE & GROWTH FORECASTS (VALUE)
- 5.1 By Solution
- 5.1.1 Know-Your-Customer (KYC) Systems
- 5.1.2 Transaction Monitoring
- 5.1.3 Compliance Reporting Suites
- 5.1.4 Auditing and Analytics
- 5.1.5 Fraud Detection / Case Management
- 5.2 By Deployment Mode
- 5.2.1 Cloud
- 5.2.2 On-premises
- 5.3 By End-user Vertical
- 5.3.1 Banking, Financial Services and Insurance (BFSI)
- 5.3.2 Government and Law-Enforcement Agencies
- 5.3.3 FinTechs and Payment Service Providers
- 5.3.4 Designated Non-Financial Businesses and Professions
- 5.4 By Application
- 5.4.1 Anti-Money Laundering (AML)
- 5.4.2 Counter-Terrorist Financing (CTF)
- 5.4.3 Fraud and Cyber-Crime Detection
- 5.4.4 Regulatory and Tax Compliance (FATCA, CRS)
- 5.5 By Geography
- 5.5.1 United Arab Emirates
- 5.5.2 Kingdom of Saudi Arabia
- 5.5.3 Qatar
- 5.5.4 Egypt
- 5.5.5 Kuwait
- 5.5.6 Bahrain and Oman
- 5.5.7 Rest of Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 SAS Institute Inc.
- 6.4.2 NICE Ltd (Actimize Solutions)
- 6.4.3 Fair Isaac Corporation (FICO)
- 6.4.4 ACI Worldwide Inc.
- 6.4.5 Oracle Financial Services Software Ltd.
- 6.4.6 Fiserv Inc.
- 6.4.7 Experian plc
- 6.4.8 Refinitiv Ltd (London Stock Exchange Group)
- 6.4.9 EastNets FZ-LLC
- 6.4.10 Tata Consultancy Services Ltd.
- 6.4.11 Temenos AG
- 6.4.12 Wolters Kluwer NV
- 6.4.13 Fidelity National Information Services Inc. (FIS)
- 6.4.14 SymphonyAI Financial Crime
- 6.4.15 iSPIRAL IT Solutions Ltd.
- 6.4.16 Napier AI Ltd.
- 6.4.17 Feedzai SA
- 6.4.18 ComplyAdvantage Ltd.
- 6.4.19 ThetaRay Ltd.
- 6.4.20 BAE Systems Digital Intelligence
- 6.4.21 LexisNexis Risk Solutions Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


