|
시장보고서
상품코드
2125650
중국의 센서 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)China Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
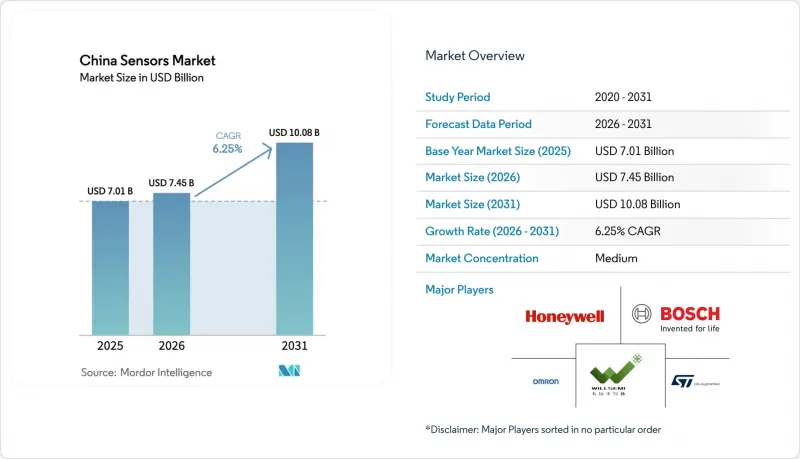
중국의 센서 시장 규모는 2026년에 74억 5,000만 달러로 추정되고, 2025년 70억 1,000만 달러에서 확대해, 2031년에는 100억 8,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 6.25%가 될 것으로 전망됩니다.
본 보고서는 측정 파라미터별(온도, 압력, 레벨, 유량, 근접 등), 작동 모드별(광학식, 전기저항식, 바이오센서, 피에조저항식, 영상식, 라이더 등), 기술별(MEMS, CMOS/IC 센서, 광섬유, 양자·NV 센터, 기타) 및 최종 사용자 산업별(자동차, 소비자 가전, 에너지, 산업 및 제조, 의료·웰니스 등)로 분류되어 있습니다.
중국의 센서 시장 동향 및 인사이트
정부 주도의 ‘중국 제조 2025’에 따른 현지화 추진
대규모 재정적 우대 조치와 조달 우선 조치에 따라 주요 센서 부품의 국내 조달률은 2020년 약 40%에서 2025년까지 70%로 상승했습니다. 2025년 초까지 33곳 이상의 제조 혁신 센터가 개설되어 대학과 기업 간의 공동 연구 개발 거점이 되고 있습니다. 우대 대출, 인증 절차 간소화, 지적 재산(IP) 지원 등을 통해 현지 기업의 진입 장벽이 더욱 낮아졌으며, 압력, 환경, 관성 센서 각 분야에서 현재 해외 공급업체에 필적하는 수직 통합형 밸류체인이 구축되었습니다.
전기차(EV) 생산의 급증으로 고온·압력·전류 센서 수요가 증가했으며
2024년 전기차 판매 대수는 350만 대를 넘어 2023년 이전 수준 대비 3자리 수의 성장세를 유지했으며, 차량 1대당 센서 탑재 수는 연평균 8-10%의 속도로 증가했습니다. BYD는 추가 비용 없이 전 차종에 ‘God’s Eye’ 스마트 드라이빙 플랫폼을 기본 사양으로 탑재했으며, 대중차에서도 첨단 열 관리, 배터리 압력, 전류 측정 어레이를 표준화했습니다. 이러한 추세에 따라 주요 조립 거점과 가장 가까운 위치에 있는 국내 MEMS 및 션트식 전류 센서 제조업체의 수주 잔고가 확대되었습니다.
수입된 특수 웨이퍼에 대한 의존도가 공급망 리스크를 야기하고 있습니다.
국내 팹이 성숙 노드의 생산 능력을 확충했음에도 불구하고, 중국은 여전히 고온·포토닉 센서에 사용되는 SOI, SiC, GaN 웨이퍼에 대해 해외 공급업체에 의존하고 있었습니다. 2024년에 시행된 첨단 기판에 대한 새로운 수출 규제 조치로 인해 조달 측면의 불확실성이 높아지고, 버퍼 재고를 확보할 수밖에 없게 된 결과, 운전 자금 수요가 증가했습니다. 그 결과 발생한 리드타임 변동으로 인해 최첨단 자동차 및 의료기기 생산에 제약이 발생했습니다.
부문별 분석
2025년, 압력 센서는 중국 센서 시장 점유율의 18.45%를 차지했으며, 자동차, 산업, 휴대전화 분야에서 확고한 임베디드 실적을 반영하고 있습니다. 환경 센서는 시장 규모는 작지만, 국가 대기 환경 품질 기준의 엄격화와 지자체에 의한 PM2.5 모니터링 의무화에 힘입어 16.59%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다.
1선 도시에서의 대기질 관측 거점의 급속한 확충이 미세 정밀 가스 및 입자 센서에 대한 수요를 자극하여, 예측 기간 동안 중국 환경 분야의 센서 시장 규모를 놀라운 속도로 끌어올렸습니다. 소비자용 IoT 공기청정기 및 스마트 홈 기기도 판매 대수의 추가 확대에 기여했습니다. 한편, 유량·레벨 센서는 화학 처리 및 상수도 유틸리티 프로젝트에서 착실하게 발전했으며, 진동·자기 센서는 구조물의 건전성 모니터링 및 자율 항해 이용 사례에서 보급이 확대되었습니다.
압저항형 디바이스는 성숙한 패키징 라인과 확립된 설계 IP에 힘입어 2025년에도 매출 점유율 31.75%를 유지했습니다. 반면, 중급 전기차(EV)에서 ADAS의 보급이 확대됨에 따라 LiDAR 유닛의 연평균 성장률(CAGR)은 2031년까지 21.53%를 나타낼 것으로 예측됩니다. Hesai와 RoboSense는 2024년에 자동차용 LiDAR를 합쳐 52만 대 이상 출하했으며, 이는 전 세계 출하 대수의 3분의 1에 해당합니다.
중국의 라이다 센서 시장 규모는 성능 지표를 규정한 GB/T 45500-2025 등의 국가 표준을 바탕으로 2031년까지 14억 2,000만 달러에 육박할 것으로 전망됩니다. 이를 보완하는 레이더, 정전용량식 터치 센서, 광학 이미저 등은 멀티모달 지각 어레이가 필요한 소비자용 기기 및 산업용 로봇 시장을 대상으로 두 자릿수 성장세를 유지했습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, China sensors market size in 2026 is estimated at USD 7.45 billion, growing from 2025 value of USD 7.01 billion with 2031 projections showing USD 10.08 billion, growing at 6.25% CAGR over 2026-2031.
This report is Segmented by Parameter Measured (Temperature, Pressure, Level, Flow, Proximity, and More), Mode of Operation (Optical, Electrical Resistance, Biosensors, Piezoresistive, Image, Lidar, and More), Technology (MEMS, CMOS / IC Sensors, Fiber-Optic, Quantum and NV-Centre, and Others), and by End-User Industry (Automotive, Consumer Electronics, Energy, Industrial and Manufacturing, Medical and Wellness, and More).
China Sensors Market Trends and Insights
Government-led "Made in China 2025" localization push
Large-scale fiscal incentives and mandated procurement preferences lifted domestic content in core sensor components toward 70% by 2025, compared with about 40% in 2020. More than 33 Manufacturing Innovation Centres had been launched by early 2025, anchoring joint R&D between universities and enterprises. Preferential financing, expedited certification, and IP support further reduced entry barriers for local firms, fostering a vertically integrated value chain that now rivals overseas suppliers in pressure, environmental, and inertial categories.
EV production surge boosting demand for high-temperature, pressure, and current sensors
EV sales exceeded 3.5 million units in 2024, sustaining a triple-digit expansion from pre-2023 levels and lifting per-vehicle sensor content at an 8-10% annual pace. BYD bundled its 'God's Eye' smart-driving platform across the full model line without extra cost, normalizing advanced thermal-management, battery-pressure, and current-measurement arrays even in mass-market cars. The trend strengthened order books for domestic MEMS and shunt-based current-sensor makers positioned closest to major assembly hubs.
Dependence on imported specialty wafers creates supply-chain risk
Despite domestic fabs adding mature-node capacity, China still relied on overseas suppliers for SOI, SiC, and GaN wafers used in high-temperature and photonic sensors. Renewed export-control measures on advanced substrates in 2024 heightened procurement uncertainty and forced buffer-stock policies, increasing working-capital needs. Resulting lead-time volatility constrained the production of cutting-edge automotive and medical devices.
Other drivers and restraints analyzed in the detailed report include:
- Mass manufacturing of smartphones and IoT wearables clustering in Guangdong
- Smart-factory retrofits across the Yangtze River Delta are accelerating industrial sensor uptake
- Fragmented IP landscape triggering cross-licensing disputes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pressure sensors accounted for 18.45% of China's sensor market share in 2025, reflecting established automotive, industrial, and handset integration footprints. Environmental sensors represented a smaller base yet posted the fastest 16.59% CAGR forecast, propelled by stricter National Ambient Air Quality Standards and municipal PM2.5 monitoring mandates.
Rapid air-quality site build-outs in Tier-1 cities stimulated demand for micro-precision gas and particulate sensors, pushing the China sensors market size for environmental categories at a significant rate during the forecast period. Consumer IoT air-purifiers and smart-home devices further broadened volume. Meanwhile, flow and level sensors advanced steadily in chemical processing and water-utilities projects, while vibration and magnetic devices gained traction in structural health and autonomous navigation use cases.
Piezoresistive components retained a 31.75% revenue share in 2025, anchored by mature packaging lines and well-established design IP. LiDAR units, however, are projected for a 21.53% CAGR through 2031 as ADAS penetration in mid-range EVs climbs. Hesai and RoboSense jointly shipped more than 520,000 automotive LiDARs in 2024, equal to one-third of global deliveries.
The China sensors market size for LiDAR is expected to approach USD 1.42 billion by 2031 on the strength of national standards such as GB/T 45500-2025 that codify performance metrics. Complementary radar, capacitive-touch, and optical imagers sustained double-digit growth, serving consumer devices and industrial robots that require multi-modal perception arrays.
Complete Report Scope:
- By Parameter Measured
- Temperature
- Pressure
- Level
- Flow
- Proximity
- Environmental (Air-quality, Gas)
- Chemical
- Inertial (Accel/Gyro)
- Magnetic
- Vibration
- Other Parameters
- By Mode of Operation
- Optical
- Electrical Resistance
- Biosensors
- Piezoresistive
- Image
- Capacitive
- Piezoelectric
- LiDAR
- Radar
- Other Modes
- By Technology
- MEMS
- CMOS / IC Sensors
- Fiber-Optic
- Quantum and NV-Centre
- Others (O-NEMS, Thin-Film)
- By End-user Industry
- Automotive
- Consumer Electronics
- Smartphones
- Tablets, Laptops and PCs
- Wearables
- Smart Home Devices
- Other Consumer Electronics
- Energy (Generation and Storage)
- Industrial and Manufacturing
- Medical and Wellness
- Construction, Agriculture and Mining
- Aerospace and Defense
List of Companies Covered in this Report:
- Bosch Sensortec GmbH
- STMicroelectronics NV
- Honeywell International Inc.
- Omron Corporation
- Infineon Technologies AG
- Texas Instruments Inc.
- Panasonic Corporation
- Sensirion AG
- Hesai Technology Co. Ltd.
- NXP Semiconductors NV
- TDK Corporation (InvenSense)
- Analog Devices Inc.
- Melexis NV
- AAC Technologies Holdings Inc.
- Will Semiconductor Co. Ltd.
- Goertek Inc.
- MEMSensing Microsystems Co. Ltd.
- Novosense Microelectronics
- Hanwei Electronics Group Corp.
- OmniVision Technologies Inc.
- Amphenol Advanced Sensors
- Shanghai Zhaohui Pressure Apparatus Co. Ltd.
- Sinochip Electronics Co. Ltd.
- Hefei 3-Nod Sensor Co. Ltd.
- Silan Microelectronics Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government-led "Made in China 2025" localisation push for sensor supply-chains
- 4.2.2 EV production surge boosting demand for high-temperature, pressure and current sensors
- 4.2.3 Mass-manufacturing of smartphones and IoT wearables clustering in Guangdong raises MEMS volumes
- 4.2.4 Smart-factory retrofits across Yangtze River Delta accelerating industrial sensor uptake
- 4.2.5 Rising adoption of remote patient-monitoring and digital health platforms driving medical sensors
- 4.2.6 Falling 8-inch MEMS wafer costs from domestic foundries widening sensor addressable markets
- 4.3 Market Restraints
- 4.3.1 Dependence on imported specialty wafers creating supply-chain risk
- 4.3.2 Fragmented IP landscape triggering cross-licensing disputes with incumbents
- 4.3.3 Price wars among local vendors eroding RandD budgets
- 4.3.4 China Cyber-security Law complicating deployment of cloud-connected industrial sensors
- 4.4 Value Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Competition
- 4.8 Investment Analysis
- 4.9 Imapct of Macroeconomic Factors on the market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Parameter Measured
- 5.1.1 Temperature
- 5.1.2 Pressure
- 5.1.3 Level
- 5.1.4 Flow
- 5.1.5 Proximity
- 5.1.6 Environmental (Air-quality, Gas)
- 5.1.7 Chemical
- 5.1.8 Inertial (Accel/Gyro)
- 5.1.9 Magnetic
- 5.1.10 Vibration
- 5.1.11 Other Parameters
- 5.2 By Mode of Operation
- 5.2.1 Optical
- 5.2.2 Electrical Resistance
- 5.2.3 Biosensors
- 5.2.4 Piezoresistive
- 5.2.5 Image
- 5.2.6 Capacitive
- 5.2.7 Piezoelectric
- 5.2.8 LiDAR
- 5.2.9 Radar
- 5.2.10 Other Modes
- 5.3 By Technology
- 5.3.1 MEMS
- 5.3.2 CMOS / IC Sensors
- 5.3.3 Fiber-Optic
- 5.3.4 Quantum and NV-Centre
- 5.3.5 Others (O-NEMS, Thin-Film)
- 5.4 By End-user Industry
- 5.4.1 Automotive
- 5.4.2 Consumer Electronics
- 5.4.2.1 Smartphones
- 5.4.2.2 Tablets, Laptops and PCs
- 5.4.2.3 Wearables
- 5.4.2.4 Smart Home Devices
- 5.4.2.5 Other Consumer Electronics
- 5.4.3 Energy (Generation and Storage)
- 5.4.4 Industrial and Manufacturing
- 5.4.5 Medical and Wellness
- 5.4.6 Construction, Agriculture and Mining
- 5.4.7 Aerospace and Defense
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Bosch Sensortec GmbH
- 6.4.2 STMicroelectronics NV
- 6.4.3 Honeywell International Inc.
- 6.4.4 Omron Corporation
- 6.4.5 Infineon Technologies AG
- 6.4.6 Texas Instruments Inc.
- 6.4.7 Panasonic Corporation
- 6.4.8 Sensirion AG
- 6.4.9 Hesai Technology Co. Ltd.
- 6.4.10 NXP Semiconductors NV
- 6.4.11 TDK Corporation (InvenSense)
- 6.4.12 Analog Devices Inc.
- 6.4.13 Melexis NV
- 6.4.14 AAC Technologies Holdings Inc.
- 6.4.15 Will Semiconductor Co. Ltd.
- 6.4.16 Goertek Inc.
- 6.4.17 MEMSensing Microsystems Co. Ltd.
- 6.4.18 Novosense Microelectronics
- 6.4.19 Hanwei Electronics Group Corp.
- 6.4.20 OmniVision Technologies Inc.
- 6.4.21 Amphenol Advanced Sensors
- 6.4.22 Shanghai Zhaohui Pressure Apparatus Co. Ltd.
- 6.4.23 Sinochip Electronics Co. Ltd.
- 6.4.24 Hefei 3-Nod Sensor Co. Ltd.
- 6.4.25 Silan Microelectronics Co. Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment