

|
시장보고서
상품코드
2154390
상업용 팬 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Commercial Fans - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
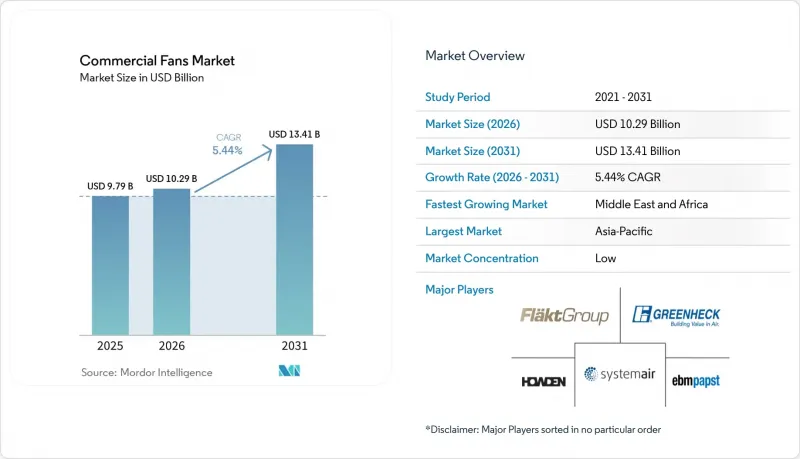
에 따르면 상업용 팬 시장 규모는 2025년 97억 9,000만 달러에서 2026년에는 102억 9,000만 달러로 확대하며, 2026-2031년에 CAGR 5.44%로 추이하며, 2031년에는 134억 1,000만 달러에 달할 것으로 예측됩니다.
전 세계 상업용 팬 시장의 동향 및 인사이트
데이터센터 및 AI 냉각 인프라
2026-2030년 사이에 전 세계에서 약 100 GW의 데이터센터 용량이 추가될 것으로 예상되며, 이에 따라 해당 부문의 연평균 성장률(CAGR)은 14%에 달할 전망입니다. 이러한 건설 계획으로 인해 컴퓨터실의 공조 장치 및 서버실 배기 시스템에 사용되는 고정밀 EC 팬에 대한 수요가 증가하고 있습니다. 특히 고밀도 컴퓨팅 장비 주변에서 신뢰할 수 있는 열 제어가 필요한 시설에서 그 수요가 두드러집니다. 랙당 30kW 미만 범위에서는 여전히 공랭식이 널리 채택되고 있습니다. 이에 따라 수랭식이 확대되는 상황에서도 팬 수요는 유지되며, 공급업체는 기존 시설과 업그레이드 중인 시설 모두에 서비스를 제공할 수 있게 됩니다. 또한 랙당 40kW 이상으로 가동되는 AI 클러스터의 경우에도 완전한 수랭식 개조가 완료될 때까지는 공랭식 보조 장치가 필요하므로 인프라 변경의 중간 단계에서 팬 시스템의 역할이 확대될 것입니다. Ziehl-Abegg사는 2026년 6월, 유럽, 미국, 아시아의 생산 능력에 대해 9,000만 유로(1억 350만 달러 상당)의 추가 투자를 발표하며, AI 데이터센터를 주요 촉진요인으로 꼽았습니다. 데이터센터 프로젝트에서 건설 역량이 부족해짐에 따라 인증된 제품, 확실한 리드타임, 그리고 다양한 냉각 구성에 적합한 장비를 제공할 수 있는 공급업체에게 유리하게 작용할 가능성이 있습니다.
상업용 건물의 환기 및 HVAC 개조 수요
상업용 팬 시장은 리모델링 수요의 혜택을 받고 있습니다. 이는 설치된 환기 설비의 교체 주기가 신축과 달리, 성능이나 규정 준수가 불충분한 경우 그 대응을 항상 미룰 수 있는 것은 아니기 때문입니다. HVAC 시스템은 상업용 건물의 에너지 소비량의 35%에서 50%를 차지하며, 병원이나 호텔의 경우 70%에 달하기도 합니다. ‘62.1-2025’ 표준에는 습도 제어, 수요 반응형 환기 및 배기 유량 요건의 업데이트가 추가되었습니다. 이러한 규정이 채택되고 지역 건축 기준이 이 규격을 참조하는 경우, 설비 업그레이드가 촉진될 가능성이 있습니다. 또한 전체 사무실 수요가 침체되어 있는 상황에서도 기존 빌딩이 임차인에게 매력적인 상태를 유지하고 현재의 운영 기대치를 충족시키기 위해서는 더 우수한 환기 시스템이 필요합니다. 고효율 팬은 소유주가 전기 요금을 직접 지불하고 전력 사용량 감축으로 인한 이점을 입증할 수 있는 경우, 운영 비용을 절감할 수 있습니다. 반면, 기존의 임대 계약에 따라 임차인이 에너지 비용을 부담하는 경우, 특히 자본 예산이 제한된 다중 임차인 건물에서는 인센티브의 불일치로 인해 개보수가 지연될 가능성이 있습니다.
첨단 고효율 팬 시스템의 높은 초기 비용
EC 모터식 팬은 구매시 유도 모터식 대체 제품보다 30%에서 60% 더 비쌀 수 있으며, 운영 비용 면에서 유리하더라도 즉각적인 장벽이 됩니다. 이러한 가격 차이로 인해 초기 예산을 중시하는 소규모 소유주나 구매자의 도입이 제한됩니다. 특히 자본 지출 승인 권한과 에너지 관리가 분리된 시장에서는 이러한 경향이 두드러집니다. 전력 회사의 리베이트를 통해 대상 개보수 비용의 20%에서 30%를 상쇄할 수 있지만, 이용 가능 여부는 지역에 따라 다르며, 전담 에너지 관리 팀을 보유하지 않은 운영자에게는 프로그램 관리가 어려울 수 있습니다. 기존의 임대차 계약 구조에서는 임차인이 전기 요금을 부담하므로 소유주의 인센티브가 약화되고, 구매자는 잠재적인 절감 효과를 직접 누릴 수 없게 됩니다. 또한 전기 요금 체계의 차이로 인해 국가나 건물 포트폴리오 전반에 걸친 공통된 조달 방안을 수립하기 어려워집니다. 구조적 여유 공간이 부족한 경우, 운영상의 경제성이 개조를 지원하고 있더라도 도심 지역의 노후 건물에서 대풍량·저속 팬으로의 개조가 더욱 제한될 가능성이 있습니다.
부문 분석
2025년, 축류 팬은 상업용 팬 시장의 42.4%를 차지했습니다. 이 팬의 비용과 성능은 HVAC 배관, 옥상 배기, 창고내 공기 순환 등 저-중정압 용도에 적합하며, 광범위한 도입으로 인해 정기적인 교체 수요가 지원되고 있습니다. 원심 팬은 더 높은 압력과 안정적인 운전 특성이 요구되는 덕트식 시스템에서 여전히 중요한 역할을 하고 있습니다. 건축 규제가 엄격해지고 운영자가 총 운영 비용을 비교 검토하게 됨에 따라 그 큰 설치 면적과 에너지 소비량에 대한 감시가 강화되고 있습니다. 배기 팬은 다른 상업용 용도가 건설 주기의 영향을 받기 쉬운 경우에도, 주방이나 병원 및 이와 유사한 환경에서는 환기 요건을 충족해야 하므로 안정적인 역할을 유지하고 있습니다.
혼합류 팬은 2031년까지 연평균 성장률(CAGR) 5.7%로 성장할 것으로 예측됩니다. 이 팬의 설계는 높은 축류 풍량과 원심 압력 능력을 겸비하여, 기존의 축류식 및 원심식 설계의 중간에 위치하는 유용한 대안을 제공합니다. 이로 인해 소형 데이터센터의 냉각 랙, 낮은 높이의 덕트 배관, 설치 공간이 제한된 옥상 시스템에 적합합니다. 그린헥(Greenheck)사는 2025년 12월, 혼합 흐름 기술을 채택한 다이렉트 드라이브 방식의 옥상 팬 ‘RSQ’를 출시했습니다. 이 제품의 성능은 최대 27,100 cfm에 달하며, FEI, 공기 성능 및 소음 성능에 관한 AMCA 인증을 획득했습니다. 클리어런스 및 유량 제어 슈라우드에 대한 추가적인 연구개발은 압력 상승 향상과 소음 저감을 위한 지속적인 노력을 보여주며, 공간 및 음향 성능이 중요한 용도에서 원심식 제품과의 격차를 좁힐 것으로 기대됩니다.
지역별 분석
2025년, 아시아태평양은 상업용 팬 시장의 42.1%를 차지했습니다. 중국에서는 제조, 창고, 상업용 부동산에 더해 하이퍼스케일 데이터센터 건설 계획이 확대되면서 주요 팬 용도인 여러 분야에서 수요가 창출되고 있습니다. 2025년, 이 지역의 데이터센터 냉각 매출의 60%를 공랭식이 차지하고 있으며, 이로 인해 컴퓨터실의 공조 설비 및 정밀 냉각 장치에 대한 수요가 지원되고 있습니다. 인도, 베트남, 인도네시아, 태국에서는 도시 개발 및 초기 단계의 데이터센터 건설을 통해 수요가 확대되고 있으며, 이에 따라 해당 지역의 상업용 환기 설비 수요도 증가하고 있습니다. 일본과 한국에서는 에너지 효율 요건에 기반한 고사양 교체 수요가 지원되고 있으며, 가변속 EC 시스템이 중요한 역할을 하고 있습니다.
북미와 유럽은 상업용 팬 시장에서 기술적 리더십의 기반을 형성하고 있습니다. 북미에서는 데이터센터 건설과 노후화된 상업용 건물의 존재가 신규 설치와 개보수 모두를 지원하고 있으며, 사양 수립에 있어서는 검증된 제품 성능이 높이 평가되고 있습니다. 유럽에서는 2026년 7월 규정 2024/1834가 시행됨에 따라 규제 준수를 주요 원인으로 하는 교체 주기에 접어들었습니다. 독일, 프랑스, 영국, 폴란드는 판매량 측면에서 중요한 유럽 시장이며, 폴란드는 데이터센터 및 물류 거점으로서도 그 중요성이 높아지고 있습니다. 브라질과 칠레에서는 대도시의 상업용 건축물 및 식품 가공을 위한 환기 수요가 성장의 원동력이 되고 있지만, 인프라 및 환율 상황에 따라 그 속도는 제한되고 있습니다.
중동 및 아프리카는 2031년까지 연평균 성장률(CAGR) 5.9%로 성장할 것으로 예측됩니다. 사우디아라비아와 아랍에미리트에서는 데이터센터, 공항 수용 능력, 호텔 및 레저 시설, 복합 용도 프로젝트가 증가하고 있으며, 이들이 대용량 환기 수요를 지원하고 있습니다. 폭염으로 인해 신뢰성 높은 연속 운전과 우수한 열 성능을 갖춘 장비에 대한 수요가 증가하고 있습니다. 남아프리카공화국과 이집트는 의료 및 소매 분야의 HVAC 투자에 있으며, 2차 수요 거점으로 부상하고 있습니다. 걸프 국가들의 사양에서는 IP 규격을 준수하는 외장, 내열 모터 권선, 내식성 코팅이 종종 요구되며, 이는 제품 단가 상승에 기여하는 동시에 해당 지역 특유의 제품 요구 사항을 두드러지게 하는 요인이 되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 공급망 분석
- Porter's Five Forces 분석
- 기술 동향
- 규제 상황
- 투자 분석
제5장 시장 규모와 성장 예측
- 팬 유형별
- 용도별
- 최종사용자별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 프랑스
- 이탈리아
- 스페인
- 영국
- 폴란드
- 러시아
- 기타 유럽 국가
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- 호주
- 인도네시아
- 베트남
- 태국
- 기타 아시아태평양 국가
- 남미
- 브라질
- 아르헨티나
- 칠레
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 아랍에미리트
- 이집트
- 남아프리카공화국
- 모로코
- 기타 중동 및 아프리카 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Air Systems Components, Inc.
- Carrier Global Corporation
- Cincinnati Fan
- Daikin Industries, Ltd.
- ebm-papst Group
- FlaktGroup Holding GmbH
- Greenheck Fan Corporation
- Howden Group Ltd
- Johnson Controls International plc
- Loren Cook Company
- Munters Group AB
- New York Blower Company
- Rosenberg Ventilatoren GmbH
- Soler & Palau Ventilation Group
- Systemair AB
- Trane Technologies plc
- Twin City Fan Companies, Ltd.
- Vent-Axia
- Zhejiang Shangfeng Industrial Group Co., Ltd.
- Zhejiang Yilida Ventilator Co., Ltd.
제7장 시장 기회와 향후 전망
KSA 26.10.23According to Mordor Intelligence, the commercial fans market size is expected to grow from USD 9.79 billion in 2025 to USD 10.29 billion in 2026 and is forecast to reach USD 13.41 billion by 2031 at 5.44% CAGR over 2026-2031.
Global Commercial Fans Market Trends and Insights
Data Center and AI Cooling Infrastructure
Nearly 100 GW of data center capacity is expected to be added globally between 2026 and 2030, which supports a 14% CAGR for the sector. This construction pipeline raises demand for precision EC fans in computer room air-handling units and server-room exhaust systems, particularly in facilities that need dependable thermal control around dense computing equipment. Air cooling remains widely used below 30 kW per rack, which keeps fan demand relevant as liquid cooling expands and allows suppliers to serve both established and upgrading facilities. AI clusters operating above 40 kW per rack also need air-assist equipment before full liquid-cooling retrofits are completed, extending the role of fan systems during an intermediate stage of infrastructure change. Ziehl-Abegg announced an additional EUR 90 million investment, equivalent to USD 103.5 million, in European, U.S., and Asian capacity in June 2026 and identified AI data centers as a key driver. Tight construction capacity in data center projects can favor suppliers that can provide certified products, dependable lead times, and equipment suited to different cooling configurations.
Commercial Building Ventilation and HVAC Retrofit Demand
The commercial fans market benefits from retrofit demand because installed ventilation equipment has a different replacement cycle from new construction and cannot always be deferred when performance or compliance falls short. HVAC systems accounted for 35% to 50% of commercial building energy use, while hospitals and hotels can reach 70%. Standard 62.1-2025 added humidity control, demand-controlled ventilation, and updated exhaust-airflow requirements, which can prompt upgrades where those provisions are adopted, and local codes refer to the standard. Existing buildings also need better ventilation to remain attractive to tenants and comply with current operating expectations, even when broader office demand is weak. Efficient fans can lower operating costs where owners directly pay electricity bills and can document the benefits of lower electricity use. Split incentives can slow upgrades where tenants pay energy costs under legacy leases, especially in multi-tenant properties with limited capital budgets.
High Upfront Cost of Advanced Energy-Efficient Fan Systems
EC-motor fans can cost 30% to 60% more than induction-motor alternatives at purchase, creating an immediate barrier even when the operating cost is favorable. This price gap limits adoption by smaller owners and buyers focused on initial budgets, particularly in markets where capital approvals are separated from energy management. Utility rebates can offset 20% to 30% of qualifying upgrade costs, but access varies by location, and program administration can be difficult for operators without dedicated energy teams. Legacy lease structures weaken the owner's incentive when tenants bear electricity costs, leaving the buyer without a direct share of the potential savings. Differences in electricity tariffs also make a common procurement case harder to prepare across countries and building portfolios. Low structural clearances can further limit high-volume, low-speed fan retrofits in older urban buildings, even where operating economics support an upgrade.
Other drivers and restraints analyzed in the detailed report include:
- Energy Efficiency and Indoor Air Quality Regulations
- Warehouses, Modular Fan Walls, and Digital Verification
- Availability of Integrated HVAC and Alternative Air-Movement Technologies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Axial fans held 42.4% of the commercial fans market in 2025. Their cost and performance suit low-to-medium static-pressure work in HVAC distribution, rooftop exhaust, and warehouse circulation, where broad deployment supports repeat replacement demand. Centrifugal fans remain important in ducted systems that need higher pressure and a stable operating profile. Their larger footprint and energy use face greater scrutiny as building rules tighten and operators compare full operating costs. Exhaust fans retain a stable role because kitchens, hospitals, and similar settings must meet ventilation requirements, even when other commercial applications are more exposed to construction cycles.
Mixed-flow fans are projected to grow at a 5.7% CAGR through 2031. Their design combines high axial airflow with centrifugal pressure capability, offering a useful option between conventional axial and centrifugal designs. This makes them suitable for compact data center cooling racks, low-height duct runs, and rooftop systems with limited installation space. Greenheck introduced its RSQ direct-drive rooftop fan with mixed-flow technology in December 2025, with performance up to 27,100 cfm and AMCA licenses for FEI, air, and sound performance. Further work on clearance-flow-control shrouds points to continued efforts to improve pressure rise and reduce sound, narrowing the gap with centrifugal products in applications where space and acoustic performance are important.
Complete Report Scope:
- By Fan Type
- Axial Fans
- Centrifugal Fans
- Mixed-Flow Fans
- Exhaust Fans
- Other Commercial Fan Types
- By Application
- General Ventilation
- HVAC and Air Conditioning
- Cooling and Air Circulation
- Exhaust and Fume Extraction
- Other Applications
- By End User
- Office Buildings
- Retail and Shopping Centers
- Hotels and Hospitality
- Restaurants and Commercial Kitchens
- Hospitals and Healthcare Facilities
- Educational Institutions
- Warehouses and Distribution Centers
- Data Centers
- Transportation Infrastructure
- Other Commercial Facilities
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- Spain
- United Kingdom
- Poland
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Vietnam
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Morocco
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 42.1% of the commercial fans market in 2025. China combines manufacturing, warehousing, commercial real estate, and a growing hyperscale data center pipeline, creating demand across several major fan applications. Air-based cooling accounted for 60% of regional data center cooling revenue in 2025, which sustains demand for computer room air-handling and precision-cooling equipment. India, Vietnam, Indonesia, and Thailand add demand through urban development and early-stage data center construction, expanding the regional need for commercial ventilation equipment. Japan and South Korea support high-specification replacement demand under energy-efficiency requirements, where variable-speed EC systems are relevant.
North America and Europe form the technology leadership base for the commercial fans market. North American data center construction and aging commercial buildings support both new installations and retrofits, while specification work places a high value on tested product performance. Europe entered a compliance-led replacement cycle when Regulation 2024/1834 became enforceable in July 2026. Germany, France, the United Kingdom, and Poland are important European markets by volume, with Poland also gaining relevance as a data center and logistics location. Brazil and Chile provide growth from commercial construction in large cities and food-processing ventilation, although infrastructure and currency conditions limit the pace.
Middle East and Africa are projected to grow at a 5.9% CAGR through 2031. Saudi Arabia and the United Arab Emirates are adding data centers, airport capacity, hospitality properties, and mixed-use projects, which support higher-capacity ventilation demand. Extreme heat creates demand for equipment with reliable continuous operation and stronger thermal performance. South Africa and Egypt are secondary demand centers for healthcare and retail HVAC investment. Gulf specifications often require IP-rated housings, high-temperature motor windings, and corrosion-resistant coatings, which can support higher unit values and distinguish regional product requirements.
- Air Systems Components, Inc.
- Carrier Global Corporation
- Cincinnati Fan
- Daikin Industries, Ltd.
- ebm-papst Group
- FlaktGroup Holding GmbH
- Greenheck Fan Corporation
- Howden Group Ltd
- Johnson Controls International plc
- Loren Cook Company
- Munters Group AB
- New York Blower Company
- Rosenberg Ventilatoren GmbH
- Soler & Palau Ventilation Group
- Systemair AB
- Trane Technologies plc
- Twin City Fan Companies, Ltd.
- Vent-Axia
- Zhejiang Shangfeng Industrial Group Co., Ltd.
- Zhejiang Yilida Ventilator Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Data Center and AI Cooling Infrastructure
- 4.2.2 Commercial Building Ventilation and HVAC Retrofit Demand
- 4.2.3 Energy-Efficiency and Indoor-Air-Quality Regulations
- 4.2.4 Industrialization and Expansion of Warehouses and Distribution Centers
- 4.2.5 Modular Fan-Wall Adoption in Brownfield Air-Handling Units
- 4.2.6 Fan-Energy-Index-Based Procurement and Digital Performance Verification
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost of Advanced Energy-Efficient Fan Systems
- 4.3.2 Availability of Integrated HVAC and Alternative Air-Movement Technologies
- 4.3.3 Structural and Clearance Constraints for High-Volume Low-Speed Fan Retrofits
- 4.3.4 Rare-Earth Magnet and Specialty-Alloy Supply Exposure
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Fan Type
- 5.1.1 Axial Fans
- 5.1.2 Centrifugal Fans
- 5.1.3 Mixed-Flow Fans
- 5.1.4 Exhaust Fans
- 5.1.5 Other Commercial Fan Types
- 5.2 By Application
- 5.2.1 General Ventilation
- 5.2.2 HVAC and Air Conditioning
- 5.2.3 Cooling and Air Circulation
- 5.2.4 Exhaust and Fume Extraction
- 5.2.5 Other Applications
- 5.3 By End User
- 5.3.1 Office Buildings
- 5.3.2 Retail and Shopping Centers
- 5.3.3 Hotels and Hospitality
- 5.3.4 Restaurants and Commercial Kitchens
- 5.3.5 Hospitals and Healthcare Facilities
- 5.3.6 Educational Institutions
- 5.3.7 Warehouses and Distribution Centers
- 5.3.8 Data Centers
- 5.3.9 Transportation Infrastructure
- 5.3.10 Other Commercial Facilities
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 France
- 5.4.2.3 Italy
- 5.4.2.4 Spain
- 5.4.2.5 United Kingdom
- 5.4.2.6 Poland
- 5.4.2.7 Russia
- 5.4.2.8 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Indonesia
- 5.4.3.7 Vietnam
- 5.4.3.8 Thailand
- 5.4.3.9 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Chile
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Egypt
- 5.4.5.4 South Africa
- 5.4.5.5 Morocco
- 5.4.5.6 Rest of Middle East and Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Air Systems Components, Inc.
- 6.4.2 Carrier Global Corporation
- 6.4.3 Cincinnati Fan
- 6.4.4 Daikin Industries, Ltd.
- 6.4.5 ebm-papst Group
- 6.4.6 FlaktGroup Holding GmbH
- 6.4.7 Greenheck Fan Corporation
- 6.4.8 Howden Group Ltd
- 6.4.9 Johnson Controls International plc
- 6.4.10 Loren Cook Company
- 6.4.11 Munters Group AB
- 6.4.12 New York Blower Company
- 6.4.13 Rosenberg Ventilatoren GmbH
- 6.4.14 Soler & Palau Ventilation Group
- 6.4.15 Systemair AB
- 6.4.16 Trane Technologies plc
- 6.4.17 Twin City Fan Companies, Ltd.
- 6.4.18 Vent-Axia
- 6.4.19 Zhejiang Shangfeng Industrial Group Co., Ltd.
- 6.4.20 Zhejiang Yilida Ventilator Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


