

|
시장보고서
상품코드
2154413
바이오수소 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Bio Hydrogen - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
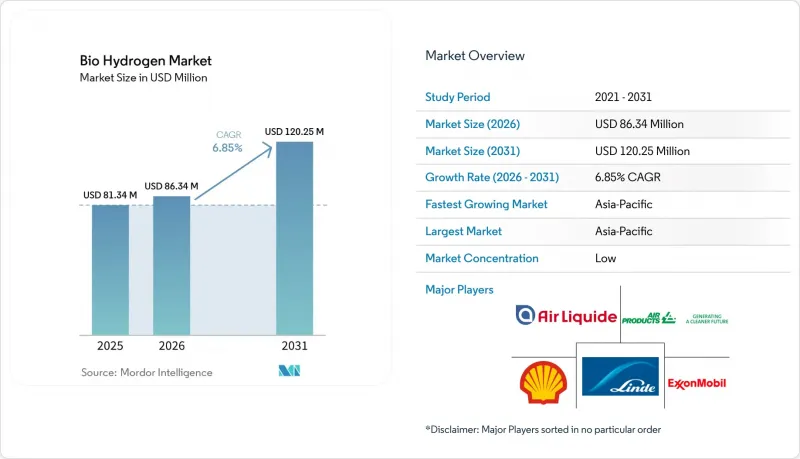
에 따르면 바이오수소 시장 규모는 2025년에 8,134만 달러로 추계되고 있으며, 예측 기간(2026-2031년)에 CAGR 6.85%로 확대하며, 2026년 8,634만 달러에서 2031년에는 1억 2,025만 달러에 달할 것으로 전망되고 있습니다.
세계 바이오수소 시장의 동향 및 인사이트
감축이 어려운 수소 수요의 탈탄소화
바이오수소 시장은 철강, 정유, 시멘트, 암모니아 생산업체들이 검증 가능한 저탄소 수소를 조달해야 한다는 압박으로부터 혜택을 받고 있습니다. 이러한 부문은 직접 전기화에 전적으로 의존할 수 없기 때문에 수소의 출처와 배출 프로필이 상업적으로 더욱 중요해지고 있습니다. 2026년 6월 초까지 유럽연합(EU) 회원국 13개국이 운송 부문의 재생에너지 지침을 국내법에 반영하는 작업을 완료했습니다. 그 결과 마련된 프레임워크를 통해 지속가능성 속성이 문서화된 저배출 수소에 대해 연간 575킬로톤(ktpa)을 초과하는 수요가 창출되었습니다. 바이오매스 가스화와 탄소 포집을 결합함으로써 CertifHy가 정한 음의 배출 요건을 충족할 수 있으며, ISO 19880 시리즈에 기반한 수소 품질 기준 준수도 지원할 수 있습니다. 영국의 평가에 따르면 탄소 포집 및 저장(CCS)을 동반한 바이오매스 가스화가 상업적으로 가장 발전된 ‘수소 바이오에너지·탄소 포집 및 저장(H2BECCS)’ 경로로 확인되었습니다. 한편, 하이브리드 가스화 및 고체 산화물 연료 전지 시스템은 최대 55%의 효율을 달성했습니다.
탄소 포집은 인증된 음의 배출 제품을 실현함으로써 바이오수소 시장에서 생물 유래 수소의 역할을 변화시킵니다. 이 특징은 구매자가 단순히 운영시 배출량 감축뿐만 아니라 문서화된 지속가능성 속성을 요구할 때 중요해집니다. 또한 전력망에서 발생하는 배출량이 여전히 상당한 경우, 생물 유래 수소 제조 공정을 전해 방식으로 생산된 수소와 차별화하는 데에도 도움이 됩니다. 그 결과 발생하는 프리미엄은 원료의 수집, 전환, 회수 및 배송에 걸친 추적 가능성과 연결됩니다. 따라서 개발자는 인증 시스템을 생산 개시 후의 행정적 절차가 아닌, 프로젝트 설계의 일부로 다루어야 합니다. 이러한 요건으로 인해 바이오매스의 출처와 각 전환 단계에 수반되는 배출량을 모두 문서화할 수 있는 프로젝트가 유리해집니다.
폐기물 흐름의 효율적 활용과 순환형 수소 생산
폐기물 전환은 처분 의무를 잠재적인 생산 투입물로 전환함으로써 바이오수소 시장을 지원하고 있습니다. 2024년 5월, 중국은 농업, 임업 및 도시 지역의 유기성 폐기물 연간 배출량이 35억 톤을 초과했다고 보고했습니다. 보고된 이용률은 14% 미만으로, 이러한 물질을 수집·처리할 수 있는 프로젝트의 경우 원료가 크게 남게 됩니다. 폐기물 처리 업체는 처분 비용과 매립 처분에 대한 의존도를 줄일 수 있는 반면, 수소 생산자는 저비용 또는 사실상 무비용으로 원료를 확보할 수 있습니다. 이러한 구조는 단일 성장률만으로는 파악할 수 없는 방식으로 프로젝트의 경제성을 향상시킬 수 있습니다. 또한 바이오수소 시장을 순환형 경제 정책 및 지역의 폐기물 관리 의무와 연계하는 역할도 수행합니다.
식품 폐기물, 도시 유기물, 농업 잔여물은 수분 함량, 불순물, 취급 요건이 서로 다릅니다. 이러한 차이에 따라 각 현장에서 어떤 생물학적 또는 열화학적 공정이 적합한지가 결정됩니다. 단일 현장에서 폐기물 관리, 수소 생산, 환경 의무 이동을 동시에 실현할 수 있다면 프로젝트의 경제성은 향상됩니다. 이러한 프로젝트에는 신뢰성 높은 수거 시스템과 폐기물 소유자와의 명확한 합의가 필요합니다. 현장 수준의 프로젝트에서는 폐기물 매립 처리비 절감 효과와 수소 판매, 그리고 환경 규정 준수를 결합할 수 있습니다. 이 모델은 폐기물 소유자, 지자체 및 수소 구매자가 장기 계약을 체결할 수 있는 경우에 효과적입니다.
높은 단위 생산 비용과 낮은 수소 수율
생산 비용은, 특히 생물학적 전환 경로의 경우, 바이오수소 시장에 있으며, 여전히 가장 시급한 제약 요인으로 남아 있습니다. 원료 조성의 편차는 수율을 제한하며, 대규모 전해 시설이나 수증기 메탄 개질 시설에서 얻을 수 있는 규모의 경제를 저해할 가능성이 있습니다. 2025년 기술경제 분석에 따르면 미생물 전해 셀과 통합된 다크 발효 방식에서는 전류 밀도 20 A/m²에서 1kg당 17-30달러의 비용으로 수소를 생산할 수 있는 것으로 나타났습니다. 전류 밀도를 100 A/m²로 높이면, 모델 시산에 따른 비용은 1kg당 4-6.9달러로 낮아졌습니다. 다만, 전류 밀도가 상승함에 따라 재료의 내구성에 대한 우려도 커지는데, 이는 상업 운영에서 여전히 해결되지 않은 문제로 남아 있습니다. 인센티브를 통해 이러한 격차를 줄일 수는 있지만, 지원 체계가 갖춰지지 않은 지역에서 발생하는 기술적·재정적 위험을 완전히 배제할 수는 없습니다.
원료 내의 불순물 또한 제약 요인이 됩니다. 혼합 유기물은 생물학적 공정을 저해하고, 플랜트 운영을 복잡하게 만들 가능성이 있기 때문입니다. 농업 폐기물이나 산업 폐기물은 전환 전에 선별, 전처리 또는 공정 제어가 필요할 수 있습니다. 이러한 요건은 소규모 분산형 시설에서 설비 투자 비용과 운영 비용을 상승시킬 가능성이 있습니다. 기술 선정 시에는 수분 함량, 화학 조성 및 공급 안정성을 고려해야 합니다. 탄소 크레딧이나 폐기물 처리 수수료로 인한 수익은 경제성을 향상시킬 수 있지만, 어느 수입원도 안정적인 수소 생산량의 필요성을 배제하지는 않습니다. 바이오수소 시장에는 수소 생산량을 관리하는 것만큼이나 신중하게 원료의 품질을 관리하는 운영 모델이 필요할 것입니다.
부문 분석
2025년 기준, 바이오수소 시장에서 바이오매스 가스화의 점유율은 35.80%를 차지했으며, 2031년까지의 예측 연평균 성장률(CAGR)은 7.35%로 가장 높은 수치를 기록했습니다. 이러한 이중적 위상은 해당 기술의 확고한 역할과 지속적인 성장 가능성을 반영합니다. 가스화 기술은 농업 및 임업 공급망 전반에서 입수 가능한 고체 리그노셀룰로오스계 물질을 처리할 수 있습니다. 또한 배출 성능을 향상시킬 수 있는 탄소 포집 시스템과도 호환됩니다. IEA 바이오에너지 태스크 33은 2050년까지의 H2BECCS 도입 전망에서 가스화 기술을 가장 신뢰할 수 있는 경로로 지목했습니다. 이 평가에서는 탄소 포집 측면 외에도 전 세계에서 확립된 상업적 운영 사례가 언급되었습니다.
지역별 분석
아시아태평양은 2025년에 바이오수소 시장 점유율의 29.71%를 차지할 것으로 예상되며, 2031년까지 지역별 가장 높은 연평균 성장률(CAGR) 7.29%를 기록할 것으로 전망됩니다. 이 지역은 풍부한 바이오매스 공급, 정부의 지원 정책, 그리고 연료전지 도입 확대의 혜택을 받고 있습니다. 중국의 ‘제15차 5개년 계획’에서는 바이오 유래 수소가 전략적 우선 과제로 자리매김하고 있습니다. 2026년 3월, 공업정보화부, 재정부, 국가발전개혁위원회가 발표한 공고에서는 도시 클러스터의 투자를 다양한 수소 최종 용도로 전환하고, 특히 농업 폐기물 및 유기 폐기물 유래 바이오수소를 지원하도록 지시했습니다. 인도에서는 60건의 수소 프로젝트가 진행 중이며, 총 투자액은 1050억 달러로 추정됩니다. 또한 초기 단계의 암모니아 구매 계약을 통해 개발 사업자는 구매처를 확보할 수 있었습니다.
일본에서는 2026년 5월 하순까지 연간 약 13만 톤의 저배출 수소를 지원하는 차액결제계약(CFD)이 체결되었습니다. 한국은 바이오매스가 풍부한 아세안(ASEAN) 국가들을 대상으로 한 바이오수소 수입 허브로서의 위상을 확립하고자 하고 있습니다. 태국과 인도네시아는 볏짚을 원료로 하는 수소 제조 공정에서 화석 수소에 비해 온난화 잠재력이 55-60% 감소한 것으로 나타나, 그 유효성을 입증하는 사례가 되고 있습니다. 북미와 유럽은 각각 지역별 점유율에서 2위와 3위를 차지했습니다. 미국에서는 섹션 45V에 따라 수명 주기 배출량 성과가 검증된 적격 프로젝트를 지원할 수 있습니다. 유럽의 정책적 영향력도 수소 경매 제도와 지속가능성 관련 규정을 통해 발휘되고 있습니다.
유럽 수소 은행의 제3차 입찰에서는 유럽 경제 지역(EEA) 7개국에 걸친 9개 프로젝트에 10억 유로(11억 6,000만 달러) 이상이 지원되었으며, 이는 약 1.1 GW의 용량에 해당합니다. 남미, 중동 및 아프리카는 바이오수소 시장에서 여전히 초기 단계에 있는 지역입니다. 브라질은 에탄올 인프라를 활용하여 현장 개질을 수행함으로써 가스화 설비에 대한 신규 투자를 피할 수 있습니다. 사우디아라비아의 ‘비전 2030’ 프로그램은 폐기물 처리 체계가 정비됨에 따라 생물 유래 원료를 활용할 가능성이 있는 상류 부문의 수소 투자를 추진하고 있습니다. 규제 차이와 인프라 부족으로 인해 중동 및 아프리카의 단기적인 진전은 제약을 받고 있지만, 향후 수출 경로와 EU의 인증 요건에 따라 이 지역들은 장기적으로 중요한 역할을 수행할 가능성이 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 생산 기술별
- 원료별
- 용도별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 러시아
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- Air Liquide
- Air Products and Chemicals, Inc.
- Ballard Power Systems
- Cummins Inc.
- Enapter AG
- ENGIE
- Exxon Mobil Corporation
- ITM Power plc
- Linde PLC
- McPhy Energy
- Nel ASA
- Plug Power Inc.
- Shell plc
- Siemens Energy
- Sunfire SE
제7장 시장 기회와 향후 전망
KSAAccording to Mordor Intelligence, the bio hydrogen market size was estimated at USD 81.34 million in 2025 and is estimated to grow from USD 86.34 million in 2026 to USD 120.25 million by 2031, at a CAGR of 6.85% during the forecast period (2026-2031).
Global Bio Hydrogen Market Trends and Insights
Decarbonization of Hard-to-Abate Hydrogen Demand
The biohydrogen market benefits from pressure on steel, refining, cement, and ammonia producers to obtain verifiable low-carbon hydrogen. These sectors cannot fully rely on direct electrification, making the origin and emissions profile of hydrogen more commercially important. By early June 2026, 13 European Union member states had completed the transposition of the Renewable Energy Directive for transport. The resulting framework created demand for more than 575 kilotons per annum (ktpa) of low-emission hydrogen with documented sustainability attributes . Biomass gasification paired with carbon capture can meet negative-emissions requirements under CertifHy and support compliance with hydrogen quality standards under the ISO 19880 series. A UK assessment identified biomass gasification with carbon capture and storage as the most commercially advanced Hydrogen Bioenergy with Carbon Capture and Storage (H2BECCS) route, while hybrid gasification and solid oxide fuel cell systems achieved efficiencies of up to 55%.
Carbon capture changes the role of biogenic hydrogen within the biohydrogen market by enabling a certified negative-emissions product. This feature is relevant where buyers require documented sustainability attributes rather than only lower operational emissions. It also helps differentiate biogenic pathways from hydrogen produced through electrolysis when grid emissions remain material. The resulting premium is tied to traceability across feedstock collection, conversion, capture, and delivery. Developers therefore need to treat certification systems as part of project design rather than as an administrative step after production begins. This requirement favors projects that can document both the origin of the biomass and the emissions associated with each conversion stage.
Waste-Stream Valorization and Circular Hydrogen Production
Waste conversion supports the biohydrogen market by turning a disposal obligation into a potential production input. In May 2024, China reported annual agricultural, forestry, and urban organic waste output exceeding 3.5 billion tons. The reported utilization rate was below 14%, resulting in a substantial feedstock surplus for projects capable of collecting and processing these materials. Waste handlers can reduce disposal costs and exposure to landfill, while hydrogen producers can obtain feedstocks at low or negative cost. This structure can improve project economics in ways that a single growth rate does not capture. It also connects the biohydrogen market with circular economy policies and local waste-management obligations.
Food waste, municipal organic material, and agricultural residues differ in moisture content, contaminants, and handling requirements. These differences influence which biological or thermochemical route is appropriate at each site. Project economics improve when a single site can manage waste, produce hydrogen, and meet environmental obligations. Such projects require reliable collection systems and clear agreements with waste owners. Site-level projects can combine avoided waste-tipping fees with hydrogen sales and environmental compliance. This model is relevant where waste owners, municipalities, and hydrogen buyers can coordinate long-term contracts.
High Unit Production Cost and Low Hydrogen Yield
Production cost remains the most immediate restraint on the bio hydrogen market, especially for biological conversion pathways. Variable feedstock composition can limit yields and prevent the scale benefits available to large electrolysis and steam methane reforming facilities. A 2025 techno-economic analysis found that dark fermentation integrated with microbial electrolysis cells produced hydrogen at USD 17-30 per kg at a current density of 20 A/m2. Raising current density to 100 A/m2 reduced the modeled cost to USD 4-6.9 per kg. Higher current density also raises materials durability concerns that remain unresolved in commercial operation. Incentives can narrow the gap, but they do not eliminate technical and financial risks in unsupported locations.
Feedstock contaminants pose another limitation, as mixed organic material can inhibit biological processes and complicate plant operations. Agricultural and industrial waste streams may require sorting, pretreatment, or process controls before conversion. These requirements can raise capital and operating costs at smaller distributed sites. Technology selection must account for moisture content, chemical composition, and supply consistency. Carbon-credit or waste-fee revenue can improve the economics, but neither revenue stream removes the need for stable hydrogen yields. The bio hydrogen market will need operating models that manage feedstock quality as carefully as they manage hydrogen output.
Other drivers and restraints analyzed in the detailed report include:
- Policy Incentives and Hydrogen Certification Demand
- Fuel-Cell and Low-Carbon Fuel Adoption
- Immature Storage, Distribution, and Offtake Infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Biomass gasification held 35.80% of the bio hydrogen market share in 2025 and recorded the highest projected CAGR of 7.35% through 2031. This dual position reflects its established role and continued growth potential. Gasification can process solid lignocellulosic materials available across agricultural and forestry supply chains. It also aligns with carbon capture systems that can improve emissions performance. IEA Bioenergy Task 33 identified gasification as the pathway with the highest confidence in H2BECCS deployment projections through 2050. The assessment cited established global commercial operations, alongside the carbon-capture layer.
Complete Report Scope:
- By Production Technology
- Biomass Gasification
- Dark Fermentation
- Photofermentation
- Others
- By Feedstock
- Agricultural Residues
- Food and Organic Waste
- Wastewater and Sewage Sludge
- Others
- By Application
- Transportation Fuel
- Power Generation
- Industrial Feedstock
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 29.71% of the bio hydrogen market share in 2025 and was projected to record the highest regional CAGR of 7.29% through 2031. The region benefits from extensive biomass availability, government commitments, and expanding fuel cell deployment. China's 15th Five-Year Plan identifies biogenic hydrogen as a strategic priority. A March 2026 notice from the Ministry of Industry and Information Technology, the Ministry of Finance, and the National Development and Reform Commission directed city-cluster investments toward diverse hydrogen end uses, specifically supporting bio hydrogen from agricultural and organic waste streams. India had 60 active hydrogen projects with an estimated combined investment of USD 105 billion, while early ammonia offtake agreements helped developers secure buyers.
Japan had issued contracts for difference supporting nearly 130 ktpa of low-emission hydrogen by late May 2026. South Korea is positioning itself as a bio hydrogen import hub for biomass-rich ASEAN economies. Thailand and Indonesia present a supporting case, as rice-straw pathways showed a 55-60% reduction in warming potential compared to fossil hydrogen. North America and Europe held the second- and third-largest regional shares, respectively. In the United States, Section 45V can support qualifying projects with verified lifecycle-emissions performance. Europe's policy influence is also channeled through hydrogen auction mechanisms and sustainability rules.
The European Hydrogen Bank's third auction awarded more than EUR 1 billion (USD 1.16 billion) to 9 projects across 7 European Economic Area countries, representing nearly 1.1 GW of capacity. South America, the Middle-East, and Africa remain earlier-stage regions within the bio hydrogen market. Brazil can leverage its ethanol infrastructure for on-site reforming, avoiding greenfield gasification investment. Saudi Arabia's Vision 2030 program is driving upstream hydrogen investment that could incorporate biogenic feedstocks as waste frameworks develop. Regulatory differences and infrastructure shortages constrain near-term progress in the Middle-East and Africa, although future export corridors and EU certification requirements could create a longer-term role for these regions.
- Air Liquide
- Air Products and Chemicals, Inc.
- Ballard Power Systems
- Cummins Inc.
- Enapter AG
- ENGIE
- Exxon Mobil Corporation
- ITM Power plc
- Linde PLC
- McPhy Energy
- Nel ASA
- Plug Power Inc.
- Shell plc
- Siemens Energy
- Sunfire SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Decarbonization of Hard-to-Abate Hydrogen Demand
- 4.2.2 Waste-Stream Valorization and Circular Hydrogen Production
- 4.2.3 Policy Incentives and Hydrogen Certification Demand
- 4.2.4 Fuel-Cell and Low-Carbon Fuel Adoption
- 4.2.5 Integrated Biohydrogen With Carbon Capture and Co-Products
- 4.3 Market Restraints
- 4.3.1 High Unit Production Cost and Low Hydrogen Yield
- 4.3.2 Immature Storage, Distribution and Offtake Infrastructure
- 4.3.3 Feedstock Contaminant Variability and Biological Process Inhibition
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Production Technology
- 5.1.1 Biomass Gasification
- 5.1.2 Dark Fermentation
- 5.1.3 Photofermentation
- 5.1.4 Others
- 5.2 By Feedstock
- 5.2.1 Agricultural Residues
- 5.2.2 Food and Organic Waste
- 5.2.3 Wastewater and Sewage Sludge
- 5.2.4 Others
- 5.3 By Application
- 5.3.1 Transportation Fuel
- 5.3.2 Power Generation
- 5.3.3 Industrial Feedstock
- 5.3.4 Others
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Air Liquide
- 6.4.2 Air Products and Chemicals, Inc.
- 6.4.3 Ballard Power Systems
- 6.4.4 Cummins Inc.
- 6.4.5 Enapter AG
- 6.4.6 ENGIE
- 6.4.7 Exxon Mobil Corporation
- 6.4.8 ITM Power plc
- 6.4.9 Linde PLC
- 6.4.10 McPhy Energy
- 6.4.11 Nel ASA
- 6.4.12 Plug Power Inc.
- 6.4.13 Shell plc
- 6.4.14 Siemens Energy
- 6.4.15 Sunfire SE
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


