

|
시장보고서
상품코드
2154435
디지털 알약 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Digital Pills - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
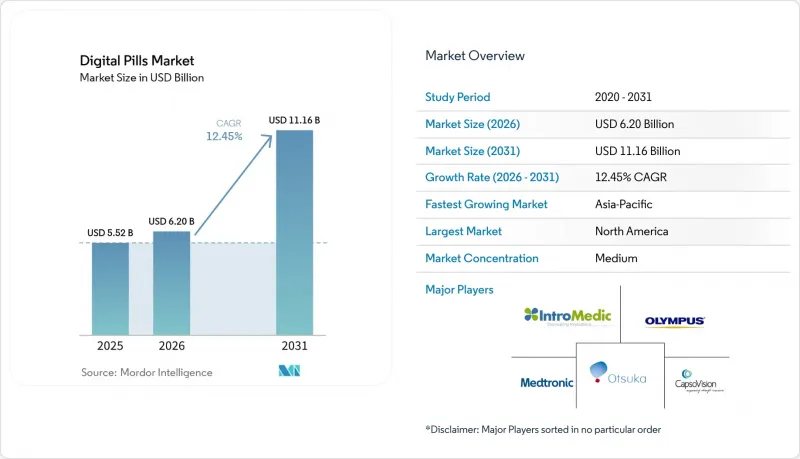
에 따르면 디지털 알약 시장 규모는 2025년 55억 2,000만 달러에서 2026년에는 62억 달러로 확대하며, 2026-2031년에 CAGR 12.45%로 추이하며, 2031년에는 111억 6,000만 달러에 달할 것으로 예측됩니다.
전 세계 디지털 알약 시장의 동향 및 인사이트
객관적인 복약 순응도 측정 확대가 핵심 수요를 견인
디지털 알약 시장은 의료진이 직접 관찰하는 상황 이외에는 복약 상태를 확인할 수 없는 경우가 많기 때문에 중요한 임상적 과제를 해결하는 역할을 합니다. 2026년에 실시된 PrEPSteps 중재에 관한 무작위 대조 시험에서 디지털 알약 시스템을 사용한 참가자의 3개월간 PrEP 복약 순응도가 대조군에 비해 14% 더 높은 것으로 나타났습니다. 이 결과는 의료 제공자가 복약 기록을 단순한 기록 관리에 그치지 않고 중재 전략과 결합할 수 있음을 보여주었습니다. 또한 이를 통해 치료 성과에 관한 보험사와의 논의도 강화되었습니다. 아울러 이 증거는 복약 누락이 치료 효과에 영향을 미칠 수 있는 만성질환 치료에서도 그 유효성을 입증하고 있습니다. 디지털 복약 준수 시스템을 통해 의료진은 정기적인 자가 보고보다 더 조기에 복약 누락 패턴을 파악할 수 있게 되었습니다. 의료 제공자가 이 정보를 기존의 환자 지원 프로세스에 통합함으로써 디지털 피임약 시장은 혜택을 볼 가능성이 있습니다. 그러나 기술만으로는 접근성, 신뢰 또는 치료상의 장벽과 같은 과제를 해결할 수는 없습니다.
분산형 및 하이브리드형 임상시험의 확대가 제약 업계에서 지속적인 수요를 창출
제약 기업은 특히 임상시험 방문 빈도가 낮은 경우, 피험자가 시험용 약물을 언제 복용했는지에 대한 신뢰할 수 있는 기록이 필요합니다. 2026년 리뷰에서는 2001-2025년까지 등록된 웨어러블 기기에서 얻은 데이터를 사용한 1,021건의 중재 임상시험을 평가하여, 의약품 개발에서 기기 기반 평가 지표의 활용이 확산되고 있음을 밝혔습니다. 섭취형 센서는 타임스탬프가 포함된 복약 기록을 제공하여 다른 원격 데이터 소스를 보완했습니다. 이러한 시스템 덕분에 분산형 및 하이브리드형 임상시험 설계에서 환자의 기억이나 정제 수에 대한 의존도가 감소했습니다. FDA는 2026년 7월, 의약품 및 생물제제의 임상 연구에서 디지털 헬스 기술에 관한 협력 협정 ‘RFA-FD-26-012’를 공표했습니다. 이 공모에서는 110만 달러의 자금이 지원되며, 2건의 선정이 예상되며, 디지털 헬스 평가 지표 및 소아 환자 모니터링이 대상이 되었습니다.
센서를 활용한 치료의 높은 총비용이 광범위한 도입을 저해
센서를 활용한 치료에는 센서 본체 이상의 요소가 관여합니다. 공동 인캡슐레이션, 기기 제공, 소프트웨어 서비스, 규제 준수 및 운영 지원이 필요할 수 있습니다. 처방전이 필요한 디지털 치료제에 대한 분석 결과, 환자의 접근성을 개선하기 위해서는 정책 및 보험 급여 조치가 매우 중요하다는 사실이 밝혀졌습니다. 이러한 추가 요소들로 인해 치료비는 기본 약제 비용을 초과할 가능성이 있습니다. 그 결과, 복약 순응도가 치료 성과에 명확한 영향을 미치는 사용 사례나 이미 보험 급여 제도가 마련된 경우에서 초기 도입이 더 현실적입니다. ‘디지털 알약’ 시장에서는 명확한 지불 경로가 확립된 사용 사례에서 단기적인 비즈니스 기회가 더 크다고 할 수 있습니다.
비용은 진단용 캡슐과 복약 순응도 시스템 간의 경쟁에도 영향을 미칩니다. 캡슐 내시경은 많은 의료 현장에서 확립된 소화기 계통 검사 절차를 활용할 수 있다는 장점이 있습니다. 반면, 복약 순응도 플랫폼은 서비스 모델에 기기, 소프트웨어 및 사후 관리가 포함되므로 대부분의 경우 보험사와의 별도 협의가 필요합니다. 이러한 차이로 인해 수익 모델이 더 명확한 진단 용도에 대한 투자가 우선시될 가능성이 있습니다. 또한 본래는 복약 순응도 모니터링의 혜택을 받을 수 있어야 할 치료법에서도 그 도입이 지연될 가능성이 있습니다. 임상적 신뢰성을 유지할 수 있는 한, 저비용 하드웨어와 보다 효율적인 치료 과정은 접근성 향상으로 이어질 수 있습니다.
부문 분석
캡슐은 2025년 매출의 61.40%를 차지하며, 제품 유형별로는 디지털 알약 시장에서 가장 큰 점유율을 차지하고 있습니다. 그 설계 덕분에 유효 성분을 변경하지 않고도 기존 제제에 센서를 추가할 수 있으므로, 재개발의 필요성이 줄어듭니다. 캡슐 내시경은 보험 급여의 지원을 받아 위장관 영상 진단 분야에서 확고한 입지를 유지하고 있으며, 후지필름, 올림푸스, CapsoVision, AnX Robotica 및 여러 아시아 제조업체가 이 부문에 참여하고 있습니다. 마이크로칩 전달 장치는 여전히 초기 단계의 하위 부문이며, 서방형 및 표적 지향형 소화관 전달에 대한 상업적 도입은 2028년 이후가 될 것으로 예상됩니다.
정제용 디지털 알약 시장 규모는 2031년까지 연평균 성장률(CAGR) 13.65%로 확대될 것으로 예측됩니다. 정제 기반의 경구 투여형 이벤트 마커 시스템은 아리피프라졸을 함유한 ‘아빌리파이 마이사이트(Abilify MyCite)’가 입증한 바와 같이, 기존의 경구용 약물 형태에 센서를 통합한 것입니다. 2026년 연구에 따르면 손목 밴드형 수신기를 갖춘 정제 기반 디지털 알약 시스템에서 시스템이 감지한 복용 횟수와 정제 수량 간에 0.75의 피어슨 상관계수가 보고되었습니다. 블리스터 팩이나 스트립형 디스펜서와의 호환성은 약국 주도의 복약 순응도 프로그램을 지원하지만, 성장 여부는 환자, 약국, 의료진에게 가치를 입증할 수 있는지에 달려 있습니다.
2025년 매출 중 복약 순응도 분야가 34.55%를 차지하며 가장 큰 애플리케이션 점유율을 기록했습니다. 이 분야는 특히 치료 결과가 정기적인 복약에 좌우되는 경우, 환자가 처방된 치료를 확실히 받고 있는지 확인해야 할 필요성에 부응합니다. 2025년 임상 연구에서는 경구용 HIV 노출 전 예방(PrEP)의 복약 순응도를 지원하는 실시간 디지털 중재가 검증되었습니다. 약물전달, 질환 관리 및 기타 사용 사례가 나머지 사용 사례를 차지했으나, 도입은 보험 급여 및 진료팀과의 협력에 달려 있었습니다.
환자 모니터링용 디지털 알약 시장 규모는 2031년까지 연평균 성장률(CAGR) 14.51%로 확대될 것으로 예측됩니다. 경구 투여형 시스템은 복용 정보 외에도 위장 pH 값, 통과 시간, 온도 데이터를 수집할 수 있습니다. AnX Robotica사의 ‘MotiliCap’은 위 내용물 배출, 소장 통과 및 대장의 운동성을 평가하기 위해 2025년 5월 FDA의 510(k) 승인을 획득했습니다. 이 시스템은 치료 관리 및 소화관 진단을 지원하지만, 의료진이 검사 결과를 임상적 조치로 연결하기 위해서는 명확한 워크플로가 필요합니다.
지역별 분석
2025년, 북미는 매출의 42.45%를 차지하며 디지털 알약의 최대 지역 시장이 되었습니다. 이 지역에서는 확립된 FDA 승인 절차, 캡슐 내시경의 보급 기반, 그리고 디지털 의료에 대한 보험 환급에 대한 관심 증가가 맞물려 있으며, 미국 의사협회(AMA)의 디지털 의료 지불 자문 그룹이 코딩 및 보험 환급에 관한 검토를 지원하고 있습니다. 또한 재향군인부(VA) 병원, 이식 클리닉, 행동 의료 센터가 참여하는 ID-Cap의 임상 연구 프로그램을 통해 미국은 계속해서 중심적인 역할을 수행하고 있습니다. 캐나다는 캡슐 내시경에 대한 병원 주도의 수요를 주도하고 있는 반면, 멕시코는 여전히 소규모 시장이지만 만성질환 관리의 디지털화를 통해 잠재적인 성장이 기대되고 있습니다.
2025년 기준, 유럽은 지역별 시장 규모에서 2위를 차지했습니다. 독일, 영국, 프랑스에서는 확립된 진단 관행에 힘입어 소화기 질환에 대한 캡슐 내시경의 임상적 활용이 촉진되었습니다. 그러나 복약 순응도 지원 시스템의 경우 국가별로 시장 진입 요건이 상이하여, 각국의 승인 절차로 인해 신규 의료기기의 상용화까지 소요되는 기간이 길어졌습니다. 또한 GDPR(일반 데이터 보호 규정) 요건에 따라 동의 획득, 데이터 관리 및 개인정보 보호에 관한 명확한 정보 제공이 도입 과정에서 매우 중요해졌습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 15.20%로 성장할 것으로 예측되며, 이는 모든 지역 중 가장 높은 수치입니다. 규제 현대화, 진단 능력 확대, 그리고 결핵 및 간염으로 인한 높은 질병 부담이 이 지역의 성장을 지원하고 있습니다. 한국은 2025년 1월 ‘디지털 의료기기법’을 제정했으며, 2026년 중반까지 CONNECT DTx 플랫폼은 서울 수도권 3차 의료기관의 42%에 도입되어 누적 처방 건수가 3,300건을 넘어섰습니다. 중국에서는 디지털 치료 제품의 유통 경로가 정비되고 있으며, 중동 및 아프리카 및 남미에서는 GCC 국가들의 의료 현대화와 브라질 규제 당국의 관심을 통해 장기적인 기회가 기대되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류·공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 적응증별
- 질환별
- 최종사용자별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽 국가
- 아시아태평양
- 중국
- 인도
- 일본
- 호주
- 한국
- 기타 아시아태평양 국가
- 중동 및 아프리카
- GCC
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 북미
제6장 경쟁 구도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- AccuHealth Technologies
- AnX Robotica Corp.
- Bio-Images Research Ltd.
- CapsoVision, Inc.
- Check-Cap Ltd.
- Chongqing Jinshan Pharmaceutical Co., Ltd.
- Cosmo Pharmaceuticals N.V.
- etectRx, Inc.
- Fujifilm Corporation
- Given Imaging Ltd.
- IntroMedic Co., Ltd.
- Jinshan Science and Technology(Group) Co., Ltd.
- Medispec Ltd.
- Medtronic plc
- Olympus Corporation
- Otsuka Pharmaceutical Co., Ltd.
- PENTAX Medical
- Proteus Digital Health, Inc.
- RF Co., Ltd.
- Wision A.I.
제7장 시장 기회와 향후 전망
KSA 26.10.23According to Mordor Intelligence, the digital pills market size is expected to grow from USD 5.52 billion in 2025 to USD 6.20 billion in 2026 and is forecast to reach USD 11.16 billion by 2031 at 12.45% CAGR over 2026-2031.
Global Digital Pills Market Trends and Insights
Expansion of Objective Medication-Adherence Measurement Drives Core Demand
The Digital pills market addresses a key clinical challenge, as providers often cannot confirm medication intake outside of directly observed settings. A 2026 randomized trial of the PrEPSteps intervention found 14% higher PrEP adherence over three months among participants using a digital pill system than among controls. The findings showed that providers could combine ingestion records with interventions rather than use them only for recordkeeping. This also strengthened discussions with payers on treatment outcomes. The evidence also supported chronic therapies, where missed doses can affect treatment effectiveness. Digital adherence systems enabled care teams to identify missed-dose patterns earlier than periodic self-reporting. The Digital pills market may benefit when providers integrate this information into established patient-support processes. However, technology alone does not address access, trust, or treatment barriers.
Growth of Decentralized and Hybrid Clinical Trials Creates Sustained Pharma Demand
Drug developers need reliable records of when participants take study medication, particularly when trial visits occur less frequently. A 2026 review assessed 1,021 interventional trials registered from 2001 through 2025 that used wearable-derived data and identified broader use of device-based endpoints in drug development. Ingestible sensors provided time-stamped medication records that complemented other remote data sources. These systems reduced reliance on patient recall and pill counts in decentralized and hybrid trial designs. The FDA posted cooperative agreement RFA-FD-26-012 in July 2026 for digital health technologies in drug and biologic clinical investigations. The opportunity provided USD 1.1 million in funding, anticipated two awards, and covered digital health endpoints and pediatric patient monitoring.
High Total Cost of Sensor-Enabled Therapy Limits Broad Adoption
Sensor-enabled therapy involves more than the sensor itself. It may require co-encapsulation, device provision, software services, regulatory compliance, and operational support. An analysis of prescription digital therapeutics identified policy and reimbursement approaches as critical to improving patient access. These additional components can increase treatment costs beyond those of the base medication. Consequently, initial adoption is more practical in use cases where adherence clearly affects outcomes or where reimbursement is already available. The Digital Pills Market has stronger near-term opportunities in applications with defined payment pathways.
Cost also influences competition between diagnostic capsules and adherence systems. Capsule endoscopy benefits from established gastrointestinal procedures across many care settings. In contrast, adherence platforms often require separate payer discussions because their service models include the device, software, and follow-up care. This difference may direct investment toward diagnostic applications with clearer revenue models. It may also slow the adoption of ingestion monitoring in therapies that could otherwise benefit from it. Lower-cost hardware and more efficient care processes could improve access, provided they maintain clinical reliability.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Precedent for Ingestible Event Markers Reduces Market-Entry Risk
- Rising Demand for Remote Monitoring in Chronic Therapy Diversifies End-User Applications
- Limited Reimbursement and Unproven Outcomes at Scale Remain Structural Barriers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Capsules accounted for 61.40% of 2025 revenue, giving them the largest digital pills market share by product type. Their design allows sensors to be added to existing drug formulations without altering the active ingredient, reducing redevelopment requirements. Capsule endoscopy maintained an established role in gastrointestinal imaging, supported by reimbursement, with Fujifilm, Olympus, CapsoVision, AnX Robotica, and several Asian manufacturers participating in this segment. Microchip delivery devices remained an early-stage sub-segment, with commercial adoption for sustained-release and targeted gastrointestinal delivery expected beyond 2028.
The digital pills market size for tablets is projected to grow at a CAGR of 13.65% through 2031. Tablet-based ingestible event marker systems integrate sensors into conventional oral drug forms, as demonstrated by Abilify MyCite with aripiprazole. A 2026 study reported a Pearson correlation of 0.75 between system-detected ingestions and pill counts for a tablet-based digital pill system with a wristband receiver. Compatibility with blister-pack and strip-dispensing channels supports pharmacy-led adherence programs, although growth depends on demonstrating value for patients, pharmacies, and care teams.
Medication adherence accounted for 34.55% of 2025 revenue and represented the leading application share. The segment addresses the need to verify whether patients take prescribed therapies, particularly where treatment outcomes depend on consistent dosing. A 2025 clinical study examined a real-time digital intervention supporting oral HIV pre-exposure prophylaxis adherence. Drug delivery, disease management, and other applications accounted for the remaining use cases, while adoption depended on reimbursement and care-team integration.
The digital pills market size for patient monitoring is projected to expand at a CAGR of 14.51% through 2031. Ingestible systems can capture gastrointestinal pH, transit, and temperature data in addition to ingestion events. AnX Robotica's MotiliCap received FDA 510(k) clearance in May 2025 to assess gastric emptying, small bowel transit, and colonic motility. The system supports therapy management and gastrointestinal diagnostics, although providers require clear workflows to translate findings into clinical actions.
Complete Report Scope:
- By Product Type
- Tablet
- Capsule
- Microchip Delivery Device
- By Indication
- Medication Adherence
- Drug Delivery
- Patient Monitoring
- Disease Management
- Other Indications
- By Disease
- Cardiovascular Diseases
- Mental Disorders
- Infectious Diseases
- Diabetes
- Cancer
- Other Diseases
- By End User
- Hospitals
- Clinics
- Home Care Settings
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 42.45% of revenue in 2025, making it the largest regional market for digital pills. The region combines established FDA pathways, a developed capsule endoscopy base, and increasing focus on reimbursement for digital medicine. The American Medical Association's Digital Medicine Payment Advisory Group supports coding and reimbursement considerations, while the United States remains central through ID-Cap clinical research programs involving VA hospitals, transplant clinics, and behavioral health centers. Canada contributes hospital-based demand for capsule endoscopy, while Mexico remains a smaller market with potential driven by the digitalization of chronic disease management.
Europe was the second-largest regional market in 2025. Germany, the United Kingdom, and France supported the clinical use of capsule endoscopy for gastrointestinal disorders, supported by established diagnostic practices. However, adherence systems faced varying market access requirements, while national approval processes extended commercialization timelines for new devices. GDPR requirements made consent, data management, and clear communication of privacy protections critical to implementation.
Asia-Pacific is projected to grow at a CAGR of 15.20% through 2031, the highest among all regions. Regulatory modernization, expanding diagnostic capacity, and the high burden of tuberculosis and hepatitis support regional growth. South Korea enacted the Digital Medical Device Act in January 2025, and by mid-2026, the CONNECT DTx platform had reached 42% of tertiary hospitals in the Seoul metropolitan area and recorded more than 3,300 cumulative prescriptions. China is developing channels for digital therapeutic products, while the Middle East and Africa and South America offer longer-term opportunities through healthcare modernization in the GCC and regulatory interest in Brazil.
- AccuHealth Technologies
- AnX Robotica Corp.
- Bio-Images Research Ltd.
- CapsoVision, Inc.
- Check-Cap Ltd.
- Chongqing Jinshan Pharmaceutical Co., Ltd.
- Cosmo Pharmaceuticals
- etectRx, Inc.
- FUJIFILM
- Given Imaging Ltd.
- IntroMedic Co., Ltd.
- Jinshan Science and Technology (Group) Co., Ltd.
- Medispec Ltd.
- Medtronic
- Olympus
- Otsuka
- Pentax Medical
- Proteus Digital Health, Inc.
- RF Co., Ltd.
- Wision A.I.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Objective Medication-Adherence Measurement
- 4.2.2 Growth of Decentralized and Hybrid Clinical Trials
- 4.2.3 Regulatory Precedent for Ingestible Event Markers
- 4.2.4 Rising Demand for Remote Monitoring in Chronic Therapy
- 4.2.5 Pharmacy and Care-Team Integration of Dose-Level Data
- 4.2.6 Reusable Reader and Wearable-Form-Factor Innovation
- 4.3 Market Restraints
- 4.3.1 High Total Cost of Sensor-Enabled Therapy
- 4.3.2 Limited Reimbursement and Unproven Outcomes
- 4.3.3 Dose-Detection Failure and Data-Latency Risk
- 4.3.4 Patient Consent, Privacy and Workflow Friction
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Product Type
- 5.1.1 Tablet
- 5.1.2 Capsule
- 5.1.3 Microchip Delivery Device
- 5.2 By Indication
- 5.2.1 Medication Adherence
- 5.2.2 Drug Delivery
- 5.2.3 Patient Monitoring
- 5.2.4 Disease Management
- 5.2.5 Other Indications
- 5.3 By Disease
- 5.3.1 Cardiovascular Diseases
- 5.3.2 Mental Disorders
- 5.3.3 Infectious Diseases
- 5.3.4 Diabetes
- 5.3.5 Cancer
- 5.3.6 Other Diseases
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Clinics
- 5.4.3 Home Care Settings
- 5.4.4 Other End Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Strategic Moves
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.3.1 AccuHealth Technologies
- 6.3.2 AnX Robotica Corp.
- 6.3.3 Bio-Images Research Ltd.
- 6.3.4 CapsoVision, Inc.
- 6.3.5 Check-Cap Ltd.
- 6.3.6 Chongqing Jinshan Pharmaceutical Co., Ltd.
- 6.3.7 Cosmo Pharmaceuticals N.V.
- 6.3.8 etectRx, Inc.
- 6.3.9 Fujifilm Corporation
- 6.3.10 Given Imaging Ltd.
- 6.3.11 IntroMedic Co., Ltd.
- 6.3.12 Jinshan Science and Technology (Group) Co., Ltd.
- 6.3.13 Medispec Ltd.
- 6.3.14 Medtronic plc
- 6.3.15 Olympus Corporation
- 6.3.16 Otsuka Pharmaceutical Co., Ltd.
- 6.3.17 PENTAX Medical
- 6.3.18 Proteus Digital Health, Inc.
- 6.3.19 RF Co., Ltd.
- 6.3.20 Wision A.I.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


