

|
시장보고서
상품코드
2154795
남미의 프로세스 자동화 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South America Process Automation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
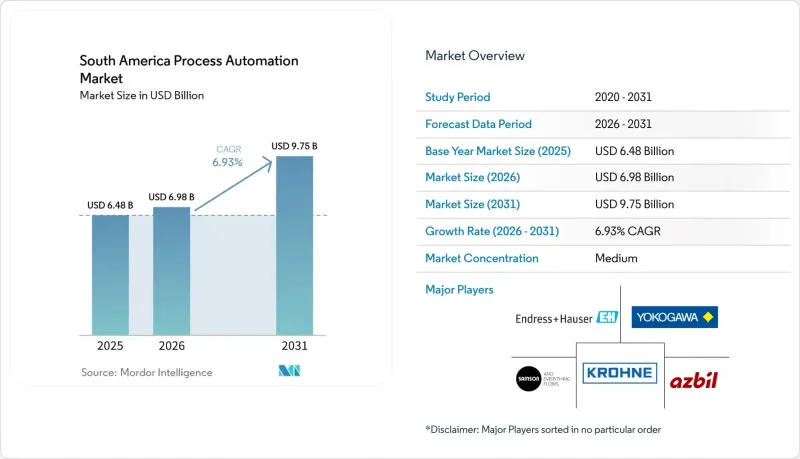
에 따르면 남미의 프로세스 자동화 시장 규모는 2025년에 64억 8,000만 달러로 평가되며, 2026년 69억 8,000만 달러에서 2031년까지 97억 5,000만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 6.93%가 될 전망입니다.
남미 프로세스 자동화 시장의 동향 및 인사이트
인더스트리 4.0 및 IIoT 도입
남미 전역에서 산업용 IoT(IIoT)의 도입으로 인해 현장 장치 정보가 운영 및 관리상의 의사결정에 더욱 밀접하게 활용되고 있습니다. 제조업체들은 계측기, 컨트롤러, 운영 소프트웨어를 연동함으로써 생산 시스템 전체의 가시성을 높이고 있습니다. 이러한 프로젝트를 통해 정기적인 운영 검토에서 보다 빈번한 모니터링으로의 전환이 용이해집니다. 또한, 연결된 아키텍처는 상호 연동되는 센서, 엣지, 클라우드 구성요소에 대한 수요도 창출하고 있습니다. 더 높은 품질의 데이터가 유지보수 계획 및 생산 관련 의사결정을 지원할 수 있다면, 그 도입의 정당성은 더욱 높아집니다. 따라서 프로젝트가 개별 장비 구매에서 통합 시스템으로 전환됨에 따라 남미의 공정 자동화 시장은 그 혜택을 누리고 있습니다.
산업용 자산의 현대화
많은 DCS 및 PLC 도입 시스템이 지원 종료 시기를 맞이함에 따라, 구형 시설의 현대화는 자동화 공급업체에게 여전히 주요 사업 원천이 되고 있습니다. 발메트(Valmet)는 브라질의 이라니 셀룰로오스(Irani Celulose)가 소유한 바르젬 보니타(Vargem Bonita) 공장에서 생산을 중단하지 않은 채 펄프 제조 라인, 증발 공정, 수처리, 가성 처리 각 구역에 설치되어 있던 기존 PLC에서 시스템을 마이그레이션했습니다. 이 프로젝트에서는 개별 제어 노드를 단일 플랫폼으로 통합하고, 신뢰성 관리를 위한 플랜트 데이터 접근성을 개선했습니다. 이러한 노력은 현대화의 가치가 단순히 하드웨어를 교체하는 것뿐만 아니라 정보를 통합함으로써 종종 창출된다는 점을 보여줍니다. 또한, 개방형 네트워크 접근 방식은 단일 공급업체에 얽매이는 것에 대한 우려를 완화하고, 교체 결정을 용이하게 할 가능성이 있습니다. 자산 소유자가 제어 시스템 업그레이드를 일회성 유지보수 작업이 아닌 장기적인 데이터 인프라로 인식함으로써, 남미의 공정 자동화 시장은 그 혜택을 누리게 될 것입니다.
자동화 프로젝트의 높은 초기 비용
초기 비용은 식품·음료, 화학, 포장 분야의 중소 제조업체에게 여전히 큰 장벽으로 작용하고 있습니다. 설비, 소프트웨어 및 현장 인프라의 업그레이드에는 중소기업이 당장 마련하기 어려운 자본이 필요할 수 있습니다. 브라질의 중소기업은 자동화 도입률에서 대기업에 비해 최대 2배나 뒤처져 있으며, 그 주요 장벽은 투자 비용입니다. 많은 제어 시스템, 센서, 정밀 기기가 달러나 유로로 구매되기 때문에 환율 변동도 추가적인 압박 요인이 되고 있습니다. 현지 통화 약세는 프로젝트 계획 단계에서 예상 수익을 변화시켜 승인 지연을 초래할 가능성이 있습니다. 자금 조달 마련, 단계적 도입 계획, 공공 융자 프로그램 등이 도움이 되지만, 그 적용 범위는 자동화 범주에 따라 여전히 불균일합니다.
부문 분석
2025년, 남미의 공정 자동화 시장에서 센서 및 트랜스미터는 20.12%의 점유율을 차지했습니다. 이 점유율은 석유·가스, 광업, 펄프·제지, 화학 산업에서 유량, 압력, 온도, 레벨 측정에 대한 지속적인 수요를 반영하고 있습니다. 연평균 성장률(CAGR) 8.06%를 기록하며, 시스템 유형 중 가장 높은 성장률을 보일 것으로 전망됩니다. 이러한 성장은 이미 핵심 현장 계측 장비를 도입한 사업자들의 2단계 투자를 반영한 것입니다.
Eurofarma Laboratorios는 2025년, 상파울루주 이타페비에 위치한 자사 시설에 코버(Korber)사의 PAS-X MES를 도입했습니다. 이 시스템은 200대 이상의 워크스테이션과 5개의 생산동을 포괄하고 있습니다. 도입 내용에는 전자 배치 기록, 추적성, 설비 설정, 세척 공정 및 전자 로그북이 포함되었습니다. 석유·가스 시설 및 공공사업은 장기 제어 계약에 의존하고 있기 때문에 DCS 및 SCADA에 대한 수요는 계속해서 견조합니다. 또한, 로컬 결정론적 제어가 중요한 식품 및 제약 제조 분야에서도 PLC 도입이 진행되고 있습니다. 공정 안전 시스템은 인증된 안전 기능이 필요한 화학 플랜트 및 리튬 시설을 지원합니다. 밸브, 액추에이터, 전동기, HMI, 분석 장비 및 상태 모니터링 장비가 시스템 스택을 구성하며, 이들은 일반적으로 남미 공정 자동화 시장의 설비 투자 확대에 따라 성장하고 있습니다.
2025년, 유선 프로토콜은 남미 공정 자동화 시장에서 74.31%의 점유율을 차지했습니다. 그 도입 실적은 기존 공정 플랜트나 예측 가능한 응답 시간이 필요한 안전상 중요한 용도에서 여전히 중요한 위치를 차지하고 있습니다. 석유·가스 사업자들도 위험 구역 내의 보호된 물리적 신호 경로를 중요하게 여기고 있습니다. 이더넷-APL은 이기종 혼합 플랜트 아키텍처에서 단일 2선식 케이블로 전력과 고속 데이터를 동시에 전송할 수 있는 능력을 입증했습니다. 이 기능을 통해 완전히 새로운 케이블 네트워크를 구축하지 않고도 계측 밀도를 높일 수 있습니다. 이로 인해 유선 프로토콜의 시장 점유율 감소 속도는 둔화될 수 있지만, 무선 연결의 필요성이 사라지는 것은 아닙니다.
무선 프로토콜은 2031년까지 연평균 성장률(CAGR) 8.29%로 성장할 것으로 예측되며, 이는 통신 부문에서 가장 높은 성장률입니다. 외딴 지역의 광산, 분산형 수처리 시설, 리튬 제조 시설에서는 모든 계측 지점에 구리 케이블을 설치할 필요가 없으므로 막대한 비용을 절감할 수 있습니다. 칠레와 브라질에서는 자율 운반 시스템, 환경 센서, 원격 제어 센터를 연결하기 위해 사설 5G 네트워크가 활용되고 있습니다. ISA100 및 WirelessHART는 공정 운영자가 필드버스 대신 신뢰할 수 있고 안전한 대안을 필요로 하는 분야에서 보급이 확대되고 있습니다. 무선 지원 트랜스미터는 유선형에 비해 15-30%의 가격 프리미엄이 붙었습니다. 이러한 변화는 장비 구성을 바꾸고, 남미의 공정 자동화 시장에서 평균 판매 가격 상승을 뒷받침하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 업계 밸류체인 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
- 거시경제 요인이 시장에 미치는 영향
제5장 시장 규모와 성장 예측
- 시스템 유형별
- 통신 프로토콜별
- 최종 이용 산업별
- 전개 방식별
- 지역별
- 브라질
- 아르헨티나
- 칠레
- 콜롬비아
- 기타 남미 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Endress+Hauser AG
- Yokogawa Electric Corporation
- Azbil Corporation
- KROHNE Messtechnik GmbH
- Samson AG
- Pepperl+Fuchs SE
- Brooks Instrument LLC
- Badger Meter, Inc.
- Spirax-Sarco Engineering plc
- HIMA Paul Hildebrandt GmbH
- Mettler-Toledo International Inc.
- AMETEK, Inc.
- Valmet Flow Control Oy
- Omega Engineering, Inc.
- R. Stahl AG
- WIKA Alexander Wiegand SE & Co. KG
- SMC Corporation
- Festo SE & Co. KG
- Beckhoff Automation GmbH & Co. KG
- WEG S.A.
- Metso Corporation
- Burkert Fluid Control Systems
- KSB SE & Co. KGaA
제7장 시장 기회와 향후 동향
- 화이트 스페이스 및 미충족 수요 평가
According to Mordor Intelligence, the South America process automation market size was valued at USD 6.48 billion in 2025 and estimated to grow from USD 6.98 billion in 2026 to reach USD 9.75 billion by 2031, at a CAGR of 6.93% during the forecast period (2026-2031).
South America Process Automation Market Trends and Insights
Industry 4.0 and IIoT Adoption
Industrial Internet of Things deployments are bringing field-device information closer to operating and management decisions across South America. Manufacturers are connecting instruments, controllers, and operational software to improve visibility across production systems. These projects make it easier to move from periodic operating reviews toward more frequent monitoring. Connected architectures also create demand for sensor, edge, and cloud components that work together. The operating case becomes stronger where better data can support maintenance planning and production decisions. The South America Process Automation Market therefore benefits as projects move from individual equipment purchases toward integrated systems.
Industrial Asset Modernization
Modernizing older facilities remains a major source of work for automation suppliers because many DCS and PLC installations are approaching end-of-support. Valmet migrated Irani Celulose's Vargem Bonita mill in Brazil from existing PLCs across the fiberline, evaporation, water-treatment, and causticizing areas without stopping production. The project consolidated separate control nodes into a single platform and improved access to plant data for reliability management. Such work shows that the value of modernization often comes from integrating information, not only replacing hardware. Open networking approaches also reduce concerns about being tied to a single supplier and can make replacement decisions easier. The South America Process Automation Market gains when asset owners treat control upgrades as long-term data infrastructure rather than as a one-time maintenance event.
High Upfront Cost of Automation Projects
Upfront costs remain a significant obstacle for smaller manufacturers in the food and beverage, chemicals, and packaging sectors. Equipment, software, and site-infrastructure upgrades can require capital that smaller businesses cannot release quickly. Brazilian small and medium-sized enterprises lag large firms by up to 2 times in automation adoption rates, with investment costs being the main barrier. Currency volatility adds pressure because many control systems, sensors, and precision instruments are purchased in USD or EUR. A weaker local currency can alter expected returns during project planning and delay approval. Financing arrangements, phased deployment plans, and public loan programs can help, but their reach remains uneven across automation categories.
Other drivers and restraints analyzed in the detailed report include:
- Demand for Energy Efficiency and Process Optimization
- Rising Automation Demand in Mining and Metals
- Shortage of Skilled Automation and Instrumentation Personnel
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Sensors and Transmitters accounted for 20.12% of the South America Process Automation Market share in 2025. Their position reflects continuous requirements for flow, pressure, temperature, and level measurement in oil and gas, mining, pulp and paper, and chemicals. New biofuel and direct lithium extraction facilities add demand because these measurements are specified during plant design. Sensors also create the base data that supports advanced control, maintenance systems, and production analytics. Manufacturing Execution Systems are projected to record the fastest system-type growth at an 8.06% CAGR through 2031. This growth reflects a second phase of investment by operators that have already installed core field instrumentation.
Eurofarma Laboratorios deployed Korber's PAS-X MES at its Itapevi facility in Sao Paulo in 2025, covering more than 200 workstations and 5 production buildings. The rollout included electronic batch records, traceability, equipment setup, cleaning processes, and electronic logbooks. DCS and SCADA continue to hold substantial demand because oil and gas sites and utilities depend on long-duration control contracts. PLC adoption is also increasing in food and pharmaceutical manufacturing where local deterministic control is important. Process safety systems support chemical and lithium facilities that require certified safety functions. Valves, actuators, electric motors, HMI, analyzers, and condition-monitoring equipment complete the system stack and generally grow with broader capital spending in the South America Process Automation Market.
Wired Protocol held 74.31% of the South America Process Automation Market share in 2025. Its installed base remains important in established process plants and in safety-critical applications requiring predictable response times. Oil and gas operators also value protected physical signal paths in hazardous locations. Ethernet-APL has demonstrated the ability to combine power and high-speed data over a single two-wire cable in heterogeneous plant architectures. This capability can increase instrumentation density without requiring an entirely new cable network. It may slow the pace of wired-share loss, although it does not remove the need for wireless connectivity.
Wireless Protocol is projected to grow at an 8.29% CAGR through 2031, the fastest rate among communication segments. Remote mines, distributed water-treatment sites, and lithium facilities can avoid high costs by not having to lay copper cable to every measurement point. Chile and Brazil are using private 5G networks to link autonomous haulage systems, environmental sensors, and remote operating centers. ISA100 and WirelessHART are expanding where process operators need dependable and secure alternatives to the fieldbus. Radio-enabled transmitters carried a 15-30% price premium over wired equivalents. This shift changes the equipment mix and supports higher average selling prices within the South America Process Automation Market.
Complete Report Scope:
- By System Type
- Supervisory Control and Data Acquisition (SCADA)
- Programmable Logic Controller (PLC)
- Distributed Control System (DCS)
- Manufacturing Execution System (MES)
- Valves and Actuators
- Electric Motors
- Human Machine Interface (HMI)
- Process Safety Systems
- Sensors and Transmitters
- Other System Types
- By Communication Protocol
- Wired Protocol
- Wireless Protocol
- By End-User Industry
- Chemical and Petrochemical
- Paper and Pulp
- Water and Wastewater Treatment
- Energy and Utilities
- Oil and Gas
- Pharmaceutical
- Food and Beverages
- Other End-User Industries
- By Deployment Mode
- On-premise
- Cloud-based
- By Geography
- Brazil
- Argentina
- Chile
- Colombia
- Rest of South America
List of Companies Covered in this Report:
- Endress+Hauser AG
- Yokogawa Electric Corporation
- Azbil Corporation
- KROHNE Messtechnik GmbH
- Samson AG
- Pepperl+Fuchs SE
- Brooks Instrument LLC
- Badger Meter, Inc.
- Spirax-Sarco Engineering plc
- HIMA Paul Hildebrandt GmbH
- Mettler-Toledo International Inc.
- AMETEK, Inc.
- Valmet Flow Control Oy
- Omega Engineering, Inc.
- R. Stahl AG
- WIKA Alexander Wiegand SE & Co. KG
- SMC Corporation
- Festo SE & Co. KG
- Beckhoff Automation GmbH & Co. KG
- WEG S.A.
- Metso Corporation
- Burkert Fluid Control Systems
- KSB SE & Co. KGaA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Industry 4.0 and IIoT Adoption
- 4.2.2 Industrial Asset Modernization
- 4.2.3 Demand for Energy Efficiency and Process Optimization
- 4.2.4 Rising Automation Demand in Mining and Metals
- 4.2.5 Expansion of Pharmaceutical and Food Processing Capacity
- 4.2.6 Localized Engineering for Lithium, Biofuels, and Renewable Energy Projects
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost of Automation Projects
- 4.3.2 Shortage of Skilled Automation and Instrumentation Personnel
- 4.3.3 Industrial Connectivity and Cybersecurity Gaps
- 4.3.4 Fragmented Brownfield Infrastructure and Integration Complexity
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By System Type
- 5.1.1 Supervisory Control and Data Acquisition (SCADA)
- 5.1.2 Programmable Logic Controller (PLC)
- 5.1.3 Distributed Control System (DCS)
- 5.1.4 Manufacturing Execution System (MES)
- 5.1.5 Valves and Actuators
- 5.1.6 Electric Motors
- 5.1.7 Human Machine Interface (HMI)
- 5.1.8 Process Safety Systems
- 5.1.9 Sensors and Transmitters
- 5.1.10 Other System Types
- 5.2 By Communication Protocol
- 5.2.1 Wired Protocol
- 5.2.2 Wireless Protocol
- 5.3 By End-User Industry
- 5.3.1 Chemical and Petrochemical
- 5.3.2 Paper and Pulp
- 5.3.3 Water and Wastewater Treatment
- 5.3.4 Energy and Utilities
- 5.3.5 Oil and Gas
- 5.3.6 Pharmaceutical
- 5.3.7 Food and Beverages
- 5.3.8 Other End-User Industries
- 5.4 By Deployment Mode
- 5.4.1 On-premise
- 5.4.2 Cloud-based
- 5.5 By Geography
- 5.5.1 Brazil
- 5.5.2 Argentina
- 5.5.3 Chile
- 5.5.4 Colombia
- 5.5.5 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Endress+Hauser AG
- 6.4.2 Yokogawa Electric Corporation
- 6.4.3 Azbil Corporation
- 6.4.4 KROHNE Messtechnik GmbH
- 6.4.5 Samson AG
- 6.4.6 Pepperl+Fuchs SE
- 6.4.7 Brooks Instrument LLC
- 6.4.8 Badger Meter, Inc.
- 6.4.9 Spirax-Sarco Engineering plc
- 6.4.10 HIMA Paul Hildebrandt GmbH
- 6.4.11 Mettler-Toledo International Inc.
- 6.4.12 AMETEK, Inc.
- 6.4.13 Valmet Flow Control Oy
- 6.4.14 Omega Engineering, Inc.
- 6.4.15 R. Stahl AG
- 6.4.16 WIKA Alexander Wiegand SE & Co. KG
- 6.4.17 SMC Corporation
- 6.4.18 Festo SE & Co. KG
- 6.4.19 Beckhoff Automation GmbH & Co. KG
- 6.4.20 WEG S.A.
- 6.4.21 Metso Corporation
- 6.4.22 Burkert Fluid Control Systems
- 6.4.23 KSB SE & Co. KGaA
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-Space and Unmet-Need Assessment


