

|
시장보고서
상품코드
2154799
남미의 일회용 플라스틱 포장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South America Single-use Plastic Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
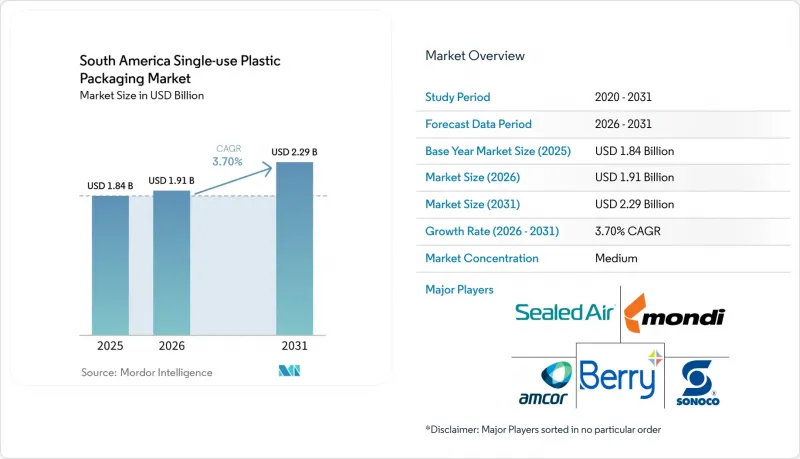
에 따르면 남미의 일회용 플라스틱 포장 시장 규모는 2025년에 18억 4,000만 달러로 평가되며, 2026년 19억 1,000만 달러에서 2031년까지 22억 9,000만 달러에 달할 것으로 예측되며, 2026년부터 2031년까지 예측 기간의 CAGR은 3.70%가 될 전망입니다.
남미 일회용 플라스틱 포장 시장의 동향 및 인사이트
음식 배달 및 퀵 서비스 레스토랑의 확대
음식 배달 및 퀵 서비스 레스토랑에서는 식품을 보호하고 안전한 취급을 가능하게 하는 포장이 요구됩니다. 배달 업체들이 주문 건마다 밀봉된 봉지, 트레이, 파우치를 사용함에 따라 남미의 일회용 플라스틱 포장 시장은 혜택을 보고 있습니다. 클라우드 키친에서는 신속한 조리 주기에 적합하기 때문에 필름 파우치, 변조 방지 트레이, 열밀봉 봉투가 사용되고 있습니다. 드라이브스루나 앱을 통한 주문에서는 개별 포장된 여러 상품을 하나의 보호용 외부 봉투에 함께 담는 경우가 있습니다. 이로 인해 레스토랑 메뉴가 간소화되더라도 주문 1건당 포장재 사용량은 증가할 가능성이 있습니다. 따라서 안전한 배달용 포장에 대한 수요는 외식 산업의 유통 채널이 확대됨에 따라 컨버터에 대한 안정적인 수요를 뒷받침하는 요인이 될 것입니다.
포장된 식품 및 음료 소비 확대
2025년, 브라질의 가공식품 생산량은 전년 대비 4.2% 증가했습니다. 이를 주도한 것은 수출 운송 중 차단 포장이 필요한 닭고기, 인스턴트 커피, 과일 농축액입니다. 소매업체와 외식 기업이 재충전이 용이한 형태를 요구하는 가운데, 조미료용 파우치 사용이 확대되고 있습니다. 이러한 변화로 인해 단위당 재료 중량을 줄이면서도 카테고리 전체에서 사용되는 포장 단위 수를 늘릴 수 있게 되었습니다. 기능성 음료, 에너지 드링크, 냉장 유제품에도 차단 기능을 갖춘 투명한 PET나 PP 용기가 요구되고 있습니다. 편의점의 확대에 따라, 분산된 유통망을 통해 제품을 보호할 수 있는 합리적인 가격의 포장에 대한 수요가 더욱 높아지고 있습니다. 이러한 수요로 인해 식품 및 음료 소비는 남미의 일회용 플라스틱 포장 시장에서 계속해서 중심적인 위치를 차지하고 있습니다.
일회용 플라스틱 규제와 확대된 생산자 책임(EPR)에 따른 비용
브라질의 연방령 제12,688/2025호는 플라스틱 포장에 관한 전국적인 역물류 체계를 확립했습니다. 이 체계에서는 2026년까지 32%의 회수 목표와 22%의 재활용 소재 함유율 요건이 설정되어 있으며, 대기업과 중소기업의 이행 시기는 다릅니다. 칠레에서는 2026년 2월, 음식점에서의 일회용 제품 사용을 제한하는 추가 요건이 도입되었습니다. 외식 사업자는 특정 제품에 대해 퇴비화 요건을 충족하거나 소비자의 요청이 있는 경우에만 매장 밖에서 제공할 수 있습니다. 이러한 규제로 인해 인증된 재활용 및 퇴비화 가능한 설계의 중요성이 커지고 있습니다. 또한, 다중 소재 구조에 의존하는 가공업체의 경우, 규정 준수, 시험 및 문서화에 드는 비용이 증가하게 됩니다.
부문별 분석
병 및 용기는 2025년 매출의 36.14%를 차지하고 있으며, 이는 강성과 제품의 가시성이 요구되는 음료, 의약품, 퍼스널케어 분야의 용도에 힘입은 것입니다. PET 및 PP 병은 조직화된 소매 업계에서 여전히 중요한 위치를 차지하고 있으며, 특히 무단 개봉 방지 포장 및 투명한 표시가 요구되는 브랜드 제품에서 중요합니다. 남미의 일회용 플라스틱 포장 시장에서 이러한 형태가 차지하는 점유율은 대량 생산되는 소비재와의 적합성을 반영합니다. 따라서 경질 병은 남미 일회용 플라스틱 포장 시장에서 안정적인 수요의 중요한 원천이 되고 있습니다. 봉지 및 파우치는 2031년까지 연평균 성장률(CAGR) 4.83%로 성장할 것으로 예측됩니다. 이러한 성장은 조미료, 유제품, 건조 식품 원료에 사용되는 경량 포장에 대한 수요를 반영하고 있습니다.
트레이, 컵 및 뚜껑은 조리된 식품의 주문량과 연동되는 외식 서비스 및 레스토랑 배달 분야에서 사용되고 있습니다. 열성형 기술의 발전으로 취급에 필요한 강도를 유지하면서 트레이의 두께를 얇게 만들 수 있게 되었습니다. 클램쉘은 상품이 보이므로 신선 식품 및 제빵 제품에 계속해서 유용합니다. 필름 및 랩은 산업용 스트레치 필름, 농업용 멀칭, 식품용 열밀봉 용도를 뒷받침하고 있습니다. 종이의 대체재는 특정 2차 포장 용도에서의 성장을 제한할 가능성이 있습니다. 콘스탄티아 플렉서블스는 LDPE 회수 시스템을 위해 설계된 단일 소재 PE 지퍼 파우치를 칠레에서 출시했습니다.
폴리에틸렌은 필름, 봉지, 병에 사용되기 때문에 2025년 소재 매출의 35.05%를 차지했습니다. 그 폭넓은 용도와 비용 측면의 우위가 남미 일회용 플라스틱 포장 시장의 수요를 뒷받침하고 있습니다. 또한 남미 일회용 플라스틱 포장 시장에서 컨버터에게 다양한 최종 용도에 대응할 수 있는, 구하기 쉬운 수지 기반을 제공하고 있습니다. PP는 캡, 전자레인지용 트레이, 내열성 식품 서비스 용기에 널리 사용되고 있습니다. PET는 투명 병과 식품용 트레이에서 여전히 중요한 역할을 하고 있습니다. 2025년 PET 현물 가격은 킬로그램당 1.06달러에 달한 반면, 재생 PET 가격은 킬로그램당 1.12달러였습니다.
칠레와 브라질의 각 지자체에서 규제가 시행됨에 따라 폴리스티렌 및 발포 폴리스티렌의 시장 진입이 제한되고 있습니다. 이로 인해 일부 외식 산업 용도에서 PP 및 PET 대체 소재에 대한 수요가 증가하고 있습니다. 폴리젖산은 2031년까지 연평균 성장률(CAGR) 4.62%를 기록할 것으로 예상되며, 이는 소개된 소재 중 가장 높은 성장률입니다. 브라질의 사탕수수 유래 에탄올 공급망은 바이오 기반 소재 개발을 촉진하고 있습니다. 브라스크엠(Braskem)은 2026년, 식품 접촉 용도, 의료 용도, 위생 용도를 위한 바이오 기반 및 순환형 폴리올레핀 제품을 발표했습니다. 또한, 브라질 정부는 식품 접촉 용도로 사용되는 PLA의 수입 관세를 인하하여, 인증을 받은 가공업체들의 채택을 촉진하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 거시경제 요인이 시장에 미치는 영향
- 업계 공급망 분석
- 기술 동향
- 규제 상황
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 소재 유형별
- 포장 형태별
- 용도별
- 최종사용자별
- 지역별
- 브라질
- 아르헨티나
- 콜롬비아
- 칠레
- 기타 남미 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Amcor plc
- Berry Global Group, Inc.
- Sealed Air Corporation
- Mondi plc
- Sonoco Products Company
- Huhtamaki Oyj
- ProAmpac Holdings Inc.
- Constantia Flexibles Group GmbH
- Coveris Management GmbH
- Transcontinental Inc.
- Winpak Ltd.
- ALPLA Werke Alwin Lehner GmbH & Co KG
- Plastipak Holdings, Inc.
- Valgroup Participacoes S.A.
- Logoplaste Group
- AptarGroup, Inc.
- CCL Industries Inc.
- Gerresheimer AG
- Graham Packaging Company, L.P.
- Comar, LLC
- ZARAPLAST S.A.
- Petropack S.A.
- EMUSA
- Megapack
제7장 시장 기회와 향후 전망
KSMAccording to Mordor Intelligence, the South America single-use plastic packaging market size was valued at USD 1.84 billion in 2025 and is estimated to grow from USD 1.91 billion in 2026 to reach USD 2.29 billion by 2031, at a CAGR of 3.70% during the forecast period 2026-2031.
South America Single-use Plastic Packaging Market Trends and Insights
Expansion of Food Delivery and Quick-Service Restaurants
Food delivery and quick-service restaurants require packaging that protects food and supports safe handling. The South America Single-use Plastic Packaging Market benefits when delivery operators use sealed bags, trays, and pouches for each order. Cloud kitchens use film pouches, tamper-evident trays, and heat-sealed bags because these formats are well-suited to rapid preparation cycles. Drive-through and app-based orders can include several individually packed items in one protected outer bag. This can increase the packaging used per order, even as restaurant menus become simpler. The requirement for secure delivery packaging, therefore, supports stable demand for converters as foodservice channels expand.
Growth of Packaged Food and Beverage Consumption
Brazil's processed-food output grew 4.2% year over year in 2025, led by poultry, instant coffee, and fruit concentrates that need barrier packaging during export transport. Pouches have gained use for condiments as retailers and foodservice companies seek refill-friendly formats. This shift can reduce the material weight of each unit while increasing the number of packaged units used in a category. Functional beverages, energy drinks, and chilled dairy products also require clear PET and PP containers with barrier properties. Growth in convenience retail creates further demand for affordable packs that can protect products through fragmented distribution networks. These needs keep food and beverage consumption central to the South America Single-use Plastic Packaging Market.
Single-Use Plastic Restrictions and Extended Producer Responsibility Costs
Brazil's Federal Decree No. 12,688/2025 established a national reverse-logistics framework for plastic packaging. The framework set a 32% recovery target and 22% recycled-content requirement for 2026, with different implementation dates for large and smaller companies. Chile introduced further requirements in February 2026 that restricted the use of single-use products in food establishments. Foodservice operators can provide certain products off-premises only when they meet compostability requirements or are requested by consumers. These rules increase the importance of certified recyclable and compostable designs. They also raise compliance, testing, and documentation costs for converters that rely on multi-material structures.
Other drivers and restraints analyzed in the detailed report include:
- E-Commerce and Quick-Commerce Fulfillment Demand
- Conversion From Rigid to Flexible Single-Use Formats
- Volatility in Petrochemical Resin Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bottles and Containers held 36.14% of 2025 revenue, supported by beverage, pharmaceutical, and personal care applications that require rigidity and product visibility. PET and PP bottles remain important in organized retail, particularly for branded products that require tamper-evident packaging and clear presentation. The share of the South America Single-use Plastic Packaging Market held by these formats reflects their fit with high-volume consumer products. This makes rigid bottles an important source of stable demand in the South America Single-use Plastic Packaging Market. Bags and Pouches are projected to grow at a 4.83% CAGR through 2031. Their growth reflects demand for lightweight packs used for condiments, dairy products, and dry food ingredients.
Trays, Cups, and Lids serve the foodservice and restaurant delivery sectors, where volume follows prepared-meal orders. Thermoforming improvements can reduce tray gauge while retaining the required strength for handling. Clamshells remain useful for fresh produce and bakery items because they allow product visibility. Films and Wraps support industrial stretch-film, agricultural mulch, and food heat-seal applications. Paper alternatives may limit growth in selected secondary-packaging uses. Constantia Flexibles launched a mono-material PE zipper pouch in Chile that was designed for LDPE collection systems.
Polyethylene accounted for 35.05% of material revenue in 2025 because it is used in films, bags, and bottles. Its broad use and cost profile sustain demand in the South America Single-use Plastic Packaging Market. It also provides converters with a widely available resin base for various end uses in the South America Single-use Plastic Packaging Market. PP is widely used for closures, microwave-safe trays, and heat-resistant foodservice containers. PET remains important for clear bottles and food trays. PET spot prices reached USD 1.06 per kilogram in 2025, while recycled PET was priced at USD 1.12 per kilogram.
Polystyrene and expanded polystyrene face lower market access as restrictions take effect in Chile and Brazilian municipalities. This supports demand for PP and PET alternatives in several foodservice uses. Polylactic Acid is projected to record a 4.62% CAGR through 2031, the fastest rate among the listed materials. Brazil's sugarcane-based ethanol supply chain supports the development of bio-based materials. Braskem presented bio-based and circular polyolefin grades for food-contact, healthcare, and hygiene uses in 2026. Brazil also reduces the import duty on PLA used in food-contact applications, thereby supporting adoption by certified converters.
Complete Report Scope:
- By Product Type
- Bottles and Containers
- Bags and Pouches
- Trays, Cups, and Lids
- Clamshells
- Films and Wraps
- Other Product Types
- By Material Type
- Polyethylene
- Polypropylene
- Polyethylene Terephthalate
- Polystyrene and Expanded Polystyrene
- Polylactic Acid
- Other Material Types
- By Packaging Format
- Rigid Packaging
- Flexible Packaging
- Semi-Rigid Packaging
- By Application
- Food Packaging
- Beverage Packaging
- Personal Care Packaging
- Pharmaceutical Packaging
- Household and Institutional Packaging
- Industrial and Agricultural Packaging
- By End User
- Foodservice and Quick-Service Restaurants
- Retail and Supermarkets
- E-Commerce and Delivery Platforms
- Consumer Goods Manufacturers
- Healthcare and Pharmaceutical Manufacturers
- Personal Care and Cosmetics Manufacturers
- By Geography
- Brazil
- Argentina
- Colombia
- Chile
- Rest of South America
List of Companies Covered in this Report:
- Amcor plc
- Berry Global Group, Inc.
- Sealed Air Corporation
- Mondi plc
- Sonoco Products Company
- Huhtamaki Oyj
- ProAmpac Holdings Inc.
- Constantia Flexibles Group GmbH
- Coveris Management GmbH
- Transcontinental Inc.
- Winpak Ltd.
- ALPLA Werke Alwin Lehner GmbH & Co KG
- Plastipak Holdings, Inc.
- Valgroup Participacoes S.A.
- Logoplaste Group
- AptarGroup, Inc.
- CCL Industries Inc.
- Gerresheimer AG
- Graham Packaging Company, L.P.
- Comar, LLC
- ZARAPLAST S.A.
- Petropack S.A.
- EMUSA
- Megapack
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Food Delivery and Quick-Service Restaurants
- 4.2.2 Growth of Packaged Food and Beverage Consumption
- 4.2.3 E-Commerce and Quick-Commerce Fulfillment Demand
- 4.2.4 Conversion from Rigid to Flexible Single-Use Formats
- 4.2.5 Expansion of Recyclable Mono-Material Packaging
- 4.2.6 Regional Growth of Food, Agricultural, and Export Supply Chains
- 4.3 Market Restraints
- 4.3.1 Single-Use Plastic Restrictions and Extended Producer Responsibility Costs
- 4.3.2 Volatility in Petrochemical Resin Prices
- 4.3.3 Limited Food-Grade Recycled Resin Availability
- 4.3.4 Fragmented Collection Systems for Multilayer Packaging
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Supply-Chain Analysis
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Bottles and Containers
- 5.1.2 Bags and Pouches
- 5.1.3 Trays, Cups, and Lids
- 5.1.4 Clamshells
- 5.1.5 Films and Wraps
- 5.1.6 Other Product Types
- 5.2 By Material Type
- 5.2.1 Polyethylene
- 5.2.2 Polypropylene
- 5.2.3 Polyethylene Terephthalate
- 5.2.4 Polystyrene and Expanded Polystyrene
- 5.2.5 Polylactic Acid
- 5.2.6 Other Material Types
- 5.3 By Packaging Format
- 5.3.1 Rigid Packaging
- 5.3.2 Flexible Packaging
- 5.3.3 Semi-Rigid Packaging
- 5.4 By Application
- 5.4.1 Food Packaging
- 5.4.2 Beverage Packaging
- 5.4.3 Personal Care Packaging
- 5.4.4 Pharmaceutical Packaging
- 5.4.5 Household and Institutional Packaging
- 5.4.6 Industrial and Agricultural Packaging
- 5.5 By End User
- 5.5.1 Foodservice and Quick-Service Restaurants
- 5.5.2 Retail and Supermarkets
- 5.5.3 E-Commerce and Delivery Platforms
- 5.5.4 Consumer Goods Manufacturers
- 5.5.5 Healthcare and Pharmaceutical Manufacturers
- 5.5.6 Personal Care and Cosmetics Manufacturers
- 5.6 By Geography
- 5.6.1 Brazil
- 5.6.2 Argentina
- 5.6.3 Colombia
- 5.6.4 Chile
- 5.6.5 Rest of South America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Berry Global Group, Inc.
- 6.4.3 Sealed Air Corporation
- 6.4.4 Mondi plc
- 6.4.5 Sonoco Products Company
- 6.4.6 Huhtamaki Oyj
- 6.4.7 ProAmpac Holdings Inc.
- 6.4.8 Constantia Flexibles Group GmbH
- 6.4.9 Coveris Management GmbH
- 6.4.10 Transcontinental Inc.
- 6.4.11 Winpak Ltd.
- 6.4.12 ALPLA Werke Alwin Lehner GmbH & Co KG
- 6.4.13 Plastipak Holdings, Inc.
- 6.4.14 Valgroup Participacoes S.A.
- 6.4.15 Logoplaste Group
- 6.4.16 AptarGroup, Inc.
- 6.4.17 CCL Industries Inc.
- 6.4.18 Gerresheimer AG
- 6.4.19 Graham Packaging Company, L.P.
- 6.4.20 Comar, LLC
- 6.4.21 ZARAPLAST S.A.
- 6.4.22 Petropack S.A.
- 6.4.23 EMUSA
- 6.4.24 Megapack
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


