

|
시장보고서
상품코드
2154820
아시아태평양의 식품용 이산화탄소 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Asia-Pacific Food Grade Carbon Dioxide - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
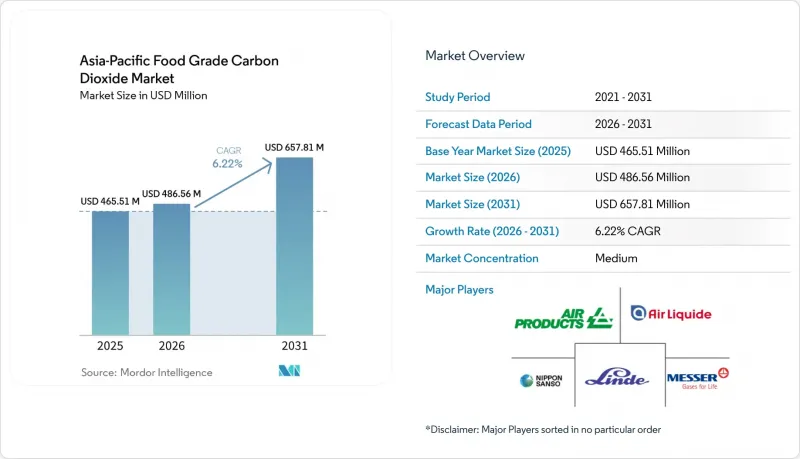
에 따르면 아시아태평양의 식품용 이산화탄소 시장 규모는 2025년 4억 6,551만 달러에서 2026년에는 4억 8,656만 달러로 확대되어, 2026년부터 2031년까지 CAGR 6.22%를 기록하며 2031년에는 6억 5,781만 달러에 달할 것으로 예측됩니다.
아시아태평양 식품용 이산화탄소 시장의 동향 및 인사이트
탄산음료 소비 확대
탄산음료는 해당 지역 전체에서 식품용 이산화탄소 수요의 주요 원천으로 자리 잡고 있습니다. 중국의 경우 2026년 6월, 주류, 음료, 정제차의 생산량이 전년 동월 대비 6.1% 증가한 것으로 보고되어, 대규모 음료 생산 기반에서 제조 활동이 지속되고 있음을 보여줍니다. 아시아태평양의 식품용 이산화탄소 시장은 개발 중인 도시 지역에서 음료 공장이 병입 및 탄산 주입 능력을 확충함에 따라 혜택을 볼 것입니다. 스파클링 워터, 향이 첨가된 탄산음료 및 무설탕 제품에는 신뢰할 수 있는 탄산 주입 제어가 요구됩니다. 이러한 요건으로 인해 일관된 순도와 확실한 대량 공급이 가능한 공급업체가 유리합니다. 또한 대규모 음료 제조업체의 경우, 비정기적인 단기 구매보다 장기 공급 계약의 중요성이 커지고 있습니다. 이와 같은 운영 요건으로 인해 현지 저장, 정기적인 탱커 배송, 그리고 공급업체의 품질 관련 문서 관리가 중시되고 있습니다.
식품 가공 및 보존 분야의 확대
식품 가공 분야에서는 음료 제조 외에도 이산화탄소의 활용 범위가 확대되고 있습니다. 인도 식품가공산업부는 2025년부터 2047년까지, 특히 육류 및 유제품 취급 분야에서 콜드체인 인프라에 대한 투자가 대폭 필요할 것이라고 지적하고 있습니다. 예냉, 터널식 냉동 및 온도 관리된 보관에는 액체 이산화탄소나 드라이아이스가 필요할 수 있습니다. 따라서 아시아태평양의 식품용 이산화탄소 시장은 냉장 식품 및 포장 식품으로의 전환에 힘입어 성장하고 있습니다. 이러한 수요는 가공업체들이 유통 거리나 유통기한을 연장하고 있는 지역에서 가장 크게 증가하고 있습니다. 가스 공급에 더해 저장 및 취급 지원을 결합한 서비스를 제공하는 공급업체는 이러한 용도에 대응하는 데 유리한 입장에 있습니다. 가공업체들이 지역 내 판매에서 일관된 온도 관리가 필요한 더 긴 유통 경로로 전환함에 따라 공급업체의 역할은 더욱 중요해질 것입니다. 이는 또한 가스 수요를 냉장 창고, 운송 및 식품 취급 장비에 대한 투자와 연계시키는 결과를 가져옵니다.
식품용 CO₂ 공급에 있어 지역 간 불균형
식품용 이산화탄소 공급은 반드시 식품 가공 수요가 있는 지역과 일치하는 것은 아닙니다. 대규모 회수 거점은 인도, 중국, 태국의 암모니아 및 에탄올 시설 주변에 집중되어 있습니다. 인도네시아, 말레이시아, 베트남, 및 인도 북동부에서는 인근의 정제, 저장, 유통 능력이 제한적인 경우가 있습니다. 따라서 아시아태평양의 식품용 이산화탄소 시장은 연안 지역 가공업체와 내륙 지역 가공업체에 따라 서로 다른 양상을 보일 가능성이 있습니다. 액체 이산화탄소 터미널 근처에 위치한 공장은 장기 공급 계약을 체결할 수 있습니다. 이러한 공급망에서 멀리 떨어진 곳에 위치한 가공업체는 음료 수요가 정점에 달할 때 계절적인 공급 부족 위험이 높아집니다. 또한, 회수 거점과 고객 간의 거리가 멀면 배송 비용이 증가하여 소규모 가공업체의 유연성이 저하될 수 있습니다.
부문 분석
2025년, 암모니아 플랜트에서의 회수는 지역 공급량의 35.14%를 차지했습니다. 인도, 중국, 베트남의 비료 복합 시설에서는 식품 용도로 회수 및 정제 가능한 고농도 이산화탄소 스트림이 생성되고 있습니다. 이 공급 경로는 기존 암모니아 및 요소 생산 규모의 혜택을 받고 있습니다. 반면, 비료 생산량, 천연가스 비용, 또는 플랜트 유지보수 일정의 변동에 따라 식품용 가스 공급이 영향을 받을 가능성도 있습니다. 수소 제조, 천연가스 처리 및 기타 산업 원천은 보다 지역 밀착형 공급원으로 기능하고 있습니다. 이러한 대체 수단은 대개 전속 공급 계약이나 장기 상업 계약을 통해 하나의 대규모 음료·식품·육류 가공업체를 지원하고 있습니다. 그 기여도는 현지 원료의 가용성, 정제 능력, 그리고 고객의 식품 등급 품질 요건에 따라 달라집니다.
아시아태평양의 식품 등급 이산화탄소 시장에서, 에탄올을 통한 회수는 2031년까지 연평균 성장률(CAGR) 7.37%로 확대될 것으로 예측됩니다. 발효 공정에서는 고농도의 이산화탄소 스트림이 생성되며, 이를 정제함으로써 식품 및 음료 용도로 활용할 수 있습니다. 인도의 에탄올 혼합 프로그램과 태국의 바이오연료 확대에 힘입어 해당 지역 전체의 증류 능력이 강화되고 있습니다. 일일 100KL 규모의 에탄올 플랜트에서는 발효 배기가스에서 연간 13,000-15,000톤의 이산화탄소를 회수할 수 있습니다. 일본산소 태국과 타이 스페셜 가스는 2026년 ‘Green CO2’ 프로젝트를 시작하여, 차촌사오 주에 위치한 BBGI사의 에탄올 제조 공정에서 발생하는 이산화탄소를 정제하여 식품, 음료 및 산업용으로 공급하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 공급망 분석
- 규제 전망
- Porter's Five Forces
제5장 시장 규모와 성장 예측
- 원료별
- 형태별
- 최종 이용 산업별
- 국가별
- 중국
- 일본
- 인도
- 한국
- 호주
- 뉴질랜드
- 인도네시아
- 말레이시아
- 베트남
- 기타 아시아태평양 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 순위 분석
- 기업 개요
- Linde plc
- Air Liquide S.A.
- Air Products and Chemicals, Inc.
- TAIYO NIPPON SANSO CORPORATION
- Messer SE & Co. KGaA
- Sicgil India Limited
- Ellenbarrie Industrial Gases Limited
- IFB Agro Industries Limited
- WKS Industrial Gas Pte Ltd.
- Southern Gas Limited
- Yingde Gases Group Company Limited
- Hangzhou Hangyang Co., Ltd.
- Sichuan Tianyi Science and Technology Co., Ltd.
- Shandong Shouguang Juneng Golden Corn Co., Ltd.
- Jiangsu Huachang Chemical Co., Ltd.
- Guangdong Huate Gas Co., Ltd.
- Zhejiang Juhua Co., Ltd.
- India Glycols Limited
- PT Samator Indo Gas Tbk
- Air Water, Inc.
제7장 시장 기회와 향후 전망
KSM 26.10.29According to Mordor Intelligence, the asia-pacific food grade carbon dioxide market size is expected to grow from USD 465.51 million in 2025 to USD 486.56 million in 2026 and is forecast to reach USD 657.81 million by 2031 at 6.22% CAGR over 2026-2031.
Asia-Pacific Food Grade Carbon Dioxide Market Trends and Insights
Growth in carbonated beverage consumption
Carbonated beverages remain the main source of food-grade carbon dioxide demand across the region. China reported a 6.1% year-on-year increase in production of liquor, beverages, and refined tea in June 2026, indicating continued manufacturing activity in a large beverage base. The Asia-Pacific food-grade carbon dioxide market benefits when beverage plants add bottling and carbonation capacity in developing urban centers. Sparkling water, flavored carbonated drinks, and sugar-free products require reliable carbonation control. That requirement favors suppliers that can deliver consistent purity and dependable bulk volumes. It also makes long-term supply arrangements more relevant for large beverage producers than occasional spot purchases. The same operating requirements place value on local storage, scheduled tanker deliveries, and supplier quality documentation.
Expansion of food processing and preservation
Food processing is widening the use of carbon dioxide beyond beverage manufacturing. India's Ministry of Food Processing Industries identified a substantial need for cold-chain infrastructure investment between 2025 and 2047, particularly for the handling of meat and dairy products. Pre-cooling, tunnel freezing, and temperature-controlled storage can require liquid carbon dioxide or dry ice. The Asia-Pacific food-grade carbon dioxide market therefore gains from the shift toward refrigerated and packaged food. This demand is strongest where processors are extending distribution distances and shelf life. Supply providers that pair gas delivery with storage and handling support are better placed to serve these applications. Their role becomes more important when processors move from local sales toward longer distribution routes that require consistent temperature management. This also links gas demand to investments in refrigerated warehouses, transport, and food handling equipment.
Regional imbalances in food-grade CO2 availability
Food-grade carbon dioxide supply does not always match the location of food-processing demand. Large recovery sites are concentrated around ammonia and ethanol facilities in India, China, and Thailand. Indonesia, Malaysia, Vietnam, and northeastern India can face limited nearby purification, storage, and distribution capacity. The Asia-Pacific food-grade carbon dioxide market can therefore operate differently for coastal processors and inland processors. Plants located near liquid carbon dioxide terminals can use longer-term supply arrangements. Processors farther from those networks face a greater risk of seasonal supply tightening during peak beverage demand. The distance between recovery sites and customers can also increase delivery costs and reduce the flexibility of smaller processors.
Other drivers and restraints analyzed in the detailed report include:
- Increasing adoption of modified atmosphere packaging (MAP)
- Rising demand for meat and poultry processing
- High investment requirements for storage and distribution infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ammonia-plant recovery held 35.14% of regional supply in 2025. Fertilizer complexes in India, China, and Vietnam generate concentrated carbon dioxide streams that can be recovered and purified for food applications. This route benefits from the scale of existing ammonia and urea production. It can also expose food-gas supply to changes in fertilizer output, natural gas costs, or plant maintenance schedules. Hydrogen production, natural gas processing, and other industrial sources serve more localized supply positions. These alternatives often support one large beverage, food, or meat processor through captive arrangements or long-term commercial contracts. Their contribution depends on local feedstock availability, purification capability, and the customer's food-grade quality requirements.
Ethanol recovery is projected to grow at a 7.37% CAGR through 2031 within the Asia-Pacific food-grade carbon dioxide market. Fermentation creates a high-concentration carbon dioxide stream that can be purified for food and beverage use. India's ethanol blending program and Thailand's biofuel expansion are increasing distillation capacity across the region. A 100-KLPD ethanol plant can recover 13,000 to 15,000 tonnes of carbon dioxide each year from fermentation exhaust. Nippon Sanso Thailand and Thai Special Gas launched Green CO2 Co., Ltd. in 2026 to purify carbon dioxide from BBGI's ethanol process in Chachoengsao Province for food, beverage, and industrial supply.
Complete Report Scope:
- By Source
- Ammonia
- Ethanol
- Hydrogen
- Natural Gas Processing
- Other Sources
- By Form
- Liquid
- Gas
- Solid/Dry Ice
- By End-use Industry
- Beverages
- Meat & Poultry
- Dairy & Frozen Foods
- Fruits & Vegetables
- Bakery & Confectionery
- Other Food Industries
- By Country
- China
- Japan
- India
- South Korea
- Australia
- New Zealand
- Indonesia
- Malaysia
- Vietnam
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- Linde plc
- Air Liquide S.A.
- Air Products and Chemicals, Inc.
- TAIYO NIPPON SANSO CORPORATION
- Messer SE & Co. KGaA
- Sicgil India Limited
- Ellenbarrie Industrial Gases Limited
- IFB Agro Industries Limited
- WKS Industrial Gas Pte Ltd.
- Southern Gas Limited
- Yingde Gases Group Company Limited
- Hangzhou Hangyang Co., Ltd.
- Sichuan Tianyi Science and Technology Co., Ltd.
- Shandong Shouguang Juneng Golden Corn Co., Ltd.
- Jiangsu Huachang Chemical Co., Ltd.
- Guangdong Huate Gas Co., Ltd.
- Zhejiang Juhua Co., Ltd.
- India Glycols Limited
- PT Samator Indo Gas Tbk
- Air Water, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in carbonated beverage consumption
- 4.2.2 Expansion of food processing and preservation
- 4.2.3 Increasing adoption of modified atmosphere packaging (MAP)
- 4.2.4 Rising demand for meat and poultry processing
- 4.2.5 Expansion of frozen and chilled food production
- 4.2.6 Growth in packaged dairy and frozen products
- 4.3 Market Restraints
- 4.3.1 Regional imbalances in food-grade CO2 availability
- 4.3.2 High investment requirements for storage and distribution infrastructure
- 4.3.3 Energy-price volatility affecting CO2 production economics
- 4.3.4 Stringent food-grade purity and certification requirements
- 4.4 Supply Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers/Consumers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Source
- 5.1.1 Ammonia
- 5.1.2 Ethanol
- 5.1.3 Hydrogen
- 5.1.4 Natural Gas Processing
- 5.1.5 Other Sources
- 5.2 By Form
- 5.2.1 Liquid
- 5.2.2 Gas
- 5.2.3 Solid/Dry Ice
- 5.3 By End-use Industry
- 5.3.1 Beverages
- 5.3.2 Meat & Poultry
- 5.3.3 Dairy & Frozen Foods
- 5.3.4 Fruits & Vegetables
- 5.3.5 Bakery & Confectionery
- 5.3.6 Other Food Industries
- 5.4 By Country
- 5.4.1 China
- 5.4.2 Japan
- 5.4.3 India
- 5.4.4 South Korea
- 5.4.5 Australia
- 5.4.6 New Zealand
- 5.4.7 Indonesia
- 5.4.8 Malaysia
- 5.4.9 Vietnam
- 5.4.10 Rest of Asia-Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Ranking Analysis
- 6.4 Company Profiles (includes Company Highlights, Core Segments, Financials (if available), Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Linde plc
- 6.4.2 Air Liquide S.A.
- 6.4.3 Air Products and Chemicals, Inc.
- 6.4.4 TAIYO NIPPON SANSO CORPORATION
- 6.4.5 Messer SE & Co. KGaA
- 6.4.6 Sicgil India Limited
- 6.4.7 Ellenbarrie Industrial Gases Limited
- 6.4.8 IFB Agro Industries Limited
- 6.4.9 WKS Industrial Gas Pte Ltd.
- 6.4.10 Southern Gas Limited
- 6.4.11 Yingde Gases Group Company Limited
- 6.4.12 Hangzhou Hangyang Co., Ltd.
- 6.4.13 Sichuan Tianyi Science and Technology Co., Ltd.
- 6.4.14 Shandong Shouguang Juneng Golden Corn Co., Ltd.
- 6.4.15 Jiangsu Huachang Chemical Co., Ltd.
- 6.4.16 Guangdong Huate Gas Co., Ltd.
- 6.4.17 Zhejiang Juhua Co., Ltd.
- 6.4.18 India Glycols Limited
- 6.4.19 PT Samator Indo Gas Tbk
- 6.4.20 Air Water, Inc.


