

|
시장보고서
상품코드
2155594
복합재료 영상 검사 시스템 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Composite Material Imaging Inspection Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
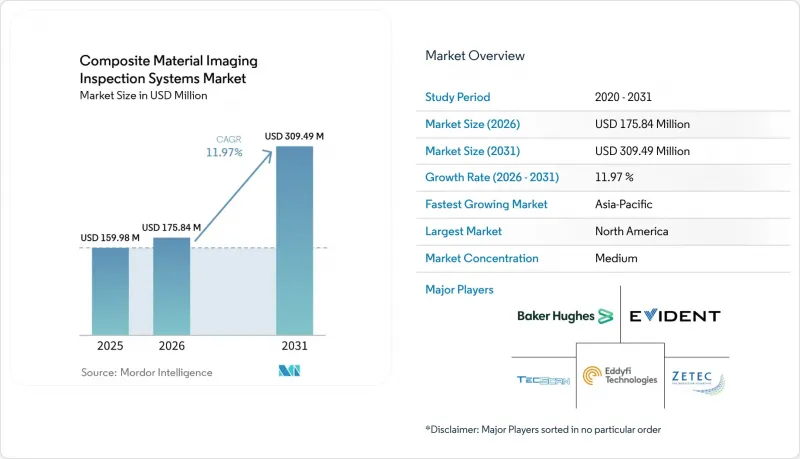
에 따르면 복합재료 영상 검사 시스템 시장 규모는 2025년 1억 5,998만 달러에서 2026년에는 1억 7,584만 달러로 확대되어, 2026년부터 2031년까지 CAGR 11.97%를 기록하며 2031년에는 3억 949만 달러에 달할 것으로 예측됩니다.
세계 복합재료 영상 검사 시스템 시장의 동향 및 인사이트
안전상 중요한 구조물에서 복합재료의 사용 비율 증가
복합재료는 제한적인 성능적 특징이라기보다는 인증된 항공기 구조물의 설계 기준이 되어가고 있습니다. 복합재료의 사용 비율이 높아짐에 따라 각 생산 주기에서 체적 검사가 필요한 영역도 확대되고 있습니다. 2026년 ECNDT 논문에서는 항공우주 엔진의 고온부에서 사용되는 실리콘 카바이드 세라믹 매트릭스 복합재료의 경우, 육안 검사만으로는 일관된 기록을 얻을 수 없기 때문에 결함 판정의 추적 가능성이 요구된다고 지적하고 있습니다. 새로운 플라이의 배향, 샌드위치 코어, 그리고 금속과 복합재료의 하이브리드 접합부 또한 검사의 복잡성을 가중시키고 있습니다. 따라서 복합재료 영상 검사 시스템 시장에서는 다양한 적층체의 형상에 걸쳐 더욱 미세한 표면 하부 특성을 평가할 수 있는 초음파와 열화상 기술을 통합한 플랫폼이 선호되고 있습니다. 이러한 수요는 개별 항공기 프로그램에서 일시적인 생산 감속이 발생하더라도 여전히 중요한 요소로 남아 있을 것입니다.
항공우주 생산 및 MRO 활동의 확대
2024년과 2025년에도 항공기 인도 일정은 활발하게 진행되고 있으며, 이는 OEM(Original Equipment Manufacturer) 시설 및 정비·수리·점검(MRO) 거점의 검사 주기를 뒷받침하고 있습니다. 대규모 정비의 경우, 정해진 검사 주기에 따라 복합재로 제작된 주요 구조물 및 2차 구조물에 대한 종합적인 비파괴 검사가 요구됩니다. 또한, 각 제조사는 성능 요건을 충족하기 위해 더욱 복잡한 플라이 배열과 샌드위치 코어 설계를 채택하고 있습니다. 이러한 설계에는 이전 라미네이트 세대를 위해 인증된 시스템보다 더 깊은 침투 깊이와 더 높은 해상도가 요구됩니다. 그 결과, 공정 중 결과를 문서화하는 데 대한 관심이 높아지면서, 운영자가 해석하는 C-스캔 출력물이 아닌 디지털 검사 기록을 생성하는 시스템에 대한 수요가 증가하고 있습니다. 항공기 1대당 검사 범위는 단순히 인도된 항공기 대수를 세는 데 그치지 않기 때문에 복합재 이미징 검사 시스템 시장은 그 혜택을 누리고 있습니다.
자동화 이미징 셀의 높은 설비 투자 비용
완전 자동화된 복합재 검사 갠트리나 로봇 스캔 시스템에는 수백만 달러 규모의 설비 투자가 필요합니다. 이는 생산량이 적은 Tier 2 및 Tier 3 공급업체에게 특히 큰 장벽이 됩니다. 총 비용은 하드웨어에만 그치지 않고, 적응형 스캔 소프트웨어, 교정용 아티팩트 라이브러리, 환경 제어, 시설 개조까지 포함됩니다. 또한 부품의 형상이 각기 다른 경우 맞춤형 고정 장치가 필요할 수 있어, 다양한 부품 포트폴리오를 보유한 공급업체에게는 실질적인 비용 증가로 이어집니다. 이러한 경제적 요인으로 인해 아시아태평양과 중동에서는 수동 검사에서 자동화 플랫폼으로의 전환이 지연되고 있습니다. 복합재료 이미징 검사 시스템 시장에서는 모듈식 또는 리스 기반의 구매 모델을 제공하는 공급업체에게 더 쉽게 진입할 수 있는 기회가 생길 가능성이 있습니다.
부문 분석
2025년, 초음파 이미징은 복합재료 이미징 검사 시스템 시장 점유율의 43.62%를 차지하며, CFRP 및 GFRP 적층판의 층간 박리, 기공, 충격 손상을 식별하기 위한 주요 기법으로 자리매김했습니다. 풀 매트릭스 캡처 및 토탈 포커싱 기법을 활용한 위상 배열 초음파 검사는 복합재료의 적합성 평가에 널리 활용되고 있습니다. 2026년 ECNDT 논문에서는 가늘고 긴 복합재료 구조 부재에 대한 완전 자동화된 싱글 패스형 로봇 초음파 검사가 소개되었습니다. 이 기법을 통해 주익 외판, 스트링거 및 로터 블레이드의 스퍼에 대한 스캔 시간을 단축할 수 있습니다. 열화상 진단은 비접촉식 검사가 유용한 대형 패널의 박리나 코어의 찌그러짐 감지에 대응합니다. X선 촬영 및 컴퓨터 단층촬영(CT)은 비행에 필수적인 패스너 구멍, 접합부, 그리고 세라믹 매트릭스 복합재로 제작된 핫 섹션 부품 내의 체적 공극 매핑에 사용되고 있습니다.
광학 및 레이저 이미징 시장은 2031년까지 연평균 성장률(CAGR) 14.83%로 확대될 것으로 예측됩니다. ISO 8203-4:2025는 섬유 강화 폴리머 복합재료의 레이저 시아로그래피에 관한 국제적 방법을 규정하고 있습니다. 이 방법은 동체 베이 및 나셀 페어링과 같은 곡면 패널에 대해 한쪽 면에서 접근하여 비접촉식이며 광범위한 검사를 가능하게 합니다. 2026년에 발표된 조사에 따르면, 필터링된 위상 맵 분석을 통해 레이저 시아로그래피에서 CFRP의 충격 손상 탐지 정확도가 향상된 것으로 밝혀졌습니다. 와전류 어레이 및 멀티센서 데이터 융합 기술은 금속과 복합재료의 접착 계면에 대한 전문적인 검사에서 계속해서 활용되고 있습니다. 이러한 표준, 신호 분석 및 블레이드 검사 수요가 맞물리면서, 복합재료 이미징 검사 시스템 업계에서 광학 기법의 보다 광범위한 활용이 촉진되고 있습니다.
2025년 기준, 복합재료 이미징 검사 시스템 시장 중 휴대용 및 핸드헬드형 시스템이 36.84%를 차지했습니다. 이러한 시스템은 고정식 갠트리로는 부품에 접근할 수 없는 유지보수 현장에서 중요한 역할을 수행하고 있습니다. 또한, 휴대용 위상 배열 검출기 및 핸드헬드 시아로그래피 카메라는 풍력발전, 선박, 토목 인프라 분야의 현장 작업도 지원하고 있습니다. 벤치탑형 및 실험실용 시스템은 재료 연구나 손상 특성 평가 작업에 활용되고 있습니다. 컴팩트한 스퀴터 모드 초음파 플랫폼은 바닥 면적이 제한된 시설에서도 고정밀 시험을 가능하게 합니다. 자동화 시스템 및 고정식 시스템은 주익 외판, 동체 패널, 로터 블레이드 등의 부품을 제조하는 전용 생산 셀을 뒷받침하고 있습니다.
인라인 검사 시스템은 2031년까지 연평균 성장률(CAGR) 15.62%로 확대될 것으로 예측됩니다. 이러한 시스템은 자동 섬유 배치 라인이나 수지 전사 성형 라인 내에 직접 이미징 센서를 설치합니다. 이를 통해 제조사는 적층체의 경화가 완료되기 전에 적층 오류, 기공, 이물질 혼입을 식별할 수 있습니다. Adaptix Ltd., 크랜필드 대학교, 항공우주기술연구소의 공동 연구를 통해 복합재 프리폼 단계에서 확장 가능한 3D X선 검사를 위해 로봇 기술을 활용한 디지털 단층촬영 기술이 검증되었습니다. 조기 검사를 실시함으로써 경화 후의 수리나 재검사의 필요성을 줄일 수 있습니다. 따라서 복합재 영상 검사 시스템 업계에서는 초기 투자 비용뿐만 아니라 수명주기 비용의 관점에서 인라인 시스템을 평가하고 있습니다.
지역별 분석
2025년 지역별 수요 중 북미가 35.18%를 차지했습니다. 이 지역은 미국의 주요 항공우주 계약업체 집적, 국방부의 유지보수 프로그램, 그리고 대규모 민간 정비·수리·점검(MRO) 네트워크의 혜택을 받고 있습니다. 캐나다는 구조용 복합재 프로그램 및 엔진 시험 센터를 포함한 Tier 1(Tier 1) 항공우주 공급망을 통해 기여하고 있습니다. 멕시코는 북부 주에 복합재 제조 회랑을 구축하고 있으며, 이를 통해 생산 시설 인근에서 휴대용 및 반자동 시스템에 대한 수요가 뒷받침되고 있습니다.
유럽은 복합재 영상 검사 시스템 시장에서 2위 규모를 자랑하는 지역으로, 독일, 프랑스, 영국, 스페인의 에어버스 산업 시스템이 그 핵심을 이루고 있습니다. 에어버스는 함부르크에서 구조 부품을 제조하고 있으며, 프리미엄 에어로테크(Premium Aerotech)의 사업은 독일 내 초음파 영상 검사 장비 조달을 뒷받침하고 있습니다. 롤스로이스(Rolls-Royce)의 팬 시스템과 GKN 에어로스페이스(GKN Aerospace)의 주익 구조 등을 포함한 영국의 복합재료 공급망은 휴대용 및 반자동 플랫폼에 대한 수요를 뒷받침하고 있습니다. 중동에서는 사우디아라비아와 UAE에서 국내 항공우주 정비 인프라에 대한 투자가 진행되고 있어, 와이드바디 기체용 휴대용 시스템에 대한 수요가 발생하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 14.67%로 확대될 것으로 예측됩니다. 중국, 인도, 일본, 한국에서는 국내 복합재 제조 및 항공우주 프로그램이 확대되고 있습니다. 중국의 COMAC 프로그램 및 관련 부품 생산으로 인해 AS9100 Rev D 요건을 충족하는 추적성 기능을 갖춘 인프라에 대한 수요가 증가하고 있습니다. 인도에서는 군사용 복합재 프로그램, 지속적으로 성장하는 민간 정비 부문, 그리고 활성화되고 있는 풍력발전 사업이 결합되어 있습니다. 또한, 보잉 787의 복합재 동체 섹션과 관련된 일본의 노력과 한국의 방위 프로그램도 수요를 더욱 끌어올리고 있습니다. 아프리카는 남아프리카공화국의 항공우주 정비를 중심으로 한 초기 단계의 지역이지만, 풍력발전 설비 설치로 인해 예측 기간 후반에는 수요가 확대될 가능성이 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 업계 밸류체인 분석
- 거시경제 요인이 시장에 미치는 영향
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 검사 기술별
- 시스템 구성별
- 용도별
- 최종사용자별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 기타 유럽 국가
- 아시아태평양
- 중국
- 일본
- 인도
- 한국
- ASEAN
- 기타 아시아태평양 국가
- 중동
- 사우디아라비아
- 아랍에미리트
- 튀르키예
- 기타 중동 국가
- 아프리카
- 남아프리카공화국
- 나이지리아
- 기타 아프리카 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Baker Hughes Company
- Evident Corporation
- Eddyfi Technologies Inc.
- Zetec, Inc.
- Sonatest Ltd.
- TecScan Systems Inc.
- Dolphitech AS
- Dantec Dynamics A/S
- Tecnatom, S.A.
- Testia SAS
- AT Sensors Oy
- Technology Design Ltd.
- Phoenix Inspection Systems Limited
- The Phased Array Company Limited
- SINTEG Systems AB
- NextNDT, Inc.
- Arora Technologies Pvt. Ltd.
- ScanMaster Systems Ltd.
- OKOndt GROUP
- Karl Deutsch Pruf-und Messgeratebau GmbH+Co. KG
- Foerster Instruments, Inc.
- Sonotron NDT Ltd.
- Modsonic Instruments Manufacturing Pvt. Ltd.
- Helling GmbH
제7장 시장 기회와 향후 전망
KSMAccording to Mordor Intelligence, the composite material imaging inspection systems market size is expected to grow from USD 159.98 million in 2025 to USD 175.84 million in 2026 and is forecast to reach USD 309.49 million by 2031 at 11.97% CAGR over 2026-2031.
Global Composite Material Imaging Inspection Systems Market Trends and Insights
Increasing Composite Content in Safety-Critical Structures
Composite materials are becoming a design baseline in certified aircraft structures rather than a limited performance feature. More composite content increases the area that requires volumetric inspection during each production cycle. A 2026 ECNDT paper noted that silicon carbide ceramic matrix composites in aerospace engine hot sections require traceable defect decisions because visual review does not provide consistent documentation. New ply orientations, sandwich cores, and hybrid metal-composite joints also increase inspection complexity. The composite material imaging inspection systems market, therefore, favors integrated ultrasonic and thermographic platforms that can assess finer subsurface features across variable laminate geometries. This demand remains relevant even when an individual aircraft program experiences a temporary production slowdown.
Expansion of Aerospace Production and MRO Activity
Aircraft delivery programs remained active in 2024 and 2025, supporting inspection cycles at original equipment manufacturer facilities and maintenance, repair, and overhaul sites. Heavy maintenance requires comprehensive nondestructive testing of composite primary and secondary structures at prescribed inspection intervals. Manufacturers are also using more complex ply arrangements and sandwich-core designs to meet performance requirements. These designs require deeper penetration and finer resolution than systems qualified for earlier laminate generations. The resulting focus on documented in-process results is increasing demand for systems that produce digital inspection records rather than operator-interpreted C-scan printouts. The composite material imaging inspection systems market benefits because the inspection scope per aircraft extends beyond a simple count of delivered aircraft.
High Capital Cost of Automated Imaging Cells
Fully automated composite inspection gantries and robotic scanning cells require multimillion-dollar capital commitments. This is particularly restrictive for tier 2 and tier 3 suppliers with lower production volumes. Total cost extends beyond hardware to adaptive scan-path software, calibration artifact libraries, environmental controls, and facility changes. Each distinct part geometry can also require custom fixtures, which raises the effective cost for suppliers with diverse part portfolios. These economics slow the shift from manual inspection to automated platforms in Asia-Pacific and the Middle East. The composite material imaging inspection systems market may offer more accessible opportunities for suppliers that provide modular or lease-based purchasing models.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Automated Phased-Array and Matrix-Array Ultrasonics
- Regulatory Demand for Traceable Composite Inspection
- Shortage of Qualified Composite NDT Personnel
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ultrasonic imaging held 43.62% of the composite material imaging inspection systems market share in 2025 and remained the main method for identifying delamination, porosity, and impact damage in CFRP and GFRP laminates. Phased-array ultrasonic testing with full-matrix capture and total focusing method processing is widely used for composite qualification. A 2026 ECNDT paper demonstrated fully automated single-pass robotic ultrasonic inspection for elongated composite structural members. The approach can reduce scan time for wing skins, stringers, and rotor-blade spars. Thermographic imaging addresses large-panel disbond and core-crush detection where noncontact coverage is useful. Radiographic imaging and computed tomography are used for volumetric void mapping in flight-critical fastener holes, splice regions, and ceramic matrix composite hot-section components.
Optical and laser imaging is projected to expand at a CAGR of 14.83% through 2031. ISO 8203-4:2025 sets out an international method for laser shearography of fiber-reinforced polymer composites. The method offers noncontact, large-area coverage with single-sided access for curved panels such as fuselage bays and nacelle fairings. Research published in 2026 found that filtered phase-map analysis improved detection of CFRP impact damage in laser shearography. Eddy current arrays and multisensor data fusion continue to serve specialized inspections of bonded metal-composite interfaces. This combination of standards, signal analysis, and blade inspection demand supports wider use of optical methods in the composite material imaging inspection systems industry.
Portable and handheld systems held 36.84% of the composite material imaging inspection systems market in 2025. They are important in maintenance settings where fixed gantries cannot access the part. Portable phased-array detectors and handheld shearography cameras also support field work in wind energy, marine, and civil infrastructure settings. Benchtop and laboratory systems serve material research and damage characterization work. Compact squirter-mode ultrasonic platforms support high-precision testing in facilities with limited floor space. Automated and fixed systems support dedicated production cells for parts such as wing skins, fuselage panels, and rotor blades.
In-line inspection systems are projected to expand at a CAGR of 15.62% through 2031. These systems place imaging sensors directly within automated fiber placement and resin transfer molding lines. Manufacturers can then identify layup errors, porosity, and foreign-object inclusions before laminate consolidation is complete. A collaboration involving Adaptix Ltd., Cranfield University, and the Aerospace Technology Institute demonstrated digital tomography with robotics for scalable 3D X-ray inspection at the composite preform stage. Earlier inspection can reduce post-cure rework and repeat inspection requirements. The composite material imaging inspection systems industry is thus evaluating in-line systems on lifecycle costs rather than on the initial capital cost alone.
Complete Report Scope:
- By Inspection Technology
- Ultrasonic Imaging
- Thermographic Imaging
- Optical and Laser Imaging
- Radiographic Imaging
- Other Imaging Technologies
- By System Configuration
- Portable and Handheld Systems
- Benchtop and Laboratory Systems
- Automated and Fixed Inspection Systems
- In-Line Inspection Systems
- By Application
- Manufacturing and Production Quality Inspection
- In-Service Inspection and Maintenance
- Repair and Refurbishment Verification
- Research, Development, and Material Characterization
- Other Applications
- By End-User
- Aerospace, Defense, and Space
- Automotive and Transportation
- Energy and Power
- Industrial Manufacturing
- Marine and Infrastructure
- Research and Testing
- Other End-Users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of the Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 35.18% of 2025 regional demand. The region benefits from the concentration of U.S. aerospace prime contractors, Department of Defense sustainment programs, and a substantial commercial maintenance, repair, and overhaul network. Canada contributes through its tier 1 aerospace supply chain, including structural composite programs and engine testing centers. Mexico is developing a composite manufacturing corridor in its northern states, which supports demand for portable and semi-automated systems near production facilities.
Europe was the second-largest regional area within the composite material imaging inspection systems market, anchored by the Airbus industrial system in Germany, France, the United Kingdom, and Spain. Airbus structures work in Hamburg, and Premium Aerotec operations support ultrasonic imaging procurement in Germany. The United Kingdom composite supply chain, including Rolls-Royce fan systems and GKN Aerospace wing structures, supports demand for portable and semi-automated platforms. The Middle East is investing in domestic aerospace maintenance infrastructure in Saudi Arabia and the UAE, creating openings for portable systems serving wide-body fleets.
Asia-Pacific is projected to expand at a CAGR of 14.67% through 2031. China, India, Japan, and South Korea are expanding domestic composite manufacturing and aerospace programs. China's COMAC programs and related component production are increasing demand for traceability-capable infrastructure that meets AS9100 Rev D requirements. India combines military composite programs, a growing commercial maintenance sector, and rising wind-energy activity. Japan's work on Boeing 787 composite fuselage sections and South Korea's defense programs add further demand. Africa remains an early-stage area centered on South African aerospace maintenance, while wind-energy installations could strengthen demand later in the forecast period.
- Baker Hughes Company
- Evident Corporation
- Eddyfi Technologies Inc.
- Zetec, Inc.
- Sonatest Ltd.
- TecScan Systems Inc.
- Dolphitech AS
- Dantec Dynamics A/S
- Tecnatom, S.A.
- Testia SAS
- AT Sensors Oy
- Technology Design Ltd.
- Phoenix Inspection Systems Limited
- The Phased Array Company Limited
- SINTEG Systems AB
- NextNDT, Inc.
- Arora Technologies Pvt. Ltd.
- ScanMaster Systems Ltd.
- OKOndt GROUP
- Karl Deutsch Pruf- und Messgeratebau GmbH + Co. KG
- Foerster Instruments, Inc.
- Sonotron NDT Ltd.
- Modsonic Instruments Manufacturing Pvt. Ltd.
- Helling GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Composite Content in Safety-Critical Structures
- 4.2.2 Expansion of Aerospace Production and MRO Activity
- 4.2.3 Adoption of Automated Phased-Array and Matrix-Array Ultrasonics
- 4.2.4 Regulatory Demand for Traceable Composite Inspection
- 4.2.5 Real-Time Stiffness Mapping and Defect Localization
- 4.2.6 Digital Twin Integration for Composite Quality Records
- 4.3 Market Restraints
- 4.3.1 High Capital Cost of Automated Imaging Cells
- 4.3.2 Complex Calibration for Thick and Curved Composite Structures
- 4.3.3 Shortage of Qualified Composite NDT Personnel
- 4.3.4 Limited Certification Pathways for AI-Assisted Inspection
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Inspection Technology
- 5.1.1 Ultrasonic Imaging
- 5.1.2 Thermographic Imaging
- 5.1.3 Optical and Laser Imaging
- 5.1.4 Radiographic Imaging
- 5.1.5 Other Imaging Technologies
- 5.2 By System Configuration
- 5.2.1 Portable and Handheld Systems
- 5.2.2 Benchtop and Laboratory Systems
- 5.2.3 Automated and Fixed Inspection Systems
- 5.2.4 In-Line Inspection Systems
- 5.3 By Application
- 5.3.1 Manufacturing and Production Quality Inspection
- 5.3.2 In-Service Inspection and Maintenance
- 5.3.3 Repair and Refurbishment Verification
- 5.3.4 Research, Development, and Material Characterization
- 5.3.5 Other Applications
- 5.4 By End-User
- 5.4.1 Aerospace, Defense, and Space
- 5.4.2 Automotive and Transportation
- 5.4.3 Energy and Power
- 5.4.4 Industrial Manufacturing
- 5.4.5 Marine and Infrastructure
- 5.4.6 Research and Testing
- 5.4.7 Other End-Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 ASEAN
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of the Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Baker Hughes Company
- 6.4.2 Evident Corporation
- 6.4.3 Eddyfi Technologies Inc.
- 6.4.4 Zetec, Inc.
- 6.4.5 Sonatest Ltd.
- 6.4.6 TecScan Systems Inc.
- 6.4.7 Dolphitech AS
- 6.4.8 Dantec Dynamics A/S
- 6.4.9 Tecnatom, S.A.
- 6.4.10 Testia SAS
- 6.4.11 AT Sensors Oy
- 6.4.12 Technology Design Ltd.
- 6.4.13 Phoenix Inspection Systems Limited
- 6.4.14 The Phased Array Company Limited
- 6.4.15 SINTEG Systems AB
- 6.4.16 NextNDT, Inc.
- 6.4.17 Arora Technologies Pvt. Ltd.
- 6.4.18 ScanMaster Systems Ltd.
- 6.4.19 OKOndt GROUP
- 6.4.20 Karl Deutsch Pruf- und Messgeratebau GmbH + Co. KG
- 6.4.21 Foerster Instruments, Inc.
- 6.4.22 Sonotron NDT Ltd.
- 6.4.23 Modsonic Instruments Manufacturing Pvt. Ltd.
- 6.4.24 Helling GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


