

|
시장보고서
상품코드
2156903
태국의 의약품 냉장 체인 공수 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Thailand Pharmaceutical Cold Chain Air Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
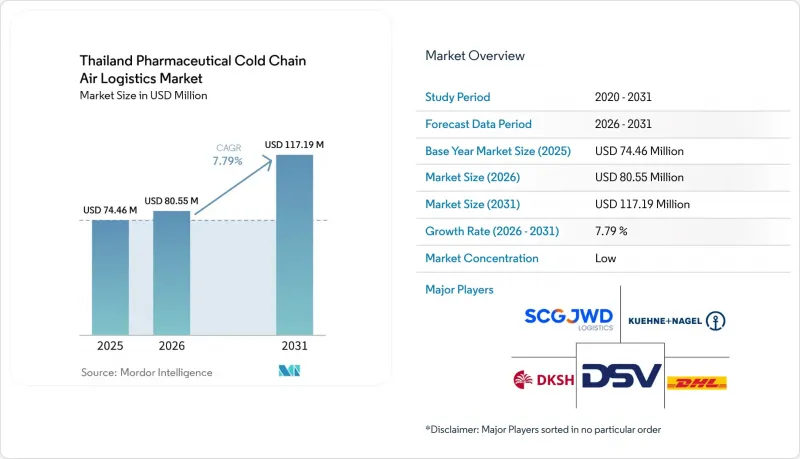
에 따르면 태국의 의약품 콜드체인 항공 물류 시장 규모는 2025년에 7,446만 달러로 평가되며, 2026년 8,055만 달러에서 2031년에는 1억 1,719만 달러에 달할 것으로 예측되고 있으며, 2026-2031년에 CAGR 7.79%를 기록할 전망입니다.
태국 의약품 콜드체인 항공 물류 시장의 동향 및 인사이트
바이오의약품, 백신 및 전문의약품의 성장
바이오의약품 및 전문의약품의 증가로 인해 태국 의약품 콜드체인 항공 물류 시장의 공급업체에 요구되는 기술적 요건이 높아지고 있습니다. 이러한 제품들은 제조업체에서 공항내 취급, 통관 절차, 그리고 임상 현장에 대한 최종 배송에 이르기까지 안정적인 조건이 요구됩니다. WHO 지침에 따르면 시간 및 온도에 민감한 의약품의 경우, 공급망 파트너 간의 인계 시점을 포함하여 제품의 품질을 보호하기 위한 관리된 보관 및 운송 체계가 필요합니다. 모노클로널 항체, 효소 대체요법, 백신 및 혈액 유래 제품은 항공 운송 중 엄격한 관리 하에 취급되어야 하는 경우가 많으며, 일부 제품의 경우 2℃에서 8℃, 혹은 그보다 더 좁은 온도 범위 내에서 관리되어야 합니다. 이러한 제품의 운송에는 표준 화물 처리 절차뿐만 아니라, 인증된 포장재, 교정된 모니터링 장비, 그리고 온도 편차가 발생했을 때의 대응 절차에 대한 문서화가 필수적입니다. 이러한 요건으로 인해 제품의 안정성, 임상 현장에서의 가용성, 그리고 문서화된 품질관리가 모두 중요한 고려 사항이 되는 출하 과정에서 인증을 받은 물류 제공업체의 역할은 더욱 중요해지고 있습니다.
GDP 준수 의약품 유통 네트워크의 확대
태국의 적정 유통 기준(GDP) 요건은 의약품 물류 사업자가 콜드 체인 활동을 조직하는 방식을 변화시켰습니다. 태국 식품의약품청(FDA)의 프레임워크에 따르면 의약품 도매업자는 운송, 보관, 모니터링 및 외부 위탁 활동을 포괄하는 품질관리 시스템을 유지해야 하며, 각 공급업체와의 관계에서 책임 소재가 명확해야 합니다. 기존 의약품 면허 소지자는 2026년 1월부터 문서화된 콜드 체인 계획 및 교정된 온도 모니터링 등을 포함한 1단계 품질관리 요건을 준수해야 합니다. 추가적인 품질 시스템 요건은 2027년 1월부터 의무화될 예정이며, 3단계의 완전한 준수는 2029년 1월로 예정되어 있습니다. 따라서 수입업자, 포워더, 취급 대리점 및 보세 창고 운영자는 물류 업체에 대한 비공식적인 위탁에 의존하지 않고, 각 인계 단계에서 감사 가능한 관리 체제를 유지해야 합니다. 이를 통해 인증된 냉장실, 모니터링 시스템, 액티브 컨테이너, 문서화된 하도급 계약, 그리고 화주에 의한 감사를 지원할 수 있는 국제적으로 인정된 인증에 대한 투자가 촉진되고 있습니다.
인증된 포장, 드라이아이스 및 액티브 컨테이너의 높은 비용
태국의 의약품 콜드체인 항공 물류 시장에서 인증된 포장재와 액티브 컨테이너는 의약품 항공 운송에 막대한 비용을 부과하고 있습니다. WHO 지침에 따르면 운송용 컨테이너는 인증을 받아야 하며, 설계, 운영 및 성능 인증을 포함한 관련 운영 조건 하에서 그 열적 성능이 입증되어야 합니다. 이 요건으로 인해 특정 운송 경로나 취급 조건에 대해 검증되지 않은 저비용 포장 옵션의 사용이 제한되고 있습니다. 세포·유전자 치료제의 경우, 드라이아이스나 기타 극저온 냉각 시스템 외에도 훈련을 받은 취급 인력과 위험물 관리가 필요할 수 있습니다. WHO의 백신 운송 지침에서도 포장재 및 냉각재 관리를 포함하여 국제 운송 중 제품의 상태를 유지해야 할 필요성이 지적되고 있습니다. 장거리 또는 복잡한 경로를 위한 능동형 컨테이너는 표준 냉장 운송에 비해 단위당 비용이 300%에서 500%까지 높아질 수 있습니다. 또한 드라이아이스의 입수 가능성은 출발지나 경유지 공항에 따라 다를 수 있으며, 이 경우 적재 밀도를 낮추어 비용 증가로 이어지는 대체 포장 기법이 필요할 수 있습니다. 이러한 비용 부담이 가장 큰 것은 소규모 수하인, 공공 조달 기관, 그리고 낮은 이익률로 인해 고가의 물류 서비스를 감당할 수 없는 제품입니다. 이러한 요인으로 인해 다른 온도 관리가 필요한 의약품도 동일한 수준의 관리 혜택을 받을 수 있음에도 불구하고 적격 항공 콜드 체인의 이용은 고부가가치 제품에 집중되어 있습니다.
부문 분석
2025년, 태국의 의약품 콜드체인 항공 물류 시장 규모 중 냉동 제품이 52.55%를 차지했습니다. 이 범주에는 확립된 유통 시스템을 통해 운송되는 다수의 백신, 냉동 혈액 제제 및 생물제제의 수입품이 포함됩니다. 냉동 제품의 온도 범위는 -20°C에서 0°C까지이며, 사무트프라칸 주 및 방콕 수도권 소재의 GDP 인증 시설에 의해 지원됩니다. 가장 빠른 성장이 예상되는 분야는 초저온 및 극저온 제품입니다. 이는 드라이아이스나 기상 액체 질소 조건이 필요한 세포 치료, 유전자 치료, 동결 보존 제품 및 첨단 생물제제에 대한 수요를 반영한 것입니다.
초저온 및 극저온 제품 시장 규모는 2026-2031년에 연평균 성장률(CAGR) 11.77%로 확대될 것으로 예측됩니다. 한편, 모노클로널 항체, 재조합 단백질, 특수 주사제의 운송에 있어서는 냉장 운송이 여전히 중요한 역할을 하고 있습니다. IATA 지침에는 이러한 제품의 상당수에 적용되는 2℃-8℃의 서비스 수준이 규정되어 있습니다. 15℃-25℃에서 운송되는 상온 제품의 경우, 긴급성이 없는 많은 화물은 육상 운송으로 처리할 수 있으므로 항공 화물로서의 기회는 비교적 적다고 할 수 있습니다. 초저온 취급에는 확립된 냉동 공정을 뛰어넘는 프로토콜이 필요합니다. 이러한 화물에는 인증된 컨테이너, 전용 자재, 그리고 드라이아이스 및 기타 극저온 시스템을 관리하기 위해 훈련을 받은 직원이 필요합니다. Genepeutic Bio사가 태국에 보유한 GMP 인증을 받은 세포·유전자 치료 시설은 향후 초저온 물류 수요를 창출할 가능성이 있는 국내 사업을 확대하고 있습니다. 또한 현장 진료(Point-of-Care) 치료 및 자가 치료 역시 채취 거점, 제조 거점, 치료 센터 간의 양방향 운송을 발생시키고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요와 의약품 콜드체인 항공화물 물류의 중요성
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 및 유통 채널 구조 분석
- 규제 프레임워크 및 컴플라이언스 요건의 개요
- 기술 혁신 전망
- 주요 의약품 항공화물 허브공항과 인프라
- 의약품의 수출 입동향과 주요 무역 루트
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 온도 범위별
- 의약품 제품 유형별
- 출하 동향별
- 지역별
- 중앙
- 동부
- 북부
- 북동부
- 남부
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- DHL Group
- Kuehne+Nagel International AG
- DSV A/S
- Nippon Express Holdings, Inc.
- United Parcel Service, Inc.
- FedEx Corporation
- Cencora, Inc.(World Courier)
- Yusen Logistics Co., Ltd
- LOGISTEED, Ltd
- CEVA Logistics(CMA CGM Group)
- DKSH Holding Ltd
- Zuellig Pharma
- KWE-Kintetsu World Express
- Bangkok Flight Services
- Thai Airways International PCL
- SCGJWD Logistics Public Company Limited
- Inter Express Logistics Co., Ltd
- Rhenus Group
- A.P. Moller-Maersk
- Expeditors International of Washington, Inc.
- Konoike Transport Co., Ltd./Konoike Group Thailand
- KLN Logistics Group Limited
제7장 시장 기회와 향후 전망
제8장 부록
KSA 26.10.29According to Mordor Intelligence, the Thailand pharmaceutical cold chain air logistics market size was valued at USD 74.46 million in 2025, and is projected to grow from USD 80.55 million in 2026 to reach USD 117.19 million in 2031, registering a CAGR of 7.79% from 2026 to 2031.
Thailand Pharmaceutical Cold Chain Air Logistics Market Trends and Insights
Growth in Biologics, Vaccines, and Specialty Medicines
Biologics and specialty medicines are increasing the technical requirements placed on Thailand pharmaceutical cold chain air logistics market providers. These products need stable conditions from the manufacturing origin through airport handling, customs clearance, and final delivery to a clinical destination. WHO guidance states that time and temperature-sensitive pharmaceutical products require controlled storage and transport arrangements that protect product quality, including during handoffs between supply chain partners. Monoclonal antibodies, enzyme replacement therapies, vaccines, and blood-derived products often need tightly controlled handling during air transit, with some products requiring 2 °C to 8 °C or narrower conditions. Their movement depends on qualified packaging, calibrated monitoring equipment, and documented action when a temperature deviation occurs, rather than standard cargo processes alone. This requirement gives certified logistics providers a stronger role in shipments where product stability, clinical availability, and documented quality controls are all material considerations.
Expansion of GDP-Compliant Pharmaceutical Distribution Networks
Thailand's Good Distribution Practice requirements have changed how pharmaceutical logistics providers organize cold chain activities. The Thai FDA's framework requires pharmaceutical distributors to maintain quality systems that cover transport, storage, monitoring, and outsourced activities, with responsibilities that remain visible across each supplier relationship. Existing pharmaceutical licensees faced mandatory Phase 1 quality-management requirements in January 2026, including documented cold chain plans and calibrated temperature monitoring. Additional quality-system requirements are due to become mandatory in January 2027, while full Phase 3 compliance is scheduled for January 2029. Importers, freight forwarders, handling agents, and bonded storage operators must therefore maintain auditable controls across each handoff instead of relying on informal delegation to a logistics provider. This is encouraging investment in qualified cold rooms, monitoring systems, active containers, documented subcontractor arrangements, and internationally recognized certification that can support shipper audits.
High Cost of Qualified Packaging, Dry Ice, and Active Containers
Qualified packaging and active containers add a high cost to pharmaceutical air shipments in the Thailand pharmaceutical cold chain air logistics market. WHO guidance requires shipping containers to be qualified so that their thermal performance is shown under relevant operating conditions, including design, operational, and performance qualification. The requirement limits the use of lower-cost packaging options that have not been validated for the intended route and handling conditions. Cell and gene therapies may require dry ice or other cryogenic cooling systems, as well as trained handling and dangerous goods controls. WHO vaccine shipping guidance also addresses the need to maintain product conditions during international transport, including the management of packaging and cooling materials. Active containers for long or complex routes can cost 300% to 500% more than standard refrigerated transport per unit. Dry ice availability can also differ across origin and transit airports, which may require backup packaging approaches that reduce payload density and add expense. The cost burden is greatest for smaller consignees, public procurement bodies, and products whose margin cannot absorb a premium logistics service. These factors concentrate qualified air cold chain use in high-value products, even when other temperature-sensitive medicines can benefit from the same level of control.
Other drivers and restraints analyzed in the detailed report include:
- Thailand's Development as a Regional Medical Hub
- Validated Air Freight, Clinical Trial Logistics, and Digital Visibility
- Certified Airport Capacity, Excursion Risk, and Skills Shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Frozen products held 52.55% of the Thailand pharmaceutical cold chain air logistics market size in 2025. This range covers many vaccines, frozen blood products, and biologic imports that move through established distribution systems. The frozen range extends from -20 °C to 0 °C and is supported by GDP-certified facilities in Samut Prakan and the Bangkok metropolitan area. The fastest expected expansion is in deep-frozen and ultra-low temperature products. It reflects demand from cell therapies, gene therapies, cryopreserved products, and advanced biologics that require dry ice or vapor-phase liquid nitrogen conditions.
Deep-frozen and ultra-low temperature products are forecast to expand at an 11.77% CAGR from 2026 to 2031. Chilled shipments remain important for monoclonal antibodies, recombinant proteins, and specialty injectables. IATA guidance identifies a 2 °C to 8 °C service level that is relevant to many of these products. Ambient products transported at 15 °C to 25 °C represent a smaller air freight opportunity because surface transport can serve many non-urgent shipments. Ultra-low temperature handling requires protocols that go beyond established frozen processes. These shipments need qualified containers, specialized materials, and staff trained to manage dry ice or other cryogenic systems. Genepeutic Bio's GMP-certified cell and gene therapy facility in Thailand adds domestic activity that can create future ultra-low temperature logistics demand. Point-of-care and autologous therapies also create two-way movements between collection sites, manufacturing locations, and treatment centers.
Complete Report Scope:
- By Temperature Range
- Chilled (0-5 °C)
- Frozen (-20-0 °C)
- Ambient
- Deep-Frozen / Ultra-Low (Less than -20 °C)
- By Pharmaceutical Product Type
- Small-Molecule Pharmaceuticals
- Branded Pharmaceuticals
- Over-the-Counter (OTC) Pharmaceuticals
- Generic Pharmaceuticals
- Biological Pharmaceuticals (Biologics, Biosimilars, Vaccines, and Blood-Derived Medicinal Products)
- Specialty Pharmaceuticals
- Cell and Gene Therapies
- Veterinary Pharmaceuticals
- Other Pharmaceutical Products
- Small-Molecule Pharmaceuticals
- By Shipment Flow
- Domestic Shipments
- International Shipments
- By Region
- Central
- Eastern
- Northern
- Northeastern
- Southern
List of Companies Covered in this Report:
- DHL Group
- Kuehne+Nagel International AG
- DSV A/S
- Nippon Express Holdings, Inc.
- United Parcel Service, Inc.
- FedEx Corporation
- Cencora, Inc. (World Courier)
- Yusen Logistics Co., Ltd
- LOGISTEED, Ltd
- CEVA Logistics (CMA CGM Group)
- DKSH Holding Ltd
- Zuellig Pharma
- KWE-Kintetsu World Express
- Bangkok Flight Services
- Thai Airways International PCL
- SCGJWD Logistics Public Company Limited
- Inter Express Logistics Co., Ltd
- Rhenus Group
- A.P. Moller - Maersk
- Expeditors International of Washington, Inc.
- Konoike Transport Co., Ltd. / Konoike Group Thailand
- KLN Logistics Group Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview and Importance of Pharmaceutical Cold Chain Air Freight Logistics
- 4.2 Market Drivers
- 4.2.1 Expansion of GDP-Compliant Pharmaceutical Distribution Networks
- 4.2.2 Growth in Biologics, Vaccines, and Specialty Medicines
- 4.2.3 Thailand's Development as a Regional Medical Hub
- 4.2.4 Increasing Use of Validated Temperature-Controlled Air Freight
- 4.2.5 Expansion of Clinical Trial and Cell and Gene Therapy Logistics
- 4.2.6 Digital Temperature Visibility and Predictive Excursion Management
- 4.3 Market Restraints
- 4.3.1 High Cost of Qualified Packaging, Dry Ice, and Active Containers
- 4.3.2 Limited Pharmaceutical Air-Cargo Capacity at Certified Airport Facilities
- 4.3.3 Temperature Excursion Risk During Customs Clearance and Ramp Handling
- 4.3.4 Shortage of Specialized Cold-Chain Quality and Refrigeration Personnel
- 4.4 Value Chain and Distribution Channel Architecture Analysis
- 4.5 Regulatory Framework and Compliance Requirements Overview
- 4.6 Technology Innovations Outlook
- 4.7 Major Pharmaceutical Air Cargo Gateways and Infrastructure
- 4.8 Pharmaceutical Import Export Flows and Major Trade Corridors
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Buyers and Consumers
- 4.9.3 Bargaining Power of Suppliers
- 4.9.4 Threat of Substitute Services
- 4.9.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Temperature Range
- 5.1.1 Chilled (0-5 °C)
- 5.1.2 Frozen (-20-0 °C)
- 5.1.3 Ambient
- 5.1.4 Deep-Frozen / Ultra-Low (Less than -20 °C)
- 5.2 By Pharmaceutical Product Type
- 5.2.1 Small-Molecule Pharmaceuticals
- 5.2.1.1 Branded Pharmaceuticals
- 5.2.1.2 Over-the-Counter (OTC) Pharmaceuticals
- 5.2.1.3 Generic Pharmaceuticals
- 5.2.2 Biological Pharmaceuticals (Biologics, Biosimilars, Vaccines, and Blood-Derived Medicinal Products)
- 5.2.3 Specialty Pharmaceuticals
- 5.2.4 Cell and Gene Therapies
- 5.2.5 Veterinary Pharmaceuticals
- 5.2.6 Other Pharmaceutical Products
- 5.2.1 Small-Molecule Pharmaceuticals
- 5.3 By Shipment Flow
- 5.3.1 Domestic Shipments
- 5.3.2 International Shipments
- 5.4 By Region
- 5.4.1 Central
- 5.4.2 Eastern
- 5.4.3 Northern
- 5.4.4 Northeastern
- 5.4.5 Southern
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Geographic Coverage, Products and Services, Recent Developments)
- 6.4.1 DHL Group
- 6.4.2 Kuehne+Nagel International AG
- 6.4.3 DSV A/S
- 6.4.4 Nippon Express Holdings, Inc.
- 6.4.5 United Parcel Service, Inc.
- 6.4.6 FedEx Corporation
- 6.4.7 Cencora, Inc. (World Courier)
- 6.4.8 Yusen Logistics Co., Ltd
- 6.4.9 LOGISTEED, Ltd
- 6.4.10 CEVA Logistics (CMA CGM Group)
- 6.4.11 DKSH Holding Ltd
- 6.4.12 Zuellig Pharma
- 6.4.13 KWE-Kintetsu World Express
- 6.4.14 Bangkok Flight Services
- 6.4.15 Thai Airways International PCL
- 6.4.16 SCGJWD Logistics Public Company Limited
- 6.4.17 Inter Express Logistics Co., Ltd
- 6.4.18 Rhenus Group
- 6.4.19 A.P. Moller - Maersk
- 6.4.20 Expeditors International of Washington, Inc.
- 6.4.21 Konoike Transport Co., Ltd. / Konoike Group Thailand
- 6.4.22 KLN Logistics Group Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


