

|
시장보고서
상품코드
2157073
인도네시아의 화물 운송 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Indonesia Freight Forwarding - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
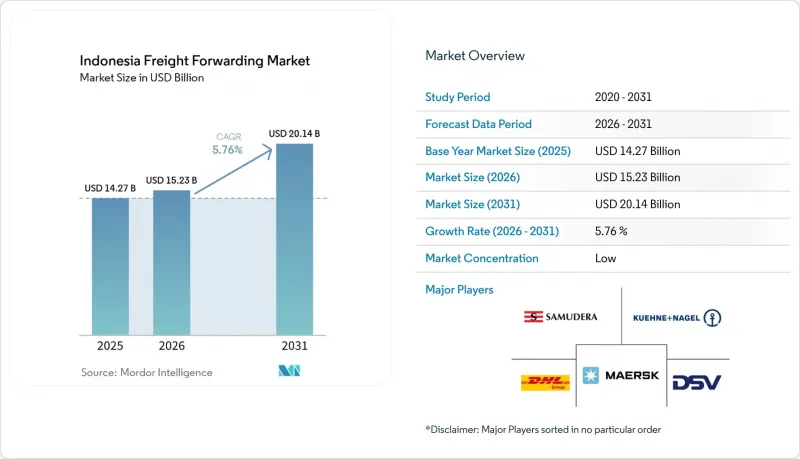
에 따르면 인도네시아의 포워딩 시장 규모는 2025년에 142억 7,000만 달러로 평가되며, 2026년 152억 3,000만 달러에서 2031년까지 201억 4,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 5.76%에 달할 전망입니다.
인도네시아 포워딩 시장의 동향 및 인사이트
수출 지향형 제조업 및 특수 화물 확대
인도네시아의 다운스트림화 정책에 따라 니켈, 구리, 보크사이트의 가공이 산지 인근으로 이전되고 있으며, 반제품, 산업용 장비 및 관련 서류의 국제 운송이 증가하고 있습니다. 2026년 4월 제조업 수출액은 755억 7,000만 달러에 달했으며, 중국, 미국, 인도가 주요 수출처인 만큼 공급업체의 서류, 원산지 증명서 및 취급 요건을 조정해 주는 포워더에 대한 수요가 지원되고 있습니다. 또한 제련소 및 정제소 건설에 따라 벌크 화물 및 중량물 운송 능력이 필요한 초대형 장비의 프로젝트 물류 수요도 발생하고 있습니다. 한편, 의료, 화학, 전기자동차(EV) 관련 화물의 경우 위험물 취급, 온도 관리, 법규 준수 기록 및 시간 지정 배송이 요구됩니다. 적시 생산(JIT) 및 전기자동차 부품 순차 배송의 증가로 서비스 요건이 더욱 높아지고 있으며, 표준적인 컨테이너 중개 업무를 넘어선 전문적인 역량을 갖춘 사업자에게는 새로운 비즈니스 기회가 창출되고 있습니다.
크로스보더 E-Commerce와 소비재 수입
소량 화물의 증가로 인해 화물 구성은 평균 출하 중량의 감소로 전환되고 있으며, 혼재, LCL(컨테이너 미만 적재), 항공 화물 서비스에 대한 수요가 높아지고 있습니다. 인도네시아의 포워딩 시장은 E-Commerce 판매업체들이 빈번한 발송을 필요로 하는 한편, 국내 풀필먼트가 세관 관리 하의 거점과 지역 배송 네트워크를 연결해 주는 데서 혜택을 받고 있습니다. 이로 인해 포워딩, 보관, 통관 절차, 배송 인도를 통합하여 제공하는 사업자가 유리한 입장에 서게 되지만, 자체 물류 역량을 구축하는 마켓플레이스와의 경쟁은 격화되고 있습니다. 수요는 자바섬과 수마트라섬에 그치지 않고, 술라웨시섬과 발리섬 등의 시장으로도 확대되고 있습니다. 동시에, 디지털 견적 및 서류 작성 자동화를 통해 소규모 수입업자의 이용 편의성이 향상되고, 대량이며 저가치의 화물 처리가 간소화됩니다. 그러나 소량 화물 1건당 수익이 감소하고 있으며, 효율적인 혼적, 예측 가능한 인도, 투명한 가격 책정이 요구되고 있으며, 화물의 가치를 지키기 위해서는 국제 운송부터 국내 배송에 이르는 풀필먼트 통합이 중요해집니다.
항만의 혼잡과 통관 절차의 복잡성
탄중 프리옥 항구는 인도네시아 수입의 대부분과 국내 컨테이너 처리량의 약 40%를 담당하고 있으며, 선박 대기 줄의 장기화, 야드 가동률 상승, 체선료 위험 증가를 통해 인도네시아 포워딩 시장에 있으며, 혼잡이 주요 위험 요인으로 대두되고 있습니다. 2026년 3월부터 4월에 걸친 이드 연휴 이후 성수기 동안, 통합 물류 흐름 관리 지휘 센터가 터미널, 트럭 운송사, 공공기관 간의 조정을 담당했으나, 새로운 터미널 용량 확충만으로는 도로 접근성이나 트럭 일정 조정에 관한 제약을 즉시 해소할 수 없었기 때문에 포워더는 운송 시간이나 화물 인도 계획에 지연을 예상해야 했습니다. 또한 통관 절차에는 관세, 소비세, 검역, BPOM(인도네시아 식품의약품감독청) 및 업종별 라이선싱에 관한 조정이 필요하며, 수작업에 의존하는 프로세스로 인해 서류상의 리스크가 높아지고 있습니다. KBLI 2025 개정안에 대해 ALFI를 통해 약 600개의 포워더 및 물류 기업이 이의를 제기하고 있으며, 통합형 서비스 모델 및 관련 투자에 불확실성이 발생하고 있습니다. 화물 도착 전 서류 확인 체계와 강력한 규제 대응 능력을 갖춘 서비스 제공업체는 통관 지연 및 과태료 위험을 완화할 수 있습니다.
부문 분석
2025년 현재, 인도네시아 포워딩 시장 점유율의 72.86%를 해상 포워딩이 차지하고 있는 반면, 항공 포워딩은 2031년까지 연평균 성장률(CAGR) 7.98%로 확대될 것으로 예측됩니다. 해상 운송은 비용 효율적인 장거리 운송이 필요한 컨테이너화된 상품, 반제품 및 제조품을 대상으로 합니다. FCL(Full Container Load) 서비스는 팜유, 석탄, 니켈 제품, 의류 및 관련 카테고리에서 정기적인 수출 계약을 맺고 있는 대규모 화주를 지원합니다. 소량 컨테이너 운송(LCL)은 보다 유연한 발송 시기가 필요하고 컨테이너를 가득 채울 수 없는 공급업체를 지원합니다. 육상 운송은 자바 섬 전역 및 수마트라 횡단 회랑에 걸쳐 있는 공장, 창고, 터미널을 연결합니다. 이러한 ‘퍼스트 마일’ 및 ‘라스트 마일’ 기능은 주요 화물이 해상 운송되는 경우에도 필수적입니다.
인도네시아 항공 화물 포워딩 시장 규모는 반도체 부품, 의약품, 패션 상품 등 고부가가치이며 시간적 제약이 엄격한 화물에 의해 지탱되고 있습니다. 항공 운송 서비스는 해상 운송으로는 대응할 수 없는 짧은 납기 요건을 충족시킬 수 있습니다. DHL 익스프레스는 2025년 12월에 업그레이드된 수라바야 게이트웨이를 개장하고, 자카르타 게이트웨이의 운송 능력을 확대하고 있습니다. 철도 포워딩은 화물 네트워크가 자바 섬에 집중되어 있고, 궤간 및 운송 능력의 제약에 직면해 있으며, 여전히 제한적입니다. 생산 지역과 자바 섬의 물류 센터 사이를 이동하는 팔레트 적재 농산물 및 일용 소비재의 경우, 해상·육로 복합 운송(인터모달)의 선택지가 점점 더 중요해지고 있습니다. 다국적 화주들은 규정을 준수하는 항공 화물 서비스를 선택할 때, 국제항공운송협회(IATA)의 위험물 및 의약품 관련 기준을 점점 더 많이 활용하고 있습니다.
2025년 현재, 인도네시아 포워딩 시장 규모의 68.43%를 대기업이 차지하고 있는 반면, 중소기업은 2031년까지 연평균 성장률(CAGR) 9.56%를 기록할 것으로 예측됩니다. 주요 고객으로는 다국적 제조업체, 국영 에너지 기업, 그리고 대개 우선 운송업체 계약을 통해 사업을 운영하는 대형 소매업체가 포함됩니다. 이러한 고객들의 지속적인 화물 발송량은 포워더의 게이트웨이, 창고 시설 및 인가된 통관 업무 역량에 대한 투자를 지원할 뿐만 아니라, 운송업체와의 협상력을 강화하고 있습니다. 또한 주요 고객들은 신뢰할 수 있는 운송 능력, 규정 준수 및 서비스의 지속성을 우선시하고 있으며, 인도네시아 포워딩 업계에서 오랜 역사를 가진 사업자들의 입지를 지원하고 있습니다.
온라인 견적, 전자 선하증권, 디지털 통관 신고를 통해 소규모 수출업체의 실질적인 진입 장벽이 낮아졌습니다. 식품 가공업체, 수공예품 제조업체, 전자기기 공급업체, 특수 화학제품 제조업체는 소량의 화물이라도 국제 화물 운송 서비스를 이용할 수 있게 되었습니다. 이러한 고객들은 대개 화물 추적, 유연한 혼적 일정, 관세 서류 작성 지원을 필요로 합니다. DSV는 2026년 5월, DB 쉔커를 PT DSV 트랜스포트 인도네시아에 통합하여 통합 후 회사의 현지 서비스 제공 범위를 확대했습니다. 이러한 서비스 범위 확대를 통해 중견 기업에도 기업 수준의 서비스 옵션이 제공될 가능성이 있습니다. 규제 대상 품목의 경우, 라이선스 요건으로 인해 비공식 중개업자보다 이미 입지를 다진 공인 공급업체가 여전히 우대받고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
- 시장 규모, 성장률 및 예측
- 주요 수요 견인 요인과 포워딩의 동향
- 주요 무역 회랑과 화물 유량 집중
- 경쟁 구도와 주요 포워더
제4장 시장 구도
- 시장 개요와 포워딩의 중요성
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 구조와 포워딩 흘러의 분석
- 국제 화물 운송에서 규제 및 통관 프레임워크에 관한 분석
- 화물 운송 업무에서 테크놀러지의 도입
- 국내 및 국제 화물 유동 패턴의 분석
- 운임 및 포워딩 마진 구조 분석
- 주요항 및 게이트웨이에서 화물 집중도의 분석
- Porter's Five Forces 분석
- 지정학적 이벤트가 공급망의 변화에 미치는 영향
제5장 시장 규모와 성장 예측
- 운송 모드별
- 기업 규모별
- 포워더 모델별
- 최종사용자 산업별
- 화물 구성별
- 지역별
- Java(자카르타 및 BOD)
- 수마트라
- 보르네오
- 술라웨시
- 발리 및 누사 텡가라
- 파푸아 지역 및 말루쿠 제도
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- DHL Group
- DSV A/S
- Kuehne+Nagel
- A.P. Moller-Maersk
- CEVA Logistics(CMA CGM Group)
- NX Group/PT NX Lemo Indonesia Logistik
- Expeditors International
- GEODIS
- Yusen Logistics
- DP World
- KLN Logistics Group Limited
- Sinotrans Limited
- CJ Logistics
- PT Samudera Indonesia Tbk
- Meratus Group
- PT Cipta Krida Bahari(CKB Logistics)
- PT Kamadjaja Logistics
- PT Puninar Logistics
- PT Kintetsu World Express Indonesia(KWE)
- PT Multi Terminal Indonesia(MTI)
- JNE Freight/PT Tiki Jalur Nugraha Ekakurir
- Rhenus Logistics
제7장 시장 기회와 향후 전망
제8장 부록
KSA 26.10.30According to Mordor Intelligence, the Indonesia freight forwarding market size was valued at USD 14.27 billion in 2025, and is estimated to grow from USD 15.23 billion in 2026 to reach USD 20.14 billion by 2031, at a CAGR of 5.76% during the forecast period (2026-2031).
Indonesia Freight Forwarding Market Trends and Insights
Expansion of Export-Oriented Manufacturing and Specialized Cargo
Indonesia's downstreaming policy is shifting nickel, copper, and bauxite processing closer to source locations, increasing international shipments of semi-finished goods, industrial equipment, and related documentation. Manufacturing exports reached USD 75.57 billion in April 2026, with China, the United States, and India as important destinations, supporting demand for freight forwarders that coordinate supplier documents, origin certificates, and handling requirements. Smelter and refinery construction also creates project logistics demand for oversized equipment requiring breakbulk and heavy-lift capabilities. In contrast, healthcare, chemical, and EV cargo require dangerous goods handling, temperature control, compliant records, and timed delivery. Rising just-in-time manufacturing and EV component sequencing further increase service requirements, creating opportunities for providers with specialized capabilities beyond standard container brokerage.
Cross-Border E-Commerce and Consumer-Goods Imports
Smaller parcels are shifting freight mixes toward lower average shipment weights, increasing demand for consolidation, less-than-container-load, and air cargo services. The Indonesia freight forwarding market benefits as e-commerce sellers require frequent dispatches, while domestic fulfillment connects customs-controlled locations with local delivery networks. This favors providers offering integrated forwarding, storage, customs processing, and delivery handoffs, although competition is increasing from marketplaces developing in-house logistics capabilities. Demand extends beyond Java and Sumatra to markets such as Sulawesi and Bali. At the same time, digital quotation and automated documentation can improve access for smaller importers and simplify high-volume, low-value shipments. However, lower revenue per parcel requires efficient consolidation, predictable handoffs, and transparent pricing, making international-to-domestic fulfillment integration important for protecting shipment value.
Port Congestion and Customs Complexity
Tanjung Priok handles the majority of Indonesia's imports and around 40% of national container throughput, making congestion a key risk for the Indonesia freight forwarding market through longer vessel queues, higher yard occupancy, and greater demurrage exposure. During the March-April 2026 post-Eid peak, an Integrated Logistics Flow Control Command Center coordinated terminals, trucking firms, and public agencies, but new terminal capacity did not immediately address road access and truck-scheduling constraints, requiring forwarders to factor delays into transit times and cargo release planning. Customs clearance also requires coordination across duty, excise, quarantine, BPOM, and sector-specific licensing, with manual processes increasing documentation risks. The KBLI 2025 revision is being contested by around 600 freight-forwarding and logistics companies through ALFI, creating uncertainty for integrated service models and related investments. Providers with pre-arrival document checks and strong regulatory capabilities can reduce clearance delays and penalty risks.
Other drivers and restraints analyzed in the detailed report include:
- Port, Airport, Corridor Modernization and Digitalization
- Inter-Island Consolidation and Secondary Economic Hubs
- Network Imbalance and Uneven System Interoperability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ocean freight forwarding held 72.86% of the Indonesia freight forwarding market share in 2025, while air freight forwarding is forecast to expand at a 7.98% CAGR through 2031. The ocean freight serves containerized commodities, semi-processed products, and manufactured goods that need cost-effective long-distance transport. Full-container-load services support large shippers with regular export contracts in palm oil, coal, nickel products, garments, and related categories. Less-than-container-load movements serve suppliers that need more flexible dispatch timing and cannot fill a full container. Road forwarding connects factories, warehouses, and terminals across Java and the trans-Sumatra corridor. These first-mile and last-mile functions remain essential even when the main shipment moves by sea.
The Indonesia freight forwarding market size for air freight forwarding benefits from higher-value and time-sensitive cargo such as semiconductor components, pharmaceuticals, and fashion goods. Air services can meet short transit requirements that ocean movements cannot support. DHL Express opened an upgraded Surabaya Gateway in December 2025 and is expanding capacity at Jakarta Gateway. Rail forwarding remains limited because the freight network is concentrated on Java and faces gauge and capacity constraints. Sea-road intermodal options are becoming more relevant for palletized agricultural and fast-moving consumer goods between production areas and Java distribution centers. International Air Transport Association dangerous-goods and pharmaceutical standards are increasingly used by multinational shippers when selecting compliant air cargo services.
Large enterprises held 68.43% of the Indonesia freight forwarding market size in 2025, while small and medium enterprises are forecast to register at a 9.56% CAGR through 2031. Key customers include multinational manufacturers, state-owned energy companies, and large retailers that typically operate through preferred-carrier agreements. Their recurring shipment volumes support forwarders' investments in gateways, warehousing facilities, and licensed brokerage capabilities, while strengthening negotiating power with carriers. Large customers also prioritize reliable capacity, regulatory compliance, and service continuity, supporting the role of established operators in Indonesia's freight forwarding industry.
Online quotation, electronic bills of lading, and digital customs filing reduce the practical entry threshold for smaller exporters. Food processors, handicraft producers, electronics suppliers, and specialty chemical firms can access international freight services with smaller shipment sizes. These customers often require tracking, flexible consolidation schedules, and help with duty documentation. DSV completed its integration of DB Schenker into PT DSV Transport Indonesia in May 2026, expanding the combined company's local service coverage. This broader coverage may extend enterprise-grade service options to mid-market accounts. Import licensing requirements still favor established and licensed providers over informal brokers for regulated goods.
Complete Report Scope:
- By Mode of Transport
- Ocean Freight Forwarding
- Full Container Load (FCL)
- Less-Than-Container Load (LCL)
- Road Freight Forwarding
- Full Truck Load (FTL)
- Less-Than-Truck Load (LTL)
- Air Freight Forwarding
- Rail Freight Forwarding
- Multimodal and Intermodal Forwarding
- Ocean Freight Forwarding
- By Enterprise Size
- Small and Medium Enterprises
- Large Enterprises
- By Forwarder Model
- Traditional Asset-Light Forwarders
- Digital-First / Online Platforms
- Hybrid Asset-Enabled Forwarders
- By End-User Industry
- Industrial and Manufacturing
- Retail and E-commerce
- Healthcare and Pharmaceuticals
- Oil, Gas and Energy
- Food and Beverages
- Automotive
- Chemicals
- Other End-Users
- By Cargo Configuration
- Containerized Cargo
- Breakbulk and Project Cargo
- Dry Bulk Cargo
- Liquid Bulk Cargo
- By Region
- Java (Jakarta and BOD)
- Sumatra
- Kalimantan
- Sulawesi
- Bali and Nusa Tenggara
- Papua Region and Maluku Islands
List of Companies Covered in this Report:
- DHL Group
- DSV A/S
- Kuehne+Nagel
- A.P. Moller - Maersk
- CEVA Logistics (CMA CGM Group)
- NX Group / PT NX Lemo Indonesia Logistik
- Expeditors International
- GEODIS
- Yusen Logistics
- DP World
- KLN Logistics Group Limited
- Sinotrans Limited
- CJ Logistics
- PT Samudera Indonesia Tbk
- Meratus Group
- PT Cipta Krida Bahari (CKB Logistics)
- PT Kamadjaja Logistics
- PT Puninar Logistics
- PT Kintetsu World Express Indonesia (KWE)
- PT Multi Terminal Indonesia (MTI)
- JNE Freight / PT Tiki Jalur Nugraha Ekakurir
- Rhenus Logistics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
- 3.1 Market Size, Growth, and Forecast Outlook
- 3.2 Key Demand Drivers and Freight Forwarding Trends
- 3.3 Major Trade Corridors and Cargo Flow Concentration
- 3.4 Competitive Landscape and Leading Freight Forwarders
4 MARKET LANDSCAPE
- 4.1 Market Overview and Importance of Freight Forwarding
- 4.2 Market Drivers
- 4.2.1 Expansion of Export-Oriented Manufacturing
- 4.2.2 Cross-Border E-Commerce and Consumer-Goods Imports
- 4.2.3 Port, Airport and National Logistics-Corridor Modernization
- 4.2.4 National Logistics Ecosystem Digitalization
- 4.2.5 Specialized EV, Healthcare and Cold-Chain Cargo Flows
- 4.2.6 Inter-Island Consolidation Demand from Secondary Economic Hubs
- 4.3 Market Restraints
- 4.3.1 Port Congestion and Container-Yard Constraints
- 4.3.2 Customs Complexity and Documentation Risk
- 4.3.3 Inter-Island Network Imbalance and Empty-Container Repositioning
- 4.3.4 Uneven Digital-System Interoperability Across Logistics Stakeholders
- 4.4 Value Chain Structure and Freight Forwarding Flow Analysis
- 4.5 Freight Forwarding Regulatory and Customs Framework Analysis
- 4.6 Technology Adoption in Freight Forwarding Operations
- 4.7 Domestic and International Shipment Flow Pattern Analysis
- 4.8 Freight Rates and Forwarding Margin Structure Analysis
- 4.9 Major Port and Gateway Cargo Concentration Analysis
- 4.10 Porter's Five Forces Analysis
- 4.10.1 Threat of New Entrants
- 4.10.2 Bargaining Power of Buyers
- 4.10.3 Bargaining Power of Suppliers
- 4.10.4 Threat of Substitute Services
- 4.10.5 Intensity of Competitive Rivalry
- 4.11 Impact of Geo-Political Events on Supply Chain Shifts
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Mode of Transport
- 5.1.1 Ocean Freight Forwarding
- 5.1.1.1 Full Container Load (FCL)
- 5.1.1.2 Less-Than-Container Load (LCL)
- 5.1.2 Road Freight Forwarding
- 5.1.2.1 Full Truck Load (FTL)
- 5.1.2.2 Less-Than-Truck Load (LTL)
- 5.1.3 Air Freight Forwarding
- 5.1.4 Rail Freight Forwarding
- 5.1.5 Multimodal and Intermodal Forwarding
- 5.1.1 Ocean Freight Forwarding
- 5.2 By Enterprise Size
- 5.2.1 Small and Medium Enterprises
- 5.2.2 Large Enterprises
- 5.3 By Forwarder Model
- 5.3.1 Traditional Asset-Light Forwarders
- 5.3.2 Digital-First / Online Platforms
- 5.3.3 Hybrid Asset-Enabled Forwarders
- 5.4 By End-User Industry
- 5.4.1 Industrial and Manufacturing
- 5.4.2 Retail and E-commerce
- 5.4.3 Healthcare and Pharmaceuticals
- 5.4.4 Oil, Gas and Energy
- 5.4.5 Food and Beverages
- 5.4.6 Automotive
- 5.4.7 Chemicals
- 5.4.8 Other End-Users
- 5.5 By Cargo Configuration
- 5.5.1 Containerized Cargo
- 5.5.2 Breakbulk and Project Cargo
- 5.5.3 Dry Bulk Cargo
- 5.5.4 Liquid Bulk Cargo
- 5.6 By Region
- 5.6.1 Java (Jakarta and BOD)
- 5.6.2 Sumatra
- 5.6.3 Kalimantan
- 5.6.4 Sulawesi
- 5.6.5 Bali and Nusa Tenggara
- 5.6.6 Papua Region and Maluku Islands
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Geographic Coverage, Products and Services, Recent Developments)
- 6.4.1 DHL Group
- 6.4.2 DSV A/S
- 6.4.3 Kuehne+Nagel
- 6.4.4 A.P. Moller - Maersk
- 6.4.5 CEVA Logistics (CMA CGM Group)
- 6.4.6 NX Group / PT NX Lemo Indonesia Logistik
- 6.4.7 Expeditors International
- 6.4.8 GEODIS
- 6.4.9 Yusen Logistics
- 6.4.10 DP World
- 6.4.11 KLN Logistics Group Limited
- 6.4.12 Sinotrans Limited
- 6.4.13 CJ Logistics
- 6.4.14 PT Samudera Indonesia Tbk
- 6.4.15 Meratus Group
- 6.4.16 PT Cipta Krida Bahari (CKB Logistics)
- 6.4.17 PT Kamadjaja Logistics
- 6.4.18 PT Puninar Logistics
- 6.4.19 PT Kintetsu World Express Indonesia (KWE)
- 6.4.20 PT Multi Terminal Indonesia (MTI)
- 6.4.21 JNE Freight / PT Tiki Jalur Nugraha Ekakurir
- 6.4.22 Rhenus Logistics
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space Opportunities and Unmet Freight Forwarding Needs
- 7.2 High-Potential Cargo Segments and Trade Growth Opportunities
- 7.3 Strategic Growth Priorities Across Freight Forwarding Ecosystem
- 7.4 Future Market Outlook and Emerging Trade Demand Pockets


