|
시장보고서
상품코드
2129349
데이터센터용 칠러 시장 : 제품별(공랭식, 수랭식, 액랭식), 기술별(스크롤식, 스크류식, 원심식), 지역별 - 세계 예측(-2032년)Data Center Chillers Market by Product (Air-Cooled Chillers, Water-Cooled Chillers, and Liquid Coolant Chillers), Technology (Scroll Chillers, Screw Chillers, and Centrifugal Chillers), and Region - Global Forecast to 2032 |
||||||

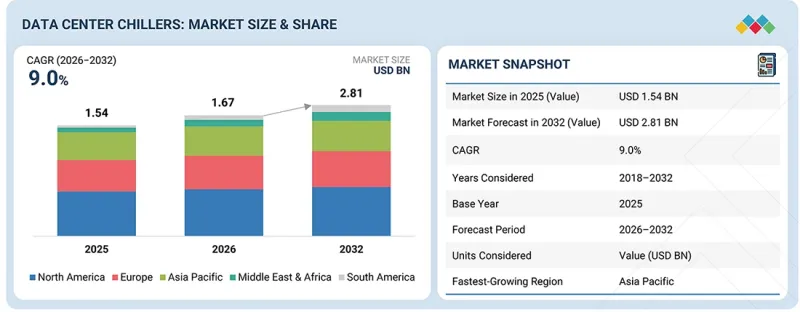
세계의 데이터센터용 칠러 시장 규모는 예측 기간 동안 CAGR 9.0%로 확대되어, 2026년 16억 7,000만 달러에서 2032년에는 28억 1,000만 달러에 달할 것으로 전망됩니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2018-2032년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2032년 |
| 단위 | 금액(달러) |
| 부문 | 제품별, 기술별, 냉각 능력별, 지역별 |
| 대상 지역 | 북미, 아시아태평양, 유럽, 남미, 중동 및 아프리카 |
데이터센터용 칠러는 지속적인 컴퓨팅 처리 과정에서 발생하는 잉여 열을 효율적으로 제거함으로써, 데이터센터가 제어된 운영 환경을 유지할 수 있도록 하는 필수적인 인프라 시스템입니다. 데이터센터가 처리하는 디지털 트래픽의 양이 증가하고, 더욱 복잡한 워크로드를 처리하게 됨에 따라 효과적인 냉각은 장비의 수명, 시스템의 안정성, 서비스 중단 없는 가용성을 확보하기 위한 중요한 요건이 되었습니다. 칠러 시스템은 열 부하의 균형을 조정하는 동시에, 규모가 다른 시설 전반에 걸쳐 최적의 에너지 관리를 실현합니다. 데이터센터용 칠러 시장의 성장은 견고한 컴퓨팅 인프라를 필요로 하는 클라우드 기반 애플리케이션, 디지털 스토리지 서비스, 기업용 데이터 처리, 커넥티드 기술의 채택 확대에 의해 주도되고 있습니다. 또한, 하이퍼스케일 시설에 대한 투자 확대, 엣지 컴퓨팅 네트워크의 확충, 에너지 효율이 높은 데이터센터 운영에 대한 수요 증가가 첨단 냉각 솔루션에 대한 수요를 견인하고 있습니다. 조직들이 디지털 인프라 전략에서 성능, 확장성, 지속가능성을 지속적으로 우선시함에 따라, 데이터센터용 칠러의 도입은 업계 전반에 걸쳐 꾸준히 증가할 것으로 예상됩니다.
“제품별로는 예측 기간 동안 공랭식이 두 번째로 큰 점유율을 차지할 전망”
공랭식 칠러 부문은 설치 요건이 비교적 간단하고 초기 인프라 비용이 낮으며, 광범위한 데이터센터 용도에 적합하기 때문에 두 번째로 큰 점유율을 차지할 것으로 예상됩니다. 수랭식 시스템과 달리, 공랭식 칠러는 냉각탑이나 대규모 물 관리 인프라가 필요하지 않기 때문에 신속한 도입과 운영상의 복잡성 감소를 추구하는 시설에 특히 매력적입니다. 데이터센터 운영자들이 지속가능성과 자원 효율성을 중시하는 가운데, 물 소비량을 최소화하면서도 신뢰성 높은 냉각 성능을 제공할 수 있다는 공랭식 칠러의 장점이 점점 더 중요하게 여겨지고 있습니다. 또한, 엣지 데이터센터, 모듈형 데이터센터, 중소규모 시설의 확대가 진행되고 있는 점도 공랭식 칠러의 도입을 뒷받침하고 있습니다. 이러한 시설에서는 유연성, 유지보수의 용이성, 작은 설치 면적이 우선시되는 경우가 많기 때문입니다. 에너지 효율이 뛰어난 설계와 제어 기술의 지속적인 발전으로 인해 그 성능과 운영 효율은 더욱 향상되고 있습니다. 전 세계적으로 데이터센터에 대한 투자가 지속적으로 확대되는 가운데, 공랭식 칠러의 폭넓은 적용성과 비용 효율적인 냉각 능력은 강력한 시장 입지를 유지하며 데이터센터용 칠러 시장의 성장에 크게 기여할 것으로 예상됩니다.
“기술별로 보면 예측 기간 동안 원심식 칠러 부문이 시장 점유율 2위를 차지할 전망”
원심식 칠러 부문은 대용량 냉각 능력과 높은 운영 효율이 필요한 대규모 및 하이퍼스케일 데이터센터 시설에서 널리 채택되고 있어, 두 번째로 큰 시장 점유율을 차지할 것으로 예상됩니다. 이러한 칠러는 고밀도 서버 환경에서 발생하는 막대한 열 부하 관리에 특히 적합하며, 클라우드 컴퓨팅, AI, 고성능 컴퓨팅 워크로드를 처리하는 대규모 데이터센터에서 선호되는 선택지가 되고 있습니다. 냉각 능력 단위당 에너지 소비량을 억제하면서도 대규모의 효율적인 냉각을 실현하는 능력은 시설 전체의 효율 향상과 운영 비용 절감을 위한 노력을 뒷받침하고 있습니다. 또한, 하이퍼스케일 데이터센터의 지속적인 확장과 전력 사용 효율(PUE) 최적화에 대한 관심 증가도 원심식 칠러 시스템에 대한 투자를 뒷받침하고 있습니다. 압축기 설계 개선, 가변 속도 드라이브, 스마트 모니터링 기능 등 지속적인 기술 혁신을 통해 그 성능과 신뢰성은 더욱 향상되고 있습니다. 대용량 냉각 인프라에 대한 수요가 계속 확대되는 가운데, 원심식 칠러는 중요한 시장 지위를 유지하며 데이터센터용 칠러 시장의 확대에 크게 기여할 것으로 예상됩니다.
“예측 기간 동안 유럽이 두 번째로 큰 시장 점유율을 차지할 전망”
유럽은 확립된 디지털 인프라, 코로케이션 및 하이퍼스케일 데이터센터의 강력한 입지, 클라우드 컴퓨팅 및 기업 데이터 관리에 대한 지속적인 투자로 인해 2위의 시장 점유율을 차지할 것으로 예상됩니다. 이 지역에서는 금융, 의료, 제조, 통신, 정부 서비스 등 다양한 산업 분야의 디지털 전환 노력을 배경으로 데이터 처리 및 스토리지 서비스에 대한 수요가 증가하고 있습니다. 또한, 엄격한 에너지 효율 규제와 지속가능성 목표에 따라 데이터센터 운영 사업자들은 신뢰할 수 있는 성능을 유지하면서 에너지 소비를 줄일 수 있는 첨단 냉각 기술의 도입을 촉진하고 있습니다. 또한, AI 애플리케이션, 엣지 컴퓨팅 시설, 고성능 컴퓨팅(HPC) 인프라의 도입 확대에 따라 해당 지역 전체에서 효율적인 열 관리 솔루션에 대한 수요가 더욱 높아지고 있습니다. 아울러, 기존 데이터센터의 현대화 및 증가하는 디지털 워크로드를 처리하기 위한 신규 시설 건설도 칠러 시스템에 대한 지속적인 수요에 기여하고 있습니다. 사업자들이 운영 효율성, 환경 규제 준수, 인프라의 내결함성에 계속해서 주력함에 따라, 유럽은 데이터센터용 칠러 시장에서 계속해서 큰 점유율을 유지할 것으로 예상됩니다.
본 보고서는 전 세계 데이터센터용 칠러 시장을 조사하여 시장 개요, 시장 성장에 영향을 미치는 다양한 요인에 대한 분석, 기술 및 특허 동향, 법규 환경, 사례 연구, 시장 규모 추정 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 종합적으로 다루고 있습니다.
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술의 진보, AI의 영향, 특허, 혁신, 향후 용도
제7장 지속가능성과 규제 상황
제8장 고객 상황과 구매 행동
제9장 데이터센터용 칠러 시장 : 제품 유형별
제10장 데이터센터용 칠러 시장 : 콘덴서 유형별
제11장 데이터센터용 칠러 시장 : 냉각 능력별
제12장 데이터센터용 칠러 시장 : 지역별
제13장 경쟁 구도
제14장 기업 개요
제15장 조사 방법
제16장 부록
KSM 26.09.17The global data center chillers market is projected to grow from USD 1.67 billion in 2026 to USD 2.81 billion in 2032, at a CAGR of 9.0% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2018-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | Value (USD Million) |
| Segments | By Product, Technology, Cooling Capacity, and Region |
| Regions covered | North America, Asia Pacific, Europe, South America, and the Middle East & Africa |
Data center chillers are essential infrastructure systems that enable data centers to maintain controlled operating environments by efficiently removing excess heat produced during continuous computing operations. As data centers handle increasing volumes of digital traffic and process more complex workloads, effective cooling has become a critical requirement for ensuring equipment longevity, system stability, and uninterrupted service availability. Chiller systems help balance thermal loads while supporting optimal energy management across facilities of varying sizes. The growth of the data center chillers market is being fueled by the rising adoption of cloud-based applications, digital storage services, enterprise data processing, and connected technologies that require robust computing infrastructure. Additionally, increasing investments in hyperscale facilities, the expansion of edge computing networks, and the growing need for energy-efficient data center operations are driving demand for advanced cooling solutions. As organizations continue to prioritize performance, scalability, and sustainability in their digital infrastructure strategies, the adoption of data center chillers is expected to increase steadily across the industry.
"By product, the air-cooled chillers segment is expected to account for the second-largest share during the forecast period."
The air-cooled chillers segment is expected to hold the second-largest share of the data center chillers market due to its relatively simple installation requirements, lower upfront infrastructure costs, and suitability for a wide range of data center applications. Unlike water-cooled systems, air-cooled chillers do not require cooling towers or extensive water management infrastructure, making them particularly attractive for facilities seeking faster deployment and reduced operational complexity. Their ability to provide reliable cooling performance while minimizing water consumption has become increasingly important as data center operators focus on sustainability and resource efficiency. Additionally, the growing expansion of edge data centers, modular data centers, and small- to medium-sized facilities is supporting the adoption of air-cooled chillers, as these installations often prioritize flexibility, ease of maintenance, and lower installation footprints. Continuous advancements in energy-efficient designs and control technologies are further enhancing their performance and operational effectiveness. As data center investments continue to expand globally, the widespread applicability and cost-effective cooling capabilities of air-cooled chillers are expected to sustain their strong market presence and contribute significantly to the growth of the data center chillers market.
"By technology, the centrifugal chillers segment is expected to account for the second-largest market share during the forecast period."
The centrifugal chillers segment is expected to hold the second-largest share of the data center chillers market owing to its widespread use in large-scale and hyperscale data center facilities that require substantial cooling capacities and high operational efficiency. These chillers are particularly well-suited for managing the significant heat loads generated by dense server environments, making them a preferred choice for large data centers handling cloud computing, artificial intelligence, and high-performance computing workloads. Their ability to deliver efficient cooling at scale while maintaining lower energy consumption per unit of cooling capacity supports efforts to improve overall facility efficiency and reduce operating costs. In addition, the ongoing expansion of hyperscale data centers and the increasing focus on optimizing power usage effectiveness (PUE) are driving investments in centrifugal chiller systems. Continuous technological advancements, including improved compressor designs, variable-speed drives, and smart monitoring capabilities, are further enhancing their performance and reliability. As demand for large-capacity cooling infrastructure continues to grow, centrifugal chillers are expected to maintain a significant market position and contribute substantially to the expansion of the data center chillers market.
"Europe to account for second-largest market share during forecast period"
Europe is expected to hold the second-largest share of the data center chillers market due to its well-established digital infrastructure, strong presence of colocation and hyperscale data centers, and continuous investments in cloud computing and enterprise data management. The region is witnessing increasing demand for data processing and storage services driven by digital transformation initiatives across industries such as finance, healthcare, manufacturing, telecommunications, and government services. Additionally, stringent energy efficiency regulations and sustainability objectives are encouraging data center operators to adopt advanced cooling technologies that reduce energy consumption while maintaining reliable performance. The growing deployment of artificial intelligence applications, edge computing facilities, and high-performance computing infrastructure is further increasing the need for efficient thermal management solutions across the region. Furthermore, modernization of existing data centers and the construction of new facilities to support rising digital workloads are contributing to sustained demand for chiller systems. As operators continue to focus on operational efficiency, environmental compliance, and infrastructure resilience, Europe is expected to maintain a significant share of the data center chillers market.
Profile break-up of primary participants for the report:
- By Company Type: Tier 1 - 65%, Tier 2 - 20%, and Tier 3 - 15%
- By Designation: Directors - 25%, Managers - 30%, and Others - 45%
- By Region: North America - 30%, Asia Pacific - 40%, Europe - 20%, Middle East & Africa - 7%, and South America - 3%
Johnson Controls (Ireland), Trane Technologies (Ireland), Carrier (US), Daikin (Japan), and Vertiv Group Corp. (US) are some of the major players operating in the data center chillers market.
Research Coverage:
The report segments the data center chillers market based on product, technology, cooling capacity, and region. It provides detailed information regarding the major factors influencing the market's growth, such as drivers, restraints, opportunities, and challenges. It strategically profiles data center chillers manufacturers, comprehensively analyzing their market shares and core competencies.
Reasons to Buy the Report:
The report is expected to help the market leaders/new entrants by providing them with the closest approximations of revenue numbers of the data center chillers market and its segments. This report is also expected to help stakeholders obtain an improved understanding of the market's competitive landscape, gain insights to improve the position of their businesses, and make suitable go-to-market strategies. It also enables stakeholders to understand the market's pulse and provides information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following pointers:
- Analysis of critical DROCs: Drivers (Rising demand for energy-efficient centralized cooling driven by stringent PUE targets and AI-era power densities; Rapid expansion of hyperscale and cloud data centers driving high-capacity chiller deployments; Surging heat loads from AI, GPU clusters, and high-performance computing demanding high-capacity thermal management; and Tightening energy efficiency regulations and sustainability mandates pushing adoption of advanced chiller systems with low-GWP refrigerants), restraints (High upfront capital expenditure for advanced chiller systems; and complexity and cost of retrofitting legacy data centers with modern chiller infrastructure, including cooling towers, condenser water loops, and piping systems), opportunities (Growing adoption of liquid coolant and direct-to-chip cooling creating demand for specialized liquid coolant chiller systems integrated with data center infrastructure; Growing demand for modular and prefabricated chiller plants enabling faster deployment and scalable capacity expansion for edge and hyperscale data centers; and Advancement of AI-driven and IoT-enabled chiller management systems improving predictive maintenance, load optimization, and energy efficiency), and challenges (Ensuring chiller system redundancy and resilience to meet Tier III/IV uptime requirements and avoid single points of failure in mission-critical environments; Pressure to transition to low-GWP and natural refrigerants while managing phase-out of legacy HFC-based chiller fleets without disrupting operations; and Managing rising water scarcity concerns for water-cooled chiller deployments, driving operational and regulatory risk especially in water-stressed geographies)
- Product Development/Innovation: Detailed insights on upcoming technologies and research & development activities in the data center chillers market
- Market Development: Comprehensive information about lucrative markets - the report analyzes the data center chillers market across varied regions.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and product offerings of leading players such as Johnson Controls (Ireland), Trane Technologies (Ireland), Carrier (US), Daikin (Japan), and Vertiv Group Corp. (US) in the data center chillers market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.4 INCLUSIONS AND EXCLUSIONS
- 1.4.1 YEARS CONSIDERED
- 1.4.2 CURRENCY CONSIDERED
- 1.5 STAKEHOLDERS
- 1.6 RESEARCH LIMITATIONS
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN DATA CENTER CHILLERS MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN DATA CENTER CHILLERS MARKET
- 3.2 DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE
- 3.3 DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE
- 3.4 DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY
- 3.5 DATA CENTER CHILLERS MARKET, BY REGION
- 3.6 DATA CENTER CHILLERS MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising AI and high-performance computing workloads
- 4.2.1.2 Growing focus on energy efficiency and lower PUE
- 4.2.1.3 Increasing adoption of reliable and redundant liquid cooling infrastructure
- 4.2.2 RESTRAINTS
- 4.2.2.1 High capital and installation costs
- 4.2.2.2 High water consumption of water-cooled chiller systems
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Integration of chillers with AI-ready liquid-cooling architecture
- 4.2.3.2 Development of low-GWP and ultra-low-GWP chillers
- 4.2.3.3 Smart and AI-enabled chiller optimization
- 4.2.4 CHALLENGES
- 4.2.4.1 Transition from conventional air cooling to hybrid cooling architectures
- 4.2.4.2 Refrigerant regulations and technology transition
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN DATA CENTER CHILLERS MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 EMERGING BUSINESS MODELS AND ECOSYSTEM SHIFTS
- 4.5.1 EMERGING BUSINESS MODELS
- 4.5.2 ECOSYSTEM SHIFTS
- 4.6 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.6.1 KEY MOVES AND STRATEGIC FOCUS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 BARGAINING POWER OF SUPPLIERS
- 5.1.2 THREAT OF NEW ENTRANTS
- 5.1.3 THREAT OF SUBSTITUTES
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 GLOBAL MACROECONOMIC OUTLOOK
- 5.2.1 GDP TRENDS
- 5.2.2 TRENDS IN GLOBAL ARTIFICIAL INTELLIGENCE INDUSTRY
- 5.3 VALUE CHAIN ANALYSIS
- 5.3.1 DATA CENTER CHILLERS VALUE CHAIN COMPRISES THE FOLLOWING STAGES:
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.6 TRENDS AND DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.7 INVESTMENT AND FUNDING SCENARIO
- 5.8 CASE STUDY ANALYSIS
- 5.8.1 CARRIER: INNOVATIVE HVAC SOLUTION TURNS DATA CENTERS INTO DISTRICT HEATING SOURCES
- 5.8.2 DANFOSS: 1,400-TON CHILLERS IMPROVE EFFICIENCY AND LOWER COSTS
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 SCREW CHILLERS
- 6.1.2 CENTRIFUGAL CHILLERS
- 6.1.3 SCROLL CHILLERS
- 6.2 ADJACENT TECHNOLOGIES
- 6.2.1 COOLING TOWERS
- 6.2.2 DRY COOLERS/FLUID COOLERS
- 6.3 COMPLEMENTARY TECHNOLOGIES
- 6.3.1 CHILLER PLANT CONTROLS
- 6.3.2 BUILDING MANAGEMENT SYSTEM (BMS)
- 6.4 PATENT ANALYSIS
- 6.4.1 INTRODUCTION
- 6.4.2 METHODOLOGY
- 6.4.3 DOCUMENT TYPE
- 6.4.4 INSIGHTS
- 6.4.5 LEGAL STATUS OF PATENTS
- 6.4.6 JURISDICTION ANALYSIS
- 6.4.7 TOP APPLICANTS
- 6.4.8 MAJOR PATENTS
- 6.5 FUTURE APPLICATIONS
- 6.5.1 AI-DRIVEN ADAPTIVE CHILLER CONTROL: REAL-TIME TEMPERATURE-BASED CONTROLS DYNAMICALLY ADJUST CHILLER AND AC OPERATION FOR HIGHER EFFICIENCY AND THERMAL ACCURACY
- 6.5.2 MODULAR & SCALABLE CHILLER ARCHITECTURES: PLUG-AND-PLAY COOLING MODULES ENABLE INCREMENTAL CAPACITY EXPANSION WITHOUT MAJOR INFRASTRUCTURE CHANGES
- 6.5.3 CASCADE & HYBRID MULTI-CHILLER SYSTEMS: HYBRID SYSTEMS OPTIMIZE PART-LOAD EFFICIENCY BY SWITCHING BETWEEN FREE COOLING AND MECHANICAL CHILLING BASED ON OUTDOOR TEMPERATURE
- 6.5.4 THERMAL STORAGE & EMERGENCY RESILIENCE SYSTEMS: BUFFER TANKS AND BACKUP CHILLERS ENSURE CONTINUOUS COOLING DURING OUTAGES AND DEMAND SPIKES
- 6.5.5 PRE-COOLING & IN-ROW DISTRIBUTED COOLING: PRE-COOLING CHILLERS WITH IN-ROW ACS ENABLE EFFICIENT, LOCALIZED COOLING FOR HIGH-DENSITY RACKS
- 6.6 IMPACT OF AI ON DATA CENTER CHILLERS MARKET
- 6.6.1 TOP USE CASES AND MARKET POTENTIAL
- 6.6.2 BEST PRACTICES: COMPANIES/INSTITUTIONS USE CASES
- 6.6.3 CASE STUDIES OF DATA CENTER CHILLERS MARKET
- 6.6.4 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.6.5 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN DATA CENTER CHILLERS MARKET
- 6.6.5.1 Trane: 9,600 RT integrated chiller plant in Beijing, China
- 6.6.5.2 Carrier: Iron Mountain data center, Pennsylvania, US
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.1 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 CARBON IMPACT AND ECO APPLICATIONS OF DATA CENTER CHILLERS
- 7.3 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 7.4 CERTIFICATIONS, LABELLING, AND ECO STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOUR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS AND BUYING CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS IN VARIOUS DATA CENTER TYPES
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES IN KEY DATA CENTER TYPES
9 DATA CENTER CHILLERS MARKET, BY PRODUCT TYPE
- 9.1 INTRODUCTION
- 9.2 SCROLL CHILLERS
- 9.2.1 RISING DEPLOYMENT OF EDGE, ENTERPRISE, AND DISTRIBUTED DATA CENTERS FUELING DEMAND
- 9.3 SCREW CHILLERS
- 9.3.1 INCREASING MEDIUM-TO-HIGH RACK DENSITIES AND ADOPTION OF HYBRID AIR/LIQUID COOLING DRIVING DEMAND FOR FLEXIBLE SCREW CHILLERS
- 9.4 CENTRIFUGAL CHILLERS
- 9.4.1 RAPID EXPANSION OF HYPERSCALE AND AI DATA CENTERS WITH MULTI-MEGAWATT COOLING REQUIREMENTS TO FUEL GROWTH
10 DATA CENTER CHILLERS MARKET, BY CONDENSER TYPE
- 10.1 INTRODUCTION
- 10.2 AIR-COOLED CHILLERS
- 10.2.1 GROWING DATA CENTER DEPLOYMENT IN WATER-STRESSED REGIONS DRIVING DEMAND FOR AIR-COOLED
- 10.3 WATER-COOLED CHILLERS
- 10.3.1 RAPID EXPANSION OF HYPERSCALE AND AI DATA CENTERS WITH MULTI-MEGAWATT COOLING LOADS DRIVING DEMAND
11 DATA CENTER CHILLERS MARKET, BY COOLING CAPACITY
- 11.1 INTRODUCTION
- 11.2 BELOW 150 RT
- 11.2.1 EXPANSION OF EDGE, MICRO, TELECOM, AND SMALL ENTERPRISE DATA CENTERS DRIVING DEMAND FOR COMPACT AND MODULAR CHILLERS
- 11.3 150-700 RT
- 11.3.1 GROWING COLOCATION AND ENTERPRISE DATA CENTERS WITH RISING RACK DENSITIES DRIVING DEMAND FOR MEDIUM-CAPACITY CHILLERS
- 11.4 700-3,000 RT
- 11.4.1 INCREASING DEVELOPMENT OF LARGE HYPERSCALE, CLOUD, AND AI DATA CENTERS FUELING MARKET GROWTH
- 11.5 ABOVE 3,000 RT
- 11.5.1 RAPID SCALING OF HYPERSCALE AND AI DATA CENTER CAMPUSES DRIVING DEMAND FOR ULTRA-HIGH-CAPACITY CENTRIFUGAL CHILLER SYSTEMS
12 DATA CENTER CHILLERS MARKET, BY REGION
- 12.1 INTRODUCTION
- 12.2 NORTH AMERICA
- 12.2.1 US
- 12.2.1.1 AI/HPC expansion, hyperscale campuses, high rack power density, cloud investment, and replacement of legacy chillers boosting demand
- 12.2.2 CANADA
- 12.2.3 GROWING AI-COMPUTE TO SUPPORT MARKET GROWTH
- 12.2.4 MEXICO
- 12.2.4.1 Nearshoring, cloud and colocation growth, proximity to US digital infrastructure, and industrial digitalization driving growth
- 12.2.1 US
- 12.3 EUROPE
- 12.3.1 GERMANY
- 12.3.2 FRANKFURT'S EXPANDING HYPERSCALE & COLOCATION MARKET, WASTE-HEAT RECOVERY REQUIREMENTS, AND GROWING AI WORKLOADS DRIVING MARKET GROWTH
- 12.3.3 UK
- 12.3.3.1 AI adoption and Critical National Infrastructure status fueling demand for data center chillers
- 12.3.4 FRANCE
- 12.3.4.1 Growing AI infrastructure fueling market growth
- 12.3.5 ITALY
- 12.3.5.1 Milan data center expansion and increasing cloud adoption to drive market
- 12.3.6 SPAIN
- 12.3.6.1 Madrid's hyperscale growth fueling market expansion
- 12.3.7 RUSSIA
- 12.3.7.1 Rising demand for modular and locally serviceable cooling systems to increase adoption
- 12.3.8 REST OF EUROPE
- 12.4 ASIA PACIFIC
- 12.4.1 CHINA
- 12.4.1.1 Adoption of AI strategy and hyperscale/cloud expansion creating demand
- 12.4.2 INDIA
- 12.4.2.1 Growing AI infrastructure and hyperscale expansion & cloud adoption driving demand
- 12.4.3 JAPAN
- 12.4.3.1 Data center concentration due to land scarcity, energy costs, and advanced automation fueling demand
- 12.4.4 SOUTH KOREA
- 12.4.4.1 Semiconductor & AI ecosystem for hyperscale development supporting market growth
- 12.4.5 MALAYSIA
- 12.4.5.1 Rapid data center expansion driving demand for chiller systems
- 12.4.6 THAILAND
- 12.4.6.1 Growing data center hub in Bangkok and Eastern Economic Corridors fueling demand
- 12.4.7 INDONESIA
- 12.4.7.1 Growing digital economy, cloud adoption, and data-localization requirements to drive market
- 12.4.8 REST OF ASIA PACIFIC
- 12.4.1 CHINA
- 12.5 MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.5.1.1 UAE
- 12.5.1.1.1 G42/Microsoft investment, Stargate AI infrastructure, and extreme temperatures to drive market
- 12.5.1.2 Saudi Arabia
- 12.5.1.2.1 Vision 2030, adoption of sovereign AI, and hyperscale investment to support market growth
- 12.5.1.3 Rest of GCC countries
- 12.5.1.1 UAE
- 12.5.2 SOUTH AFRICA
- 12.5.2.1 Established colocation market, cloud adoption, and energy-efficiency requirements to fuel market
- 12.5.3 REST OF MIDDLE EAST & AFRICA
- 12.5.1 GCC COUNTRIES
- 12.6 SOUTH AMERICA
- 12.6.1 BRAZIL
- 12.6.1.1 Sao Paulo hyperscale growth, AI infrastructure, and cloud adoption fueling demand
- 12.6.2 CHILE
- 12.6.2.1 Strong submarine connectivity and Santiago's emergence as a regional data center hub to support growth
- 12.6.3 REST OF SOUTH AMERICA
- 12.6.1 BRAZIL
13 COMPETITIVE LANDSCAPE
- 13.1 INTRODUCTION
- 13.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN
- 13.3 REVENUE ANALYSIS
- 13.3.1 TOP PLAYERS' REVENUE ANALYSIS
- 13.4 MARKET SHARE ANALYSIS, 2025
- 13.4.1 RANKING ANALYSIS OF KEY MARKET PLAYERS
- 13.4.2 MARKET SHARE ANALYSIS, 2025
- 13.5 BRAND/PRODUCT COMPARISON
- 13.5.1 STULZ
- 13.5.2 VERTIV
- 13.5.3 TRANE
- 13.5.4 MUNTERS
- 13.5.5 DAIKIN
- 13.6 COMPANY VALUATION AND FINANCIAL METRICS
- 13.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 13.7.1 STARS
- 13.7.2 EMERGING LEADERS
- 13.7.3 PERVASIVE PLAYERS
- 13.7.4 PARTICIPANTS
- 13.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 13.7.5.1 Company footprint
- 13.7.6 REGION FOOTPRINT
- 13.7.7 CONDENSER TYPE FOOTPRINT
- 13.7.8 COOLING CAPACITY FOOTPRINT
- 13.7.9 PRODUCT TYPE FOOTPRINT
- 13.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 13.8.1 PROGRESSIVE COMPANIES
- 13.8.2 RESPONSIVE COMPANIES
- 13.8.3 DYNAMIC COMPANIES
- 13.8.4 STARTING BLOCKS
- 13.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 13.8.5.1 Detailed list of key startups/SMEs
- 13.8.6 COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- 13.9 COMPETITIVE SCENARIO
- 13.9.1 PRODUCT LAUNCHES
- 13.9.2 DEALS
14 COMPANY PROFILE
- 14.1 KEY PLAYERS
- 14.1.1 JOHNSON CONTROLS
- 14.1.1.1 Business overview
- 14.1.1.2 Products/Solutions/Services offered
- 14.1.1.3 Recent developments
- 14.1.1.3.1 Product launches
- 14.1.1.4 MnM view
- 14.1.1.4.1 Key strengths
- 14.1.1.4.2 Strategic choices
- 14.1.1.4.3 Weaknesses and competitive threats
- 14.1.2 TRANE
- 14.1.2.1 Business overview
- 14.1.2.2 Products/Solutions/Services offered
- 14.1.2.3 Recent developments
- 14.1.2.3.1 Product launches
- 14.1.2.3.2 Deals
- 14.1.2.4 MnM view
- 14.1.2.4.1 Key strengths
- 14.1.2.4.2 Strategic choices
- 14.1.2.4.3 Weaknesses and competitive threats
- 14.1.3 CARRIER
- 14.1.3.1 Business overview
- 14.1.3.2 Products/Solutions/Services offered
- 14.1.3.3 Recent developments
- 14.1.3.3.1 Product launches
- 14.1.3.3.2 Deals
- 14.1.3.4 MnM view
- 14.1.3.4.1 Key strengths
- 14.1.3.4.2 Strategic choices
- 14.1.3.4.3 Weaknesses and competitive threats
- 14.1.4 DAIKIN APPLIED
- 14.1.4.1 Business overview
- 14.1.4.2 Products/Solutions/Services offered
- 14.1.4.3 Recent developments
- 14.1.4.3.1 Product launches
- 14.1.4.3.2 Deals
- 14.1.4.3.3 Expansions
- 14.1.4.4 MnM view
- 14.1.4.4.1 Key strengths
- 14.1.4.4.2 Strategic choices
- 14.1.4.4.3 Weaknesses and competitive threats
- 14.1.5 VERTIV GROUP CORP.
- 14.1.5.1 Business overview
- 14.1.5.2 Products/Solutions/Services offered
- 14.1.5.3 Recent developments
- 14.1.5.3.1 Product launches
- 14.1.5.3.2 Deals
- 14.1.5.3.3 Expansions
- 14.1.5.4 MnM view
- 14.1.5.4.1 Key strengths
- 14.1.5.4.2 Strategic choices
- 14.1.5.4.3 Weaknesses and competitive threats
- 14.1.6 MODINE
- 14.1.6.1 Business overview
- 14.1.6.2 Products/Solutions/Services offered
- 14.1.6.3 Recent developments
- 14.1.6.3.1 Product launches
- 14.1.6.3.2 Deals
- 14.1.6.3.3 Expansions
- 14.1.7 SCHNEIDER ELECTRIC
- 14.1.7.1 Business overview
- 14.1.7.2 Products/Solutions/Services offered
- 14.1.7.3 Recent developments
- 14.1.7.3.1 Product launches
- 14.1.7.3.2 Deals
- 14.1.8 MUNTERS
- 14.1.8.1 Business overview
- 14.1.8.2 Products/Solutions/Services offered
- 14.1.9 MITSUBISHI ELECTRIC CORPORATION
- 14.1.9.1 Business overview
- 14.1.9.2 Products/Solutions/Services offered
- 14.1.9.3 Recent developments
- 14.1.9.3.1 Product launches
- 14.1.9.3.2 Expansions
- 14.1.10 LENNOX INTERNATIONAL INC.
- 14.1.10.1 Business overview
- 14.1.10.2 Products/Solutions/Services offered
- 14.1.11 DANFOSS
- 14.1.11.1 Business overview
- 14.1.11.2 Products/Solutions/Services offered
- 14.1.12 STULZ GMBH
- 14.1.12.1 Business overview
- 14.1.12.2 Products/Solutions/Services offered
- 14.1.13 GEA GROUP AKTIENGESELLSCHAFT
- 14.1.13.1 Business overview
- 14.1.13.2 Products/Solutions/Services offered
- 14.1.14 RITTAL GMBH & CO. KG
- 14.1.14.1 Business overview
- 14.1.14.2 Products/Solutions/Services offered
- 14.1.15 BLUE STAR LIMITED
- 14.1.15.1 Business overview
- 14.1.15.2 Products/Solutions/Services offered
- 14.1.16 KIRLOSKAR CHILLERS PRIVATE LIMITED
- 14.1.16.1 Business overview
- 14.1.16.2 Products/Solutions/Services offered
- 14.1.17 LG ELECTRONICS
- 14.1.17.1 Business overview
- 14.1.17.2 Products/Solutions/Services offered
- 14.1.17.3 Recent developments
- 14.1.17.3.1 Deals
- 14.1.18 PANASONIC HOLDINGS CORPORATION
- 14.1.18.1 Business overview
- 14.1.18.2 Products/Solutions/Services offered
- 14.1.18.3 Recent developments
- 14.1.18.3.1 Expansions
- 14.1.19 THERMAL CARE
- 14.1.19.1 Business overview
- 14.1.19.2 Products/Solutions/Services offered
- 14.1.20 GD MIDEA HEATING & VENTILATING EQUIPMENT CO., LTD.
- 14.1.20.1 Business overview
- 14.1.20.2 Products/Solutions/Services offered
- 14.1.20.3 Recent developments
- 14.1.20.3.1 Product launches
- 14.1.21 DELTA ELECTRONICS, INC.
- 14.1.21.1 Business overview
- 14.1.21.2 Products/Solutions/Services offered
- 14.1.22 THERMAX LIMITED
- 14.1.22.1 Business overview
- 14.1.22.2 Products/Solutions/Services offered
- 14.1.1 JOHNSON CONTROLS
- 14.2 OTHER PLAYERS
- 14.2.1 MULTISTACK
- 14.2.2 AERMEC S.P.A.
- 14.2.3 VOLTAS LIMITED
15 RESEARCH METHODOLOGY
- 15.1 RESEARCH DATA
- 15.1.1 SECONDARY DATA
- 15.1.1.1 List of key secondary sources
- 15.1.2 PRIMARY DATA
- 15.1.2.1 List of participating companies for primary research
- 15.1.1 SECONDARY DATA
- 15.2 MARKET SIZE ESTIMATION
- 15.2.1 TOP-DOWN APPROACH
- 15.2.2 BOTTOM-UP APPROACH
- 15.3 MARKET FORECAST APPROACH
- 15.3.1 DEMAND-SIDE ANALYSIS
- 15.3.2 SUPPLY-SIDE ANALYSIS
- 15.3.3 CALCULATION FOR SUPPLY-SIDE ANALYSIS
- 15.4 GROWTH FORECAST
- 15.5 DATA TRIANGULATION
- 15.6 FACTOR ANALYSIS
16 APPENDIX
- 16.1 DISCUSSION GUIDE
- 16.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 16.3 CUSTOMIZATION OPTIONS
- 16.4 RELATED REPORTS
- 16.5 AUTHOR DETAILS