|
시장보고서
상품코드
2100674
인도의 코워킹 오피스 시장 : 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)India Coworking Office Spaces - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
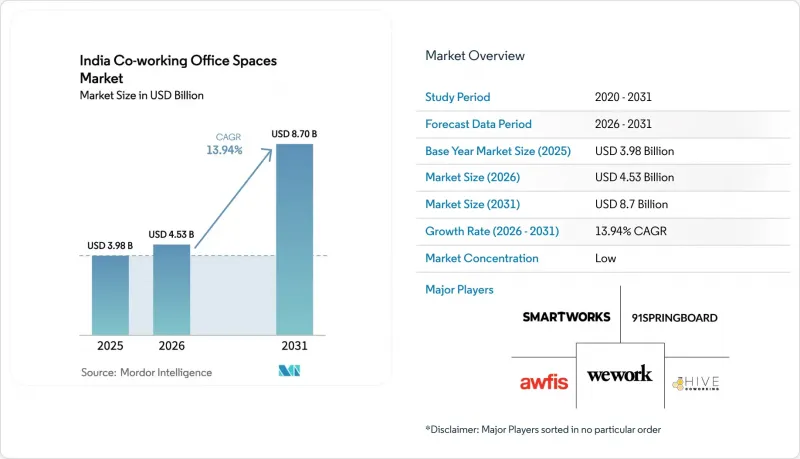
에 의하면, 2026년 인도 코워킹 오피스 시장 규모는 45억 3,000만 달러로 추정되고 있어 2025년 39억 8,000만 달러에서 확대해, 2031년에는 87억 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 13.94%가 될 것으로 전망됩니다.
본 보고서는 시설 규모(소규모, 중규모, 대규모), 업종(IT 및 ITES, 은행, 금융서비스 및 보험(BFSI), 비즈니스 컨설팅·전문 서비스, 기타 서비스), 최종 용도(프리랜서, 기업, 스타트업, 기타), 도시(뭄바이, 델리 NCR, 푸네, 벵갈루루, 하이데라바드, 첸나이, 콜카타, 아메다바드 및 인도의 기타 지역)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
인도 코워킹 오피스 시장 동향 및 인사이트
스타트업 및 중소기업의 급속한 성장이 비용 효율적인 코워킹 스페이스에 대한 수요를 견인하고 있습니다.
인도에서는 2030년까지 20만 개 이상의 스타트업이 탄생할 것으로 예상되며, 이는 현재 수치의 2.6배에 해당합니다. 또한, 현재 등록된 11만 5,000개의 스타트업 중 약 절반이 2급 및 3급 도시에 거점을 두고 있습니다. 이러한 신생 기업들은 기존 사무실에서는 50만 루피를 초과하기도 하는 보증금을 피하기 위해,월3,000-8,000 루피의 유연한 좌석을 제공하는 코워킹 스페이스를 선호하고 있습니다. '스타트업 인디아 시드 펀드'(945카롤 루피)와 같은 정부 프로그램을 통해 창업자들은 공유 업무 공간을 거점으로 하는 인큐베이터로 유도되고 있습니다. 2023년 중반 이후 주요 도시의 상업용 임대료는 30-50% 상승했으며, 이로 인해 중소기업들은 더욱 유연한 솔루션으로 눈을 돌리고 있습니다. 기존 사무실의 비용 곡선이 코워킹 요금보다 훨씬 가파르게 상승하고 있기 때문에 인도의 코워킹 오피스 시장은 자연스러운 성장에 힘입어 고객 기반을 지속적으로 확대되고 있습니다.
방갈로르, 하이데라바드, 구르가온의 IT, 전자상거래, 전문 서비스 기업들의 적극적인 도입
2023 회계연도(FY23)의 기업용 코워킹 거래는 103,665석을 기록했으며, 그중 IT·BPM 분야가 거래의 40%를 차지하여 전년 대비 20% 성장을 달성했습니다. 방갈로르, 하이데라바드, 푸네 3개 도시가 기업용 임대 시장의 78%를 차지하고 있으며, 유연한 사무실 수요는 지난 5년간 연평균 성장률(CAGR) 41%를 유지하고 있습니다. 항공사나 시멘트 업계와 같은 기존 분야도 이러한 추세에 동참하며 그 확산을 뒷받침하고 있습니다. 현재 인도 구인 공고의 약 20%에 하이브리드 근무 형태가 명시되어 있으며, 이에 따라 전문 서비스 기업들은 코워킹 허브를 통해 고객사 근처에 팀을 배치하고 있습니다. 따라서 인도의 코워킹 오피스 공간 시장은 기술 및 컨설팅 기업 임차인을 핵심으로 하는 대규모 좌석 수요의 안정적인 파이프라인으로부터 혜택을 받고 있습니다.
주요 대도시권에서의 치열한 경쟁과 공급 과잉의 위험이 가격 면에서 압박을 가하고 있습니다.
주요 도시에는 500개 이상의 사업자가 밀집해 있어 가격 경쟁이 극도로 치열해지고 있습니다. 뭄바이의 임대료는 2020년도 이후 27% 상승했으나, 점유율 하락으로 인해 할인을 할 수밖에 없는 상황입니다. 방갈로르에서는 공실률이 극히 낮은 수준이지만, 운영 비용이 전년 대비 30-50% 상승했음에도 불구하고 신규 진입 업체들로 인해 가격 결정력이 약화되고 있습니다. 규모가 작아 이익률 압박에 직면한 중소기업들은 업계 재편의 물결이나 선택적 철수를 피할 수 없는 상황에 놓여 있습니다. 공급 과잉에 대한 우려가 인도 코워킹 오피스 시장의 단기적인 회복을 저해할 가능성이 있습니다.
부문 분석
2025년 매출액 중 대규모 시설이 52.65%를 차지했습니다. 이는 전용 회의실이나 첨단 기술 서비스를 제공하는 단일 거점 캠퍼스를 원하는 기업 수요를 반영한 것입니다. 운영 사업자는 높은 좌석 밀도와 부가 서비스를 통해 규모의 경제를 활용하여 수익화를 도모하고 있으며, 경쟁이 있음에도 불구하고 가동률을 85% 이상으로 유지하고 있습니다. 한편, 중규모 시설은 중견 기업이나 프로젝트 팀이 대도시권의 높은 임대료를 지불하지 않고도 전문적인 설비를 이용하고자 하는 수요에 힘입어, 2031년까지 연평균 성장률(CAGR) 14.62%로 가장 빠르게 성장하고 있습니다. 이 부문은 대개 12-24개월 계약을 체결하기 때문에 운영사의 현금 흐름 전망이 개선됩니다.
소규모 센터는 프리랜서나 창업 초기 스타트업에게 여전히 중요한 존재이지만, 좌석당 비용이 높고 제공할 수 있는 서비스의 폭이 제한적이라는 과제에 직면해 있습니다. 기술 투자도 대규모 시설에 편중되어 있습니다. IoT 센서, 비접촉식 출입 시스템, 이용 현황 분석은 캠퍼스 규모의 시설에서는 표준 사양으로 자리 잡았지만, 많은 소규모 허브에서는 여전히 수작업에 의존하고 있습니다. 기업 대상 계약이 대형 제공업체에 집중됨에 따라, 인도의 코워킹 오피스 시장에서는 추가적인 통합이 진행될 것으로 예상되며, 여러 도시에서 대규모 확장이 가능한 운영 사업자가 유리한 입지를 차지할 것으로 전망됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.08.11According to Mordor Intelligence, India co-working office space market size in 2026 is estimated at USD 4.53 billion, growing from 2025 value of USD 3.98 billion with 2031 projections showing USD 8.7 billion, growing at 13.94% CAGR over 2026-2031.
This report is Segmented by Size & Scale of Facility (Small, Medium, and Large), by Sector (IT and ITES, BFSI, Business Consulting & Professional Service, and Other Services), by End Use (Freelancers, Enterprises, Start Ups, and Others), by City (Mumbai, Delhi NCR, Pune, Bengaluru, Hyderabad, Chennai, Kolkata, Ahmedabad and Rest of India). The Market Forecasts are Provided in Terms of Value (USD).
India Coworking Office Spaces Market Trends and Insights
Rapid growth of start-ups and SMEs is driving demand for cost-effective co-working spaces
India is expected to host more than 200,000 start-ups by 2030, a 2.6-fold jump on current numbers, and roughly half of today's 115,000 registered start-ups sit in tier-2 and tier-3 cities. These young firms favor co-working to avoid deposits that can top INR 500,000 for conventional offices, given flex seats cost INR 3,000-8,000 per month. Government programs such as the Startup India Seed Fund (INR 945 crore) are funneling founders toward incubators that operate from shared workspaces. Commercial rents have risen 30-50% in major cities since mid-2023, further tilting SMEs toward flexible solutions. As the traditional office cost curve steepens faster than co-working tariffs, the India co-working office space market continues to widen its customer base organically.
Strong adoption by IT, e-commerce, and professional services firms in Bengaluru, Hyderabad, and Gurugram
Enterprise co-working transactions booked 103,665 seats in FY23, with IT-BPM accounting for 40% of deals and achieving 20% year-on-year growth. Bengaluru, Hyderabad, and Pune together form 78% of enterprise leases, sustaining a five-year 41% CAGR in flex demand. Traditional sectors such as airlines and cement have joined the trend, underscoring its breadth. About 20% of Indian job listings now specify hybrid formats, prompting professional-services firms to situate teams close to clients via co-working hubs. The India co-working office space market, therefore, benefits from a steady pipeline of large-seat requirements anchored by technology and consulting tenants.
High competition and oversupply risk in top metros are leading to pricing pressures
With more than 500 operators crowding metros, price tension is acute. Mumbai rents have climbed 27% since FY20, yet occupancy pressure forces discounting. Bengaluru's vacancy is scarce, but newcomers erode pricing power even as operating costs inflate 30-50% year-on-year. Smaller firms lacking scale risk margin compression, prompting consolidation waves and selective exits. The oversupply overhang is likely to restrain near-term uplift in the India co-working office space market.
Other drivers and restraints analyzed in the detailed report include:
- Hybrid work models are increasing the preference for flexible and short-term leasing options
- Investor and developer partnerships are expanding Grade A co-working supply in metro cities
- Limited penetration in tier-2 and tier-3 cities despite rising demand potential
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Large facilities accounted for 52.65% of 2025 revenue, reflecting enterprise appetite for single-location campuses that deliver dedicated meeting suites and advanced tech services. Operators monetize at scale through higher seat density and ancillary services, keeping utilization above 85% despite price competition. Meanwhile, medium facilities are growing fastest at a 14.62% CAGR through 2031 as mid-market firms and project teams want professional amenities without premium metro rents. This cohort often signs 12- to 24-month commitments that improve operators' cash-flow visibility.
Smaller centers remain relevant for freelancers and early-stage start-ups but face higher per-seat costs and limited service breadth. Technology investment also tilts toward larger footprints; IoT sensors, touch-free entry, and usage analytics are standard in campus-scale assets, whereas many small hubs still rely on manual processes. As enterprise contracts concentrate volume with top providers, the India co-working office space market is expected to witness further consolidation, favoring operators capable of multi-city, large-format delivery.
Complete Report Scope:
- By Size & Scale of Facility
- Small
- Medium
- Large
- By Sector
- Information Technology (IT and ITES)
- BFSI (Banking, Financial Services and Insurance)
- Business Consulting & Professional Service
- Other Services (Retail, Lifesciences, Energy, Legal Services)
- By End Use
- Freelancers
- Enterprises
- Start Ups and Others
- By City
- Mumbai Metropolitan Region
- Delhi NCR
- Pune
- Bengaluru
- Hyderabad
- Chennai
- Kolkata
- Ahmedabad
- Rest of India
List of Companies Covered in this Report:
- WeWork India
- Awfis
- Smartworks
- 91Springboard
- CoWrks
- BHIVE Workspaces
- The Office Pass
- 315Work Avenue
- Innov8
- IndiQube
- Skootr
- GoodWorks Coworking
- Spring House Coworking
- Urban Vault
- Workafella
- Regus India
- Incuspaze
- The Executive Centre
- The Hive*
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid growth of start-ups and SMEs driving demand for cost-effective co-working spaces
- 4.2.2 Strong adoption by IT, e-commerce, and professional services firms in Bengaluru, Hyderabad, and Gurugram
- 4.2.3 Hybrid work models increasing preference for flexible and short-term leasing options
- 4.2.4 Investor and developer partnerships expanding Grade A co-working supply in metro cities
- 4.2.5 Rising demand for wellness-focused and sustainability-certified co-working facilities
- 4.3 Market Restraints
- 4.3.1 High competition and oversupply risk in top metros leading to pricing pressures
- 4.3.2 Limited penetration in tier-2 and tier-3 cities despite rising demand potential
- 4.3.3 Regulatory and compliance challenges in commercial real estate slowing expansion
- 4.4 Value / Supply-Chain Analysis
- 4.4.1 Overview
- 4.4.2 Real Estate Developers and Asset Owners - Key Quantitative and Qualitative Insights
- 4.4.3 Workspace Design and Technology Consultants - Key Quantitative and Qualitative Insights
- 4.4.4 Modular Furniture and Smart Office Solutions Providers - Key Quantitative and Qualitative Insights
- 4.5 Government Regulations and Initiatives in the Industry
- 4.6 Technological Innovations in the Co-Working Office Space Real Estate Market
- 4.7 Insights into the Key Office Real Estate Industry Metrics (Supply, Rentals, Prices, Occupancy/Vacancy (%))
- 4.8 Impact of Remote Working on Space Demand
- 4.9 Porters Five Forces
- 4.9.1 Bargaining Power of Suppliers
- 4.9.2 Bargaining Power of Buyers
- 4.9.3 Threat of New Entrants
- 4.9.4 Threat of Substitutes
- 4.9.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value USD)
- 5.1 By Size & Scale of Facility
- 5.1.1 Small
- 5.1.2 Medium
- 5.1.3 Large
- 5.2 By Sector
- 5.2.1 Information Technology (IT and ITES)
- 5.2.2 BFSI (Banking, Financial Services and Insurance)
- 5.2.3 Business Consulting & Professional Service
- 5.2.4 Other Services (Retail, Lifesciences, Energy, Legal Services)
- 5.3 By End Use
- 5.3.1 Freelancers
- 5.3.2 Enterprises
- 5.3.3 Start Ups and Others
- 5.4 By City
- 5.4.1 Mumbai Metropolitan Region
- 5.4.2 Delhi NCR
- 5.4.3 Pune
- 5.4.4 Bengaluru
- 5.4.5 Hyderabad
- 5.4.6 Chennai
- 5.4.7 Kolkata
- 5.4.8 Ahmedabad
- 5.4.9 Rest of India
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.3.1 WeWork India
- 6.3.2 Awfis
- 6.3.3 Smartworks
- 6.3.4 91Springboard
- 6.3.5 CoWrks
- 6.3.6 BHIVE Workspaces
- 6.3.7 The Office Pass
- 6.3.8 315Work Avenue
- 6.3.9 Innov8
- 6.3.10 IndiQube
- 6.3.11 Skootr
- 6.3.12 GoodWorks Coworking
- 6.3.13 Spring House Coworking
- 6.3.14 Urban Vault
- 6.3.15 Workafella
- 6.3.16 Regus India
- 6.3.17 Incuspaze
- 6.3.18 The Executive Centre
- 6.3.19 The Hive*