|
시장보고서
상품코드
2116358
영국의 플렉서블 오피스 스페이스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)United Kingdom Flexible Office Space - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
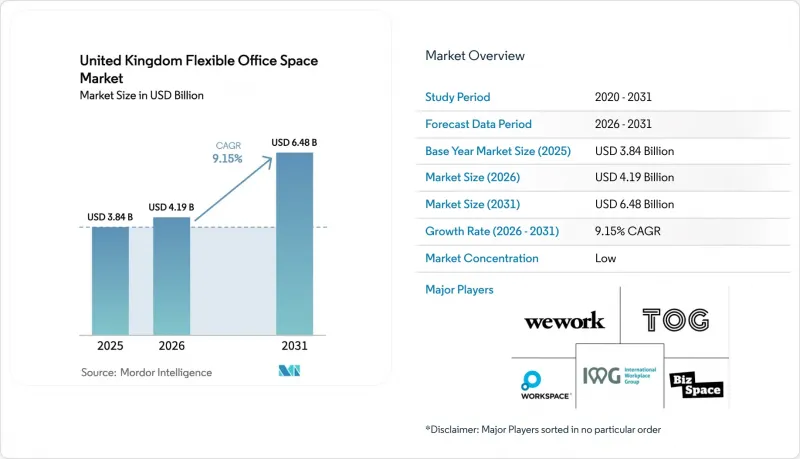
에 의하면, 영국의 플렉서블 오피스 스페이스 시장 규모는 2025년에 38억 4,000만 달러로 평가되었습니다. 2026년 41억 9,000만 달러에서 2031년까지 64억 8,000만 달러에 이를 것으로 추정되고 예측 기간(2026-2031년) CAGR은 9.15%를 나타낼 전망입니다.
본 보고서는 유형별(코워킹 스페이스, 서비스 오피스/이그제큐티브 스위트, 기타), 부문별(IT 및 ITES, 은행, 금융서비스 및 보험(BFSI), 비즈니스 컨설팅·전문 서비스, 기타 서비스), 최종 사용자별(프리랜서, 기업, 스타트업, 기타), 국가별(잉글랜드, 스코틀랜드, 웨일스, 북아일랜드)별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
영국의 플렉서블 오피스 스페이스 시장 동향 및 인사이트
런던 및 지방 도시 전역에서 하이브리드 근무 솔루션에 대한 강력한 수요
직장 정책의 변화와 직원의 선호도를 배경으로, 하이브리드 근무 솔루션에 대한 수요는 계속해서 확대되고 있습니다. 팬데믹 기간 동안 일시적인 조치로 시작된 이 근무 방식은 이제 영구적인 것으로 자리 잡았습니다. 2024년 4월, 입사 첫날부터 직원이 유연한 근무 형태를 신청할 수 있도록 허용하는 규정이 도입됨에 따라 하이브리드 근무는 표준 정책으로 자리 잡았습니다. 이러한 변화하는 상황 속에서 대기업들은 양극화된 시장에 대응할 수밖에 없는 처지에 놓여 있습니다. 이러한 기업의 절반은 여전히 풀타임 출근을 의무화하고 있지만, 주목할 점은 직원의 28%가 주간 근무 시간을 분할하여 근무하는 방식을 채택하고 있다는 것입니다. 이러한 변화로 인해 날짜별로 조정 가능한 업무 공간에 대한 시급한 수요가 발생하고 있습니다. 이러한 양극화에 대응하기 위해 기업들은 맨체스터나 버밍엄과 같은 도시에 위성 사무실을 전략적으로 배치하고 있습니다. 이러한 움직임은 출퇴근 스트레스를 줄일 뿐만 아니라, 런던의 치솟는 임대료에 대한 대책으로도 기능하고 있습니다. 각 오피스 운영사는 이러한 수요를 능숙하게 포착하여, 도심 특유의 위상과 교외의 편의성을 실용적으로 융합한, 여러 거점을 이용할 수 있는 패스를 제공합니다. 또한 법적 의무로서, 유연한 근무 형태에 대한 요청을 거부하기 전에는 충분한 협의를 거쳐야 합니다. 이는 중요한 의미를 지닙니다. 즉, 유연한 사무실 공간에 대한 예산을 장기적인 손익 계산에 반영함으로써, 과거에는 재량적 경비로 간주되던 것이 이제는 지극히 중요한 전략적 과제로 변모하고 있는 것입니다.
기술, 크리에이티브, 전문 서비스 업계에서의 높은 도입률
유연한 사무 공간에 대한 수요 증가는 다양한 업계의 기업 운영 방식을 혁신하고 있습니다. 디지털 기업들은 플러그 앤 플레이 방식의 사무실을 점점 더 많이 선택하고 있으며, 이를 통해 팀은 설비 투자 부담 없이 제품 개발 스프린트를 신속하게 시작하거나, 긱 워커를 채용하거나, 고객사와 함께 해커톤을 개최할 수 있게 되었습니다. 대형 금융 기관들도 최고 수준의 엔지니어 인재를 유치하기 위해 기술 업계를 연상시키는 문화를 도입하고 있습니다. 이러한 변화를 여실히 보여주는 것이 바로 카나리 워프에 자리 잡은 28만 6,000제곱피트 규모의 WeWork 허브입니다. 이곳은 이제 은행 및 금융 서비스·보험(BFSI) 부문이 이러한 흐름을 수용하고 있음을 보여주는 상징이 되었습니다. 크리에이티브 에이전시와 컨설팅 회사에 있어 유연한 사무 공간은 아이디어를 창출하고, 프로토타입을 제작하며, 성과를 발표하는 역동적인 환경으로 기능하며, 고객 경험을 향상시키기 위한 중요한 도구로 진화하고 있습니다. 이러한 수요에 부응하여 운영사들은 팟캐스트 스튜디오, 몰입형 데모룸, 법적 기준을 충족하는 프라이버시 부스 등 전문적인 시설을 도입하기 시작했습니다. 또한, 주요 도심에 다양한 산업이 집적되어 있다는 점은 거래 기회를 늘릴 뿐만 아니라, 임차인들이 커피 한 잔을 마시며 나누는 캐주얼한 대화에서 공식적인 계약 체결로 매끄럽게 전환할 수 있게 해줍니다. 이러한 역동성은 네트워킹의 이점을 확대할 뿐만 아니라, 운영사들에게 안정적인 입주율을 확보하는 데에도 기여하고 있습니다.
런던 중심부의 특정 서브마켓에서 나타나는 공급 과잉 위험
런던 도심의 오피스 시장은 특히 시티(City) 주변에서 공급 과잉 문제에 직면해 있습니다. 2024년, 이 지역의 공실률은 9.2%로 상승했으며, 우량 기업들이 ESG 기준을 준수하는 건물로 이전하는 가운데, 건축 연식이 오래된 B급 타워 빌딩이 가장 큰 타격을 입었습니다. 이러한 공급 과잉은 사업자 간의 가격 경쟁을 유발하고 있으며, 임차인 교체만으로는 메울 수 없는 속도로 이익률을 현저히 떨어뜨리고 있습니다. WeWork의 사우스뱅크 소송 등 주목할 만한 임대차 계약 해지를 둘러싼 분쟁은 특히 수요가 동부나 교외의 통근 도시로 이동하고 있는 상황에서 15년간의 마스터 리스 계약을 체결하는 데 따르는 위험을 여실히 드러내고 있습니다. 그러나 신규 준공 물량 감소가 예상에 따라, 2027년까지 시장 균형이 회복될 가능성이 있습니다. 향후 2년간의 과제를 극복할 수 있는 시장 진출기업들은 공급 과잉이 완화되는 시점에, 부동산 가격을 프리미엄 가격으로 재설정할 기회를 얻을 수 있을지도 모릅니다.
부문별 분석
2025년, 코워킹 부문은 영국의 플렉서블 오피스 스페이스 시장 점유율의 50.85%를 차지했습니다. ‘런치 앤 러닝’부터 투자자 대상 피치 이벤트에 이르기까지, 커뮤니티 중심 프로그램이 책상 이직률을 낮게 억제하고 소개 건수를 높은 수준으로 유지하고 있습니다. 운영 사업자는 핫데스크 패스, 전용 책상, 프라이빗 스튜디오를 조합하여 사용자층에 관계없이 수익을 안정화하고 있습니다. 포춘 500대 기업이 영국 내 직원 수의 15%를 유연 근무 제도로 전환함에 따라 기업 수요가 급증했습니다. 이에 따라 사업자들은 공유 공간 내에 기업을 위한 고보안 배지 관리 구역을 마련하게 되었습니다. 현재 경쟁사와의 차별화를 이끄는 핵심 요소는 예약, 청구, 출입 관리를 자동화하는 독자적인 앱 생태계이며, 이를 통해 직원 배치 비율은 회원 300명당 1명 미만의 커뮤니티 매니저 수준으로까지 감소했습니다.
‘기타’ 부문(하이브리드 및 가상)은 분산형 팀이 ‘정기 출근’ 패키지(사서함, 분기별 오프사이트 공간, 종량제 회의 크레딧을 포함한 세트)를 채택함에 따라 2031년까지 연평균 성장률(CAGR) 10.35%로 가장 빠르게 성장할 전망입니다. 가상 주소는 영국에 거점을 둔 해외 기업에 대한 브렉시트 이후의 규제 요건을 충족하는 동시에, 거의 제로에 가까운 운영 비용으로 시장 진입을 시험해 볼 수 있게 해줍니다. 주요 제공업체들은 자사의 거점 네트워크를 활용하여, 직원 수가 증가한 단계에서 가상 고객에게 물리적 책상으로의 업셀링을 진행함으로써 평생 가치(LTV)를 확대되고 있습니다. 또한, 하이브리드 패스는 실시간 이용 데이터를 제공하여 기업이 고정 임대 규모를 적정화할 수 있도록 지원하는 한편, 플랫폼을 이탈할 때의 전환 비용을 높임으로써 영국의 플렉서블 오피스 스페이스 시장에서 대형 업체들의 우위를 더욱 확대되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.31According to Mordor Intelligence, the UK flexible office market size was valued at USD 3.84 billion in 2025 and estimated to grow from USD 4.19 billion in 2026 to reach USD 6.48 billion by 2031, at a CAGR of 9.15% during the forecast period (2026-2031).
This report is Segmented by Type (Co-Working Space, Serviced Offices/Executive Suites and Others), by Sector (IT and ITES, BFSI, Business Consulting & Professional Service and Other Services), by End Use (Freelancers, Enterprises, Start Ups and Others), and by Country (England, Scotland, Wales and Northern Ireland). The Market Forecasts are Provided in Terms of Value (USD).
United Kingdom Flexible Office Space Market Trends and Insights
Strong Demand for Hybrid Work Solutions Across London and Regional Cities
The demand for hybrid work solutions continues to grow, driven by evolving workplace policies and employee preferences. What began as a temporary measure during the pandemic has now solidified into a permanent fixture. Following the April 2024 regulation allowing staff to request flexibility from day one, hybrid working has transitioned into a standard policy. In this evolving landscape, large employers find themselves navigating a divided market. While half of these employers still mandate full-time attendance, a notable 28% of workers have adopted a split-week approach. This shift has created a pressing demand for desks that can be adjusted on a daily basis. In response to this duality, corporations are strategically positioning satellite hubs in cities like Manchester and Birmingham. This move not only alleviates commuter stress but also serves as a countermeasure against the soaring rents in London. Operators are adeptly tapping into this demand, offering multisite access passes that seamlessly combine the allure of city-center prestige with the practicality of suburban convenience. Furthermore, a legal mandate now requires meaningful consultations before any rejection of flexible requests. This has significant implications: it integrates flexible office budgets into long-term profit and loss considerations, transforming what was once viewed as a discretionary expense into a pivotal strategic imperative.
High Adoption by Technology, Creative, and Professional Services Sectors
The increasing demand for flexible office spaces is reshaping how businesses operate across various sectors. Digital firms are increasingly opting for plug-and-play offices, enabling teams to swiftly initiate product sprints, onboard gig talent, and conduct client hackathons-all without the burden of capital expenditure. Major financial institutions, in a bid to attract top coding talent, are adopting a culture reminiscent of the tech industry. A testament to this shift is WeWork's expansive 286,000 square-foot hub in Canary Wharf, now a beacon of the banking, financial services, and insurance (BFSI) sector's embrace. For creative agencies and consultancies, flexible office spaces have evolved into pivotal tools for enhancing client experiences-serving as dynamic environments for ideation, prototyping, and showcasing results. This demand has prompted operators to incorporate specialized features like podcast studios, immersive demo rooms, and privacy booths that meet legal standards. Furthermore, the clustering of diverse industries in major urban centers not only boosts deal flow but also allows tenants to seamlessly transition from casual coffee discussions to formal contracts. This dynamic not only amplifies the advantages of networking but also ensures consistent occupancy for operators.
Oversupply Risk in Certain Central London Submarkets
The Central London office market is grappling with oversupply challenges, particularly in the City fringe. In 2024, the vacancy rate in this area increased to 9.2%, with older Grade B towers being the most affected as blue-chip companies transitioned to ESG-compliant properties. This oversupply has triggered price wars among operators, significantly eroding margins at a pace that license churn cannot counterbalance. Prominent lease-exit disputes, such as WeWork's Southbank litigation, highlight the risks of committing to 15-year headleases, especially as demand shifts towards the east or commuter towns. However, the anticipated reduction in new completions could help restore balance by 2027. Market participants who can endure the next two challenging years may have the opportunity to reprice their spaces at a premium once the oversupply diminishes.
Other drivers and restraints analyzed in the detailed report include:
- Investor Interest in Flexible Office Portfolios as a Resilient Asset Class
- Growing Demand for Sustainability-Certified and Wellness-Integrated Workspaces
- Rising Operational Costs for Flexible Office Operators Impacting Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The co-working segment represented 50.85% of UK flexible office market share in 2025. Community programming, ranging from lunch-and-learns to investor pitch nights, keeps desk churn low and referral volume high. Operators blend hot-desk passes, dedicated desks, and private studios to smooth revenue across user tiers. Corporate demand surged after Fortune 500s shifted 15% of their UK headcount into flexible allowances, prompting providers to carve enterprise-grade, badge-controlled zones inside shared floors. Competitive differentiation now centers on proprietary app ecosystems that automate booking, billing, and access, which cuts staffing ratios to under one community manager per 300 members.
The Others segment (hybrid and virtual) will grow fastest at 10.35% CAGR through 2031 as distributed teams adopt "periodic presence" packages: bundles that include mailbox, quarterly off-site space, and pay-as-you-go meeting credits. Virtual addresses satisfy post-Brexit regulatory rules for overseas companies setting up in the UK while letting them test market entry with near-zero overhead. Larger providers leverage their footprint to upsell virtual clients into physical desks once headcount scales, extending lifetime value. Hybrid passes also supply real-time usage data, helping corporates right-size fixed leases and raising switching costs should they leave the platform-extending the lead of scale players in the UK flexible office market.
Complete Report Scope:
- By Type
- Co-Working Space
- Serviced offices / Executive suites
- Others (Hybrid, Virtual Office)
- By Sector
- Information Technology (IT and ITES)
- BFSI (Banking, Financial Services and Insurance)
- Business Consulting & Professional Service
- Other Services (Retail, Lifesciences, Energy, Legal Services)
- By End Use
- Freelancers
- Enterprises
- Start Ups and Others
- By Country
- England
- Scotland
- Wales
- Northern Ireland
List of Companies Covered in this Report:
- International Workplace Group (IWG / Regus / Spaces)
- WeWork
- The Office Group
- Workspace Group
- BizSpace (Sirius Real Estate)
- Bruntwood Works
- Landmark Space
- Huckletree
- Fora
- TOG & Fora (Joint entity)
- Knotel UK
- Industrious (LXD UK)
- x+why
- Plexal
- Mindspace
- Labs
- Uncommon
- Runway East
- Oval Real Estate (Division)
- Orega
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Strong demand for hybrid work solutions across London and regional cities
- 4.2.2 High adoption by technology, creative, and professional services sectors
- 4.2.3 Investor interest in flexible office portfolios as a resilient asset class
- 4.2.4 Growing demand for sustainability-certified and wellness-integrated workspaces
- 4.2.5 Expansion of global co-working brands alongside strong local operators
- 4.3 Market Restraints
- 4.3.1 Oversupply risk in certain central London submarkets
- 4.3.2 Uncertain macroeconomic conditions and Brexit-linked investment caution
- 4.3.3 Rising operational costs for flexible office operators impacting margins
- 4.4 Value / Supply-Chain Analysis
- 4.4.1 Overview
- 4.4.2 Real Estate Developers and Asset Owners - Key Quantitative and Qualitative Insights
- 4.4.3 Workspace Design and Technology Consultants - Key Quantitative and Qualitative Insights
- 4.4.4 Modular Furniture and Smart Office Solutions Providers - Key Quantitative and Qualitative Insights
- 4.5 Government Regulations and Initiatives in the Industry
- 4.6 Technological Innovations in the Flexible Office Real Estate Market
- 4.7 Insights into the Key Office Real Estate Industry Metrics (Supply, Rentals, Prices, Occupancy/Vacancy (%))
- 4.8 Impact of Remote Working on Space Demand
- 4.9 Porter's Five Forces
- 4.9.1 Bargaining Power of Suppliers
- 4.9.2 Bargaining Power of Buyers
- 4.9.3 Threat of New Entrants
- 4.9.4 Threat of Substitutes
- 4.9.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value USD)
- 5.1 By Type
- 5.1.1 Co-Working Space
- 5.1.2 Serviced offices / Executive suites
- 5.1.3 Others (Hybrid, Virtual Office)
- 5.2 By Sector
- 5.2.1 Information Technology (IT and ITES)
- 5.2.2 BFSI (Banking, Financial Services and Insurance)
- 5.2.3 Business Consulting & Professional Service
- 5.2.4 Other Services (Retail, Lifesciences, Energy, Legal Services)
- 5.3 By End Use
- 5.3.1 Freelancers
- 5.3.2 Enterprises
- 5.3.3 Start Ups and Others
- 5.4 By Country
- 5.4.1 England
- 5.4.2 Scotland
- 5.4.3 Wales
- 5.4.4 Northern Ireland
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.3.1 International Workplace Group (IWG / Regus / Spaces)
- 6.3.2 WeWork
- 6.3.3 The Office Group
- 6.3.4 Workspace Group
- 6.3.5 BizSpace (Sirius Real Estate)
- 6.3.6 Bruntwood Works
- 6.3.7 Landmark Space
- 6.3.8 Huckletree
- 6.3.9 Fora
- 6.3.10 TOG & Fora (Joint entity)
- 6.3.11 Knotel UK
- 6.3.12 Industrious (LXD UK)
- 6.3.13 x+why
- 6.3.14 Plexal
- 6.3.15 Mindspace
- 6.3.16 Labs
- 6.3.17 Uncommon
- 6.3.18 Runway East
- 6.3.19 Oval Real Estate (Division)
- 6.3.20 Orega