|
시장보고서
상품코드
2113268
부타디엔 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Butadiene - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 부타디엔 시장 규모는 2025년 1,461만 톤에서 2026년에는 1,504만 톤으로 확대되고, 2026-2031년 CAGR 2.95%로 성장을 지속하여, 2031년에는 1,739만 톤에 이를 것으로 예측됩니다.
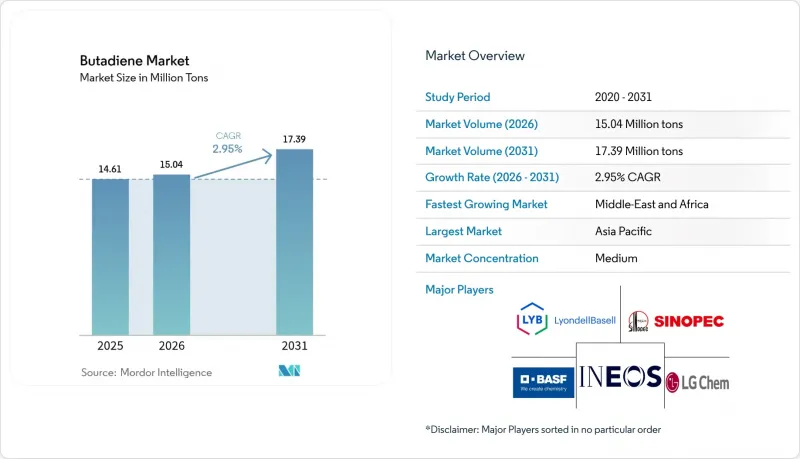
본 보고서는 용도별(폴리부타디엔, 클로로프렌, 스티렌-부타디엔, 니트릴 고무, SB 라텍스, ABS, 아디포니트릴, 설포란, 에틸리덴 노르보르넨, 기타), 최종 사용자 산업별(플라스틱·폴리머,타이어·고무, 화학, 기타) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 수량(톤) 기준으로 제시되어 있습니다.
세계 부타디엔 시장 동향 및 인사이트
아시아태평양의 자동차 및 타이어 생산 증가
아시아태평양의 타이어 생산 대수는 2024년에 13억 대를 돌파했습니다. 이는 해당 지역 생산량의 약 70%를 차지하는 중국, 인도, 일본이 주도한 결과입니다. 고시스형 폴리부타디엔은 승용차용 타이어 트레드 배합의 10-15%를 차지하고 있으며, 이로 인해 부타디엔 시장 수요가 직접적으로 증가하고 있습니다. 태국의 풍부한 천연고무 공급과 인도네시아의 오토바이용 타이어 산업이 지역 성장을 뒷받침하는 한편, 인도와 베트남에서 레이디얼 트럭용 타이어로의 전환으로 인해 타이어 1개당 합성고무 사용량이 증가하고 있습니다. 2024년 유럽연합(EU) 및 영국으로의 수입량은 전년 대비 18% 증가했으며, 이는 성숙한 시장에서도 아시아 생산자들이 증가분 수요를 확보하고 있음을 보여줍니다.
가전제품에서의 ABS 수요 증가
ABS 수지는 뛰어난 충격 강도와 매끄러운 표면 마감을 갖추고 있어, 고충격 폴리스티렌에 비해 15-20%의 가격 프리미엄을 유지하고 있습니다. 2025년에 시행된 미국의 무역 조치로 인해 수입 전자기기의 도착 비용이 약 10% 상승함에 따라, 각 브랜드는 조립을 니어쇼어화하고 국내 ABS를 확보하게 되어 북미의 부타디엔 수급 균형이 타이트해졌습니다. 부타디엔은 ABS 조성의 20-25%를 차지하기 때문에 ABS 생산량이 1퍼센트 포인트 증가할 때마다 부타디엔 소비량은 0.2-0.25퍼센트 포인트 증가합니다. 또한, ABS-폴리카보네이트 블렌드는 할로겐계 첨가제를 사용하지 않고도 엄격한 난연성 기준을 충족할 수 있기 때문에 자동차 내장 트림에 대한 수요 증가가 ABS 출하량을 더욱 끌어올리고 있습니다.
독성 및 강화되는 노출 한계치
미국 직업안전보건청(OSHA)은 부타디엔에 대해 8시간 허용 노출 한계치를 1ppm, 15분간 허용 편차 한계치를 5ppm으로 정하고 있으며,이에 따라 크래커 운영 사업자는 폐쇄 루프식 증기 회수 시스템이나 연속 모니터링 장치 설치를 강요받고 있으며, 그 비용은 시설당 500만-800만 달러에 달하는 경우가 많습니다. 캘리포니아주의 ‘프로포지션 65’에 따른 표시 요건은 다운스트림 공정에서의 규정 준수 비용을 더욱 증가시키고 있습니다. 한편, 유럽화학물질청(ECHA)은 현재 미국 기준치의 절반에 해당하는 0.5ppm이라는 작업장 노출 한계치 도입을 제안하고 있습니다. 소규모 추출 시설은 불균형적인 영향을 받고 있으며, 이는 업계 재편을 촉진하여 2026년까지 전 세계 부타디엔 추출 시설의 수가 약 160곳으로 감소할 것으로 예측됩니다.
부문 분석
폴리부타디엔은 2025년 용도별 생산량의 26.27%를 차지하며, 고시스형 등급이 내마모성과 저온 유연성을 극대화하는 타이어 트레드 및 사이드월 배합에서 확고한 입지를 입증하고 있습니다. SIBUR사는 2024년에 러시아 내 폴리부타디엔 생산 능력을 확대할 예정이며, 한편 ARLANXEO사는 주바이르에 연간 14만 톤 규모의 초고시스형 시설을 건설 중이며, 2026년에 가동을 시작할 예정입니다. ABS 수지는 가전제품 및 자동차 내장 부품에 대한 수요에 힘입어 2031년까지 연평균 성장률(CAGR) 3.94%로 확대될 것으로 예측되며, 이에 따라 지역 부타디엔 시장의 수급 균형이 타이트해질 것으로 전망됩니다. 스티렌-부타디엔 고무(SBR)는 젖은 노면 접지력과 구름 저항의 균형을 중시하는 주요 타이어 제조업체에게 여전히 필수적이며, 전기차용 타이어에서는 솔루션 등급이 에멀젼 유형을 꾸준히 대체하고 있습니다.
니트릴 고무는 자동차용 씰 용도의 60%를 차지하고 있지만, 새롭게 등장한 수소화 니트릴 고무는 150°C의 열 사이클에 지속적으로 노출되는 전기차용 배터리 팩을 목표로 하고 있습니다. 부타디엔의 시아노화 반응을 통해 생산되는 아디포니트릴은 엔진룸 부품용 나일론 6,6의 원료로 사용되며, 인비스타(Invista)는 이 부문에서 연간 4-5%의 성장에 대응하기 위해 2024년에 북미의 생산 능력을 확대할 예정입니다. 클로로프렌 고무, 설포란, 에틸리덴 노르보르넨 등의 소규모 시장은 안정적인 수요 기반을 유지하는 데 기여하고 있습니다. 2024년 톤당 500달러의 가격 상승은 원자재비 및 에너지 비용 상승을 반영한 것입니다.
지역별 분석
아시아태평양은 2025년 생산량의 51.62%를 차지했습니다. 이는 중국의 PDH 복합 시설이 2022년 수준보다 77% 높은 생산 능력을 확충했기 때문이며, 프로판-나프타 스프레드가 톤당 150달러를 초과할 경우 나프타 크래커의 평균 생산 비용보다 10-15% 낮은 전용 생산 비용을 실현하고 있습니다. 롯데케미칼은 2024년에 추출 능력을 연간 21만 톤으로 확대했으며, 한편 릴라이언스 인더스트리즈는 2030년까지 잠나가르에서 바이오나프타 통합을 특징으로 하는 70만 톤의 증산을 계획하고 있습니다. 생산 능력 증가에도 불구하고, 2024년 초에는 현물 가격이 톤당 900달러 아래로 떨어지면서 중국 생산자들은 할인된 가격으로 수출할 수밖에 없게 되었고, 그 결과 중동 및 북미의 경쟁사들을 압박하게 되었습니다. 일본과 한국은 생산을 억제하고 있으며-제온은 2026년도에 토쿠야마의 엘라스토머 생산 라인을 축소할 의향입니다-또한 말레이시아의 롯데·우베 합작 사업도 수년간 지속된 이익률 압박으로 인해 축소되고 있습니다.
중동 및 아프리카은 연평균 성장률(CAGR) 5.89%를 나타낼 것으로 예측되며, 그 견인차 역할은 사우디아라비아가 승인한 Sipchem과 LyondellBasell의 혼합 원료 크래커가 맡을 것으로 보입니다. 이 시설은 에틸렌 150만 톤 및 부타디엔을 포함한 파생 제품 180만 톤의 생산 능력을 갖추고 있으며, 2025년 2월에 최종 투자 결정(FID)이 이루어졌습니다. 2030년까지 완공될 예정인 타스니(Tasnee)사의 330만 톤 규모 석유화학 단지와, ADNOC의 코베스트로(Covestro)사 등 특수 자산 인수 움직임은 해당 지역이 통합 플랫폼을 통해 수반 가스를 수익화하려는 의도를 보여줍니다. 걸프협력회의(GCC) 화학 부문의 매출은 2023년 858억 달러에서 2030년까지 1,333억 달러로 증가할 것으로 예측되며, 이는 하류 부문의 다각화에 따른 부타디엔 수요 증가를 뒷받침하는 기반이 될 것입니다.
북미와 유럽에서는 이익률 압박과 자산 합리화에 직면해 있습니다. 쉘은 2023년에 가이스마르 추출 공장을 INEOS에 매각했으며, 베르살리스는 2024년 에너지 비용이 다른 지역보다 높다는 점을 감안하여 그랜지마우스에 위치한 연산 10만 5,000톤 규모의 폴리부타디엔 생산 라인을 폐쇄했습니다. 굿이어가 13억 달러 규모의 비용 절감 프로그램의 일환으로 보몬트와 휴스턴의 화학 자산을 매각한다고 발표한 것은 범용 엘라스토머에서 고부가가치 고성능 타이어로의 전환을 여실히 보여주고 있습니다. 2025년 1분기 유럽의 타이어 생산량은 3% 증가했지만, 2024년 중국산 타이어 수입량은 18% 급증하여 지역 제조업체들이 직면한 경쟁력 문제가 부각되고 있습니다. 남미는 여전히 기여도가 낮은 편이지만, ARLANXEO사의 트리운포 공장에서의 생산 능력 확대와 천연고무 농장과의 근접성으로 인해 블렌딩이 용이하다는 이점을 누리고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.08.24According to Mordor Intelligence, the butadiene market size is expected to grow from 14.61 million tons in 2025 to 15.04 million tons in 2026 and is forecast to reach 17.39 million tons by 2031 at 2.95% CAGR over 2026-2031.
This report is Segmented by Application (Polybutadiene, Chloroprene, Styrene-Butadiene, Nitrile Rubber, SB Latex, ABS, Adiponitrile, Sulfolane, Ethylidene Norbornene, and Others), End-User Industry (Plastic and Polymer, Tire and Rubber, Chemical, and Others), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). Market Forecasts are Provided in Terms of Volume (tons).
Global Butadiene Market Trends and Insights
Rising Automotive and Tire Production in Asia-Pacific
Asia-Pacific tire output surpassed 1.3 billion units in 2024, supported by China, India, and Japan, which jointly contributed about 70% of regional volume. High-cis polybutadiene accounts for 10-15% of passenger-tire tread formulations, thereby directly increasing butadiene market demand. Thailand's strong natural-rubber supply and Indonesia's motorcycle-tire ecosystem underpin regional growth, while India and Vietnam's shift toward radial truck tires increases synthetic-rubber use per unit. Imports into the European Union and the United Kingdom increased by 18% year-over-year in 2024, indicating that Asian producers are capturing incremental demand even in mature markets.
Expanding ABS Demand from Consumer Electronics
ABS resin maintains a 15-20% price premium over high-impact polystyrene because it offers superior impact strength and a smoother surface finish. US trade measures enacted in 2025 lifted landed costs for imported electronics by roughly 10%, prompting brands to nearshore assembly and secure domestic ABS, tightening butadiene balances in North America. Because butadiene accounts for 20-25% of ABS composition, each incremental percentage point of ABS output drives 0.2-0.25 percentage points of additional butadiene consumption. Automotive interior-trim growth further supports ABS volumes, as ABS-polycarbonate blends meet stringent flame-retardancy standards without the use of halogenated additives.
Toxicity and Tightening Exposure Limits
The US Occupational Safety and Health Administration enforces an 8-hour permissible exposure limit of 1 ppm and a 15-minute excursion limit of 5 ppm for butadiene, prompting cracker operators to install closed-loop vapor-recovery systems and continuous monitors, often costing USD 5-8 million per facility. California's Proposition 65 labeling requirements add downstream compliance expenses, while the European Chemicals Agency is proposing a 0.5 ppm workplace limit, half the current US threshold. Smaller extraction units are disproportionately impacted, driving consolidation and trimming the global count of butadiene extraction facilities to an estimated 160 by 2026.
Other drivers and restraints analyzed in the detailed report include:
- EV-Ready High-Performance S-SBR Adoption
- Rapid Capacity Additions in Bio-Butadiene
- Crude-Oil Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polybutadiene captured 26.27% of 2025 application volume, confirming its entrenched role in tire tread and sidewall formulations where high-cis grades maximize abrasion resistance and cold-weather flexibility. SIBUR expanded its Russian polybutadiene capacity in 2024, while ARLANXEO is building a 140,000-ton-per-year ultra-high-cis facility in Jubail, slated for a 2026 start-up. ABS resins are projected to advance at a 3.94% CAGR to 2031, driven by demand for consumer electronics and automotive interior trim, which is expected to tighten regional butadiene market balances. Styrene-butadiene rubber remains vital for mainstream tire producers that balance wet grip and rolling resistance; solution grades are steadily displacing emulsion types in EV fitments.
Nitrile rubber accounts for 60% of automotive seal applications, while emerging hydrogenated nitrile rubbers target EV battery packs that face sustained 150°C thermal cycling. Adiponitrile produced from butadiene cyanation feeds nylon 6,6 for under-hood components, with Invista increasing its North American capacity in 2024 to meet a 4-5% annual growth in this segment. Smaller outlets, such as chloroprene rubber, sulfolane, and ethylidene norbornene, help maintain a stable baseline demand; price rises of USD 500 per ton in 2024 reflected higher feedstock and energy costs.
Complete Report Scope:
- By Application
- Polybutadiene (PBR)
- Chloroprene
- Styrene-Butadiene (SBR)
- Nitrile Rubber (Acrylonitrile Butadiene NBR)
- SB Latex
- Acrylonitrile Butadiene Styrene (ABS)
- Adiponitrile
- Sulfolane
- Ethylidene Norbornene
- Others
- By End-user Industry
- Plastic and Polymer
- Tire and Rubber
- Chemical
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
The Asia-Pacific region represented 51.62% of the 2025 volume, thanks to Chinese PDH complexes that added capacity 77% above 2022 levels, enabling on-purpose production costs 10-15% below naphtha-cracker averages when propane-naphtha spreads widen beyond USD 150 per ton. Lotte Chemical increased its extraction capacity to 210,000 tons per year in 2024, while Reliance Industries plans a 0.7-million-ton expansion at Jamnagar, featuring bio-naphtha integration, by 2030. Despite capacity gains, spot prices dipped below USD 900 per ton in early 2024, compelling Chinese producers to export at discounts that squeezed Middle Eastern and North American competitors. Japan and South Korea are curbing output-Zeon intends to reduce Tokuyama elastomer lines in fiscal 2026-and the Lotte-Ube JV in Malaysia is winding down after years of margin pressure.
Middle East & Africa is projected to grow at a 5.89% CAGR, led by Saudi approvals for a Sipchem-LyondellBasell mixed-feed cracker capable of 1.5 million tons of ethylene and 1.8 million tons of derivatives, including butadiene, with a final investment decision reached in February 2025. Tasnee's 3.3 million-ton petrochemical complex, due by 2030, and ADNOC's bid to acquire specialty assets, such as Covestro, illustrate the region's move to monetize associated gas via integrated platforms. Gulf Cooperation Council chemical revenue is forecast to climb from USD 85.8 billion in 2023 to USD 133.3 billion by 2030, anchoring incremental butadiene demand tied to downstream diversification.
North America and Europe contend with margin compression and asset rationalization. Shell sold its Geismar extraction unit to INEOS in 2023, and Versalis shuttered its 105,000-ton polybutadiene line at Grangemouth in 2024 as energy costs outstripped peer regions. Goodyear's announced divestiture of its Beaumont and Houston chemical assets under a USD 1.3 billion cost-reduction program underscores the shift toward higher-value performance tires over commodity elastomers. European tire output rose 3% in Q1 2025, but Chinese tire imports surged 18% in 2024, highlighting competitiveness challenges for regional producers. South America remains a smaller contributor but benefits from ARLANXEO's expanded Triunfo capacity and proximity to natural-rubber plantations that facilitate blended formulations.
- BASF
- Braskem
- China National Petroleum Corporation
- China Petroleum & Chemical Corporation
- Dow
- ENEOS Materials Corporation
- Evonik Industries AG
- Exxon Mobil Corporation
- Formosa Plastics Corporation
- INEOS
- LG Chem
- LOTTE CHEMICAL TITAN HOLDING BERHAD
- LyondellBasell Industries Holdings BV
- Reliance Industries Limited
- Repsol
- Shell plc
- SABIC
- TPC Group
- ARLANXEO
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising automotive and tire production in Asia-Pacific
- 4.2.2 Expanding ABS demand from consumer electronics
- 4.2.3 EV-ready high-performance S-SBR adoption
- 4.2.4 Rapid capacity additions in bio-butadiene
- 4.2.5 Growth of Li-ion battery binders using SBR
- 4.3 Market Restraints
- 4.3.1 Toxicity and tightening exposure limits
- 4.3.2 Crude-oil price volatility
- 4.3.3 China overcapacity depressing margins
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
- 4.6 Feedstock Analysis
- 4.7 Technological snapshot
5 Market Size & Growth Forecasts (Volume)
- 5.1 By Application
- 5.1.1 Polybutadiene (PBR)
- 5.1.2 Chloroprene
- 5.1.3 Styrene-Butadiene (SBR)
- 5.1.4 Nitrile Rubber (Acrylonitrile Butadiene NBR)
- 5.1.5 SB Latex
- 5.1.6 Acrylonitrile Butadiene Styrene (ABS)
- 5.1.7 Adiponitrile
- 5.1.8 Sulfolane
- 5.1.9 Ethylidene Norbornene
- 5.1.10 Others
- 5.2 By End-user Industry
- 5.2.1 Plastic and Polymer
- 5.2.2 Tire and Rubber
- 5.2.3 Chemical
- 5.2.4 Others
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 France
- 5.3.3.3 United Kingdom
- 5.3.3.4 Italy
- 5.3.3.5 Russia
- 5.3.3.6 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.4.1 BASF
- 6.4.2 Braskem
- 6.4.3 China National Petroleum Corporation
- 6.4.4 China Petroleum & Chemical Corporation
- 6.4.5 Dow
- 6.4.6 ENEOS Materials Corporation
- 6.4.7 Evonik Industries AG
- 6.4.8 Exxon Mobil Corporation
- 6.4.9 Formosa Plastics Corporation
- 6.4.10 INEOS
- 6.4.11 LG Chem
- 6.4.12 LOTTE CHEMICAL TITAN HOLDING BERHAD
- 6.4.13 LyondellBasell Industries Holdings BV
- 6.4.14 Reliance Industries Limited
- 6.4.15 Repsol
- 6.4.16 Shell plc
- 6.4.17 SABIC
- 6.4.18 TPC Group
- 6.4.19 ARLANXEO
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment