

|
시장보고서
상품코드
2113561
유럽의 의료 임상 영양 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Medical Clinical Nutrition - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
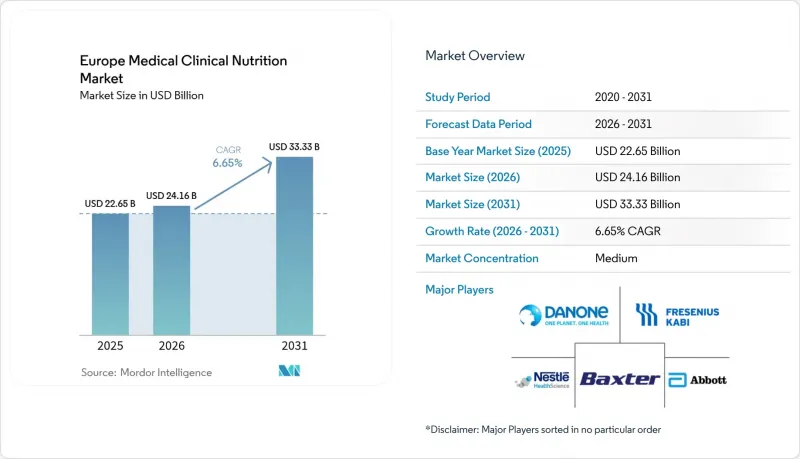
에 의하면, 유럽의 의료 임상 영양 시장 규모는 2025년에 226억 5,000만 달러, 2026년에 241억 6,000만 달러에 이르고, 2031년까지 333억 3,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 6.65%를 기록할 전망입니다.
본 보고서는 투여 경로(경구·경장, 비경구), 제품 유형(표준화 경장영양제 등), 용도(종양학, 대사성 질환 등), 최종 사용자(영아, 소아 등), 유통 채널(병원 약국 등), 국가(독일, 영국 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽의 의료 임상 영양 시장 동향 및 인사이트
만성 질환 및 대사성 질환 유병률 증가
2024년에는 암 환자 수가 420만 명에 달할 것으로 예상되며, 현재 말기 환자의 최대 80%가 악액질에 시달리고 있습니다. 이에 따라 ESMO는 2025년 프로토콜에서 진단 후 48시간 이내에 고단백 경구 보충제와 저항성 훈련을 병행할 것을 권장하고 있으며, 이를 통해 6개월 생존율이 18% 향상되었습니다. 유럽의 2형 당뇨병 성인 환자 수는 6,200만 명에 달하며, EASD는 고분자 제제와 비교하여 식후 혈당 수치를 35% 낮게 유지하는 저혈당 지수 경장영양제를 권장하고 있습니다. 2024년 기준, 염증성 장질환(IBD) 유병자 수는 320만 명을 넘어섰습니다. ECCO 지침에서는 소아 크론병 치료에 있어 장내 영양 단독 요법을 1순위 치료법으로 격상시켜 관해율을 65%로 높였으며, 독일, 프랑스,네덜란드 병원의 처방 지침을 재검토했습니다. 신장 전문의들은 현재 신장 질환에 특화된 영양제를 활용하여 만성 신장 질환을 앓는 성인의 15%에서 투석 시작 시기를 12-18개월 늦추고 있습니다.
고령화와 의료비 급증
2030년까지 유럽의 65세 이상 주민 수는 1억 5,000만 명에 달할 전망입니다. 입원 중인 고령자의 3분의 1은 이미 단백질·에너지 영양실조를 보이고 있으며, 이로 인해 입원 기간이 4-6일 연장되고 있습니다. ESPEN은 2024년에 사르코페니아를 보험 적용 대상 질환으로 지정하여, 독일, 프랑스, 네덜란드 전역에서 고단백 경구 영양 보충제의 보험 적용이 가능해졌습니다. 2024년 EU의 의료비 지출은 1조 8,000억 유로(1조 9,500억 달러)에 달했으나, 체계적인 영양 선별 검사를 통해 합병증이 감소한 결과 총 비용은 12% 절감되었습니다. 잉글랜드 국민보건서비스(NHS) 체계에서는 2025년 4월부터 24시간 체제의 영양실조 선별 검사와 경구 보충제의 표준 처방 기준이 의무화되어, 대상 환자의 30%를 배제하던 우편번호에 따른 격차가 해소되었습니다.
임상 영양에 대한 환자 및 의료진의 인식 부족
이탈리아와 스페인에서는 입원 환자의 50% 미만이 영양실조 선별 검사를 받고 있으며, 위험에 처한 환자의 40%가 치료받지 못한 채 남아 있습니다. 유럽의 일반의 중 경구 영양 보충제를 정기적으로 처방하는 비율은 고작 35%에 불과하며, 그 이유로 제품에 대한 지식이 제한적이라는 점이 꼽히고 있습니다. 포르투갈의 농촌 지역에서는 2025년에 의사 5,000명을 대상으로 한 연수를 실시하는 전국 캠페인이 진행되었음에도 불구하고, MUST와 같은 검증된 도구의 이용률은 30% 미만에 그치고 있습니다. 환자들의 오해도 여전히 뿌리 깊게 남아 있습니다. 이탈리아와 스페인의 암 환자 중 70%는 영양 요법이 화학요법으로 인한 체중 감소를 완화할 수 있다는 사실을 모르고 있습니다. 동유럽에서는 영양사 1명당 환자 수가 1만 명인 반면, 서유럽에서는 2,500명에 불과하여 더욱 큰 제약을 받고 있습니다.
부문 분석
2025년, 유럽의 의료 임상 영양 시장에서 경구 및 장내 영양법은 68.55%의 점유율을 유지했습니다. 이는 장이 기능하는 경우 항상 경구 영양을 우선시한다는 ESPEN의 ‘장 우선(gut-first)’ 지침에 힘입은 결과입니다. 중환자실(ICU) 입원 후 48시간 이내에 시행되는 조기 장내 영양 공급은 현재 환자의 45%에게 시행되고 있으며, 인공호흡기 관련 폐렴을 25% 감소시키고 있습니다. 표준 경구 영양제는 고령자 및 암 환자 집단에서 주류를 이루고 있으며, 고단백 처방전의 60%를 차지하고 있습니다.
그럼에도 불구하고, 각국의 보험 기관이 재택 정맥 영양(HPN)의 적용 범위를 확대함에 따라 비경장 요법은 2031년까지 연평균 성장률(CAGR) 8.25%로 성장하고 있습니다. 스칸디나비아 국가들의 등록 데이터에 따르면, 폐색을 억제하는 오메가-3 지질 에멀젼의 도입으로 연간 12%의 성장을 기록했으며, 카테터의 평균 수명을 26개월로 연장했습니다. 프레제니우스 카비(Fresenius Kabi)의 ‘Numeta’ 백(주입 준비 완료)은 조제 시간을 45분에서 5분 미만으로 단축하고, 조제 오류를 70% 감소시켰습니다. 이는 혁신이 재택 환경에서의 비경구 영양 솔루션 방식을 어떻게 변화시킬 수 있는지를 보여줍니다.
제네릭 고분자 제제는 2025년 매출의 45.53%를 차지하며, 내과·외과 혼합 병동에서 여전히 주력 제품으로 자리 잡고 있습니다. 식이섬유가 풍부한 제품은 설사를 30% 완화하고 혈당 프로파일을 개선하고 있습니다.
고도의 치료가 필요한 분야에서는 질환 특이적 조제액으로의 전환이 진행되고 있습니다. 유럽의 의료 임상 영양 시장에서 비경구 다량영양소 제제 시장 규모는 연간 7.75%의 속도로 확대될 전망입니다. 이는 2024년부터 2025년에 걸쳐 EMA(유럽의약품청)의 승인을 받은 4세대 지질 유제가 혈류 감염을 30% 감소시키는 데 기여하고 있기 때문입니다. 독일의 보험사는 현재 이러한 지질 제제 비용의 90%를 보상하고 있으며, ICU(중환자실)는 사전 승인에 따른 병목 현상에서 해방되었습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.08.25According to Mordor Intelligence, the Europe medical clinical nutrition market size is projected to be USD 22.65 billion in 2025, USD 24.16 billion in 2026, and reach USD 33.33 billion by 2031, growing at a CAGR of 6.65% from 2026 to 2031.
This report is Segmented by Route of Administration (Oral & Enteral, Parenteral), Product Type (Standardized Enteral Formulas, and More), Application (Oncology, Metabolic Disorders, and More), End User (Infant, Pediatric, and More), Distribution Channel (Hospital Pharmacies, and More), and Country (Germany, United Kingdom, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Medical Clinical Nutrition Market Trends and Insights
Rising Prevalence of Chronic & Metabolic Disorders
Cancer cases climbed to 4.2 million in 2024 and cachexia now affects up to 80% of late-stage patients, prompting ESMO's 2025 protocol that pairs high-protein oral supplements with resistance exercise within 48 hours of diagnosis, improving six-month survival by 18%. Type 2 diabetes counts 62 million European adults, and EASD backs low-glycemic enteral formulas that hold post-prandial glucose 35% lower than polymeric alternatives. IBD prevalence exceeded 3.2 million in 2024; ECCO guidelines upgraded exclusive enteral nutrition to first-line pediatric Crohn's therapy, lifting remission to 65% and reshaping hospital formularies in Germany, France, and the Netherlands. Nephrologists now rely on renal-specific formulas to defer dialysis 12-18 months for 15% of adults with chronic kidney disease.
Aging Population & Escalating Healthcare Spend
Europe will host 150 million residents aged 65-plus by 2030; one-third of hospitalized seniors already present with protein-energy malnutrition, lengthening stays 4-6 days. ESPEN designated sarcopenia as a reimbursable condition in 2024, enabling high-protein oral nutrition supplement coverage across Germany, France, and the Netherlands. EU healthcare outlays reached EUR 1.8 trillion (USD 1.95 trillion) in 2024, but systematic nutrition screening cut total costs 12% through fewer complications. The NHS England framework mandated 24-hour malnutrition screening from April 2025 and standard prescription criteria for oral supplements, abolishing postcode disparities that had excluded 30% of qualifying patients.
Limited Patient / HCP Awareness of Clinical Nutrition
Malnutrition screening still reaches under 50% of admissions in Italy and Spain, leaving 40% of at-risk patients untreated. Only 35% of European general practitioners routinely prescribe oral nutrition supplements, citing limited product knowledge. Rural Portuguese uptake of validated tools such as MUST stands below 30% despite a national campaign that trained 5,000 physicians in 2025. Patient misconceptions persist; 70% of cancer patients in Italy and Spain do not know nutritional therapy can mitigate chemotherapy-related weight loss. Eastern Europe is further constrained by dietitian-to-patient ratios of 1:10,000 versus 1:2,500 in Western Europe.
Other drivers and restraints analyzed in the detailed report include:
- Home-Based Enteral Nutrition Adoption Surge
- ERAS-Driven Clinical-Nutrition Stewardship
- Complex EU Regulatory & Reimbursement Landscape
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Oral and enteral modalities retained 68.55% Europe medical clinical nutrition market share in 2025, anchored by ESPEN's "gut-first" doctrine that favors tube feeding whenever the intestine is functional. Early enteral delivery within 48 hours of ICU admission now covers 45% of patients and trims ventilator-associated pneumonia by 25%. Standard oral supplements dominate geriatric and oncology cohorts, supplying 60% of high-protein prescriptions.
Parenteral therapy is nevertheless accelerating at an 8.25% CAGR through 2031 as national insurers expand HPN coverage. Scandinavia's registries logged 12% annual growth and extended median catheter life to 26 months thanks to omega-3 lipid emulsions that curb occlusion. Fresenius Kabi's ready-to-infuse Numeta bags reduced preparation time from 45 to under five minutes and lowered compounding errors 70%, illustrating how innovation can reposition parenteral solutions for home environments.
Generic polymeric formulas held 45.53% of 2025 revenue, remaining the workhorse in mixed medical-surgical wards. Fiber-enriched versions now cut diarrhea 30% and improve glycemic profiles.
High-acuity care is tilting toward disease-specific blends. The Europe medical clinical nutrition market size for parenteral macronutrient solutions is on pace to advance 7.75% annually, powered by fourth-generation lipid emulsions licensed by the EMA in 2024-2025 that lower bloodstream infections 30%. Germany's insurer now reimburses 90% of these lipids, freeing ICUs from prior-authorization bottlenecks.
Complete Report Scope:
- By Route of Administration
- Oral & Enteral
- Parenteral
- By Product Type
- Standardised Enteral Formulas
- Disease-specific Enteral Formulas
- Parenteral Macronutrient Solutions
- By Application
- Oncology
- Metabolic Disorders
- Gastro-intestinal Diseases
- Neurological Disorders
- Other Diseases
- By End User
- Infant
- Pediatric
- Adult
- Geriatric
- By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Institutional / Tender Sales
- Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Abbott Laboratories
- Ajinomoto
- AYMES Nutrition
- B. Braun
- BASF
- Baxter
- Conmed
- Cook Group
- Danone
- Fresenius
- Haleon
- Medtrition
- Nestle
- Nualtra
- Otsuka
- Perrigo
- Vifor Pharma
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising prevalence of chronic & metabolic disorders
- 4.2.2 Ageing population & escalating healthcare spend
- 4.2.3 Home-based enteral nutrition adoption surge
- 4.2.4 ERAS-driven clinical-nutrition stewardship
- 4.2.5 AI-enabled personalised nutrient profiling
- 4.2.6 EU e-pharmacy liberalisation broadening D2C reach
- 4.3 Market Restraints
- 4.3.1 Limited patient / HCP awareness of clinical nutrition
- 4.3.2 Complex EU regulatory & reimbursement landscape
- 4.3.3 Volatile polymer & packaging input costs
- 4.3.4 Stricter macronutrient caps in specialised formulas
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Route of Administration
- 5.1.1 Oral & Enteral
- 5.1.2 Parenteral
- 5.2 By Product Type
- 5.2.1 Standardised Enteral Formulas
- 5.2.2 Disease-specific Enteral Formulas
- 5.2.3 Parenteral Macronutrient Solutions
- 5.3 By Application
- 5.3.1 Oncology
- 5.3.2 Metabolic Disorders
- 5.3.3 Gastro-intestinal Diseases
- 5.3.4 Neurological Disorders
- 5.3.5 Other Diseases
- 5.4 By End User
- 5.4.1 Infant
- 5.4.2 Pediatric
- 5.4.3 Adult
- 5.4.4 Geriatric
- 5.5 By Distribution Channel
- 5.5.1 Hospital Pharmacies
- 5.5.2 Retail Pharmacies
- 5.5.3 Online Pharmacies
- 5.5.4 Institutional / Tender Sales
- 5.6 Country
- 5.6.1 Germany
- 5.6.2 United Kingdom
- 5.6.3 France
- 5.6.4 Italy
- 5.6.5 Spain
- 5.6.6 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Abbott
- 6.3.2 Ajinomoto
- 6.3.3 AYMES Nutrition
- 6.3.4 B. Braun SE
- 6.3.5 BASF
- 6.3.6 Baxter International
- 6.3.7 Conmed Corp.
- 6.3.8 Cook Medical
- 6.3.9 Danone (Nutricia)
- 6.3.10 Fresenius Kabi
- 6.3.11 Haleon
- 6.3.12 Medtrition
- 6.3.13 Nestle Health Science
- 6.3.14 Nualtra
- 6.3.15 Otsuka Pharmaceutical
- 6.3.16 Perrigo
- 6.3.17 Vifor Pharma
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


