

|
시장보고서
상품코드
2113614
북미의 농약 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America Agrochemical - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
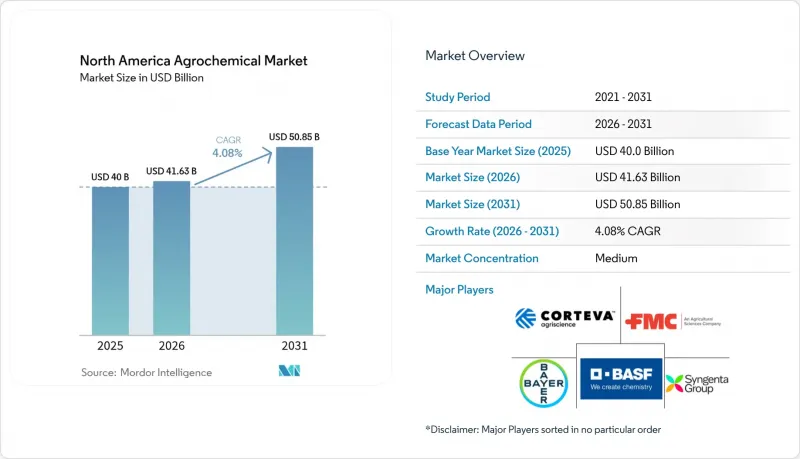
에 의하면, 북미의 농약 시장 규모는 2025년 400억 달러에서 2026년에는 416억 3,000만 달러에 이르고, 2026-2031년 CAGR 4.08%로 성장을 지속하여 2031년에는 508억 5,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 유형별(비료, 농약, 보조제, 식물 생장 조절제), 용도별(곡물, 콩류·유지종자, 과일 및 채소, 잔디 및 관상용 식물, 기타 용도), 지역별(미국, 캐나다, 멕시코, 기타 북미)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
북미의 농약 시장 동향 및 인사이트
작물 수확량 향상에 대한 수요 증가
미국 농무부는 2030년까지 식량 수요를 충족시키기 위해서는 옥수수 생산성을 연평균 1.2% 증가시켜야할 것으로 예측했습니다. 밭 시험을 통해 식물 성장 조절제, 특히 ‘Ascend 2’가 옥수수 수확량을 1에이커당 3부셸 증가시킨다는 사실이 입증되었습니다. 정밀 살포 기술과 결합하여 영양분 손실을 줄이는 동시에 탄소 크레딧 프로그램 참여를 촉진합니다. 미국 중서부 및 캐나다 프레리 지역의 농업 생산자들은 수확량 향상을 위한 이러한 기술을 도입하고 있으며, 수확량의 소폭 향상도 실질적인 수익 증가로 이어집니다. 이러한 시장 역학에 따라 제조업체들은 기존의 생산성 수준을 유지하는 것보다, 정량적으로 측정 가능한 수확량 향상을 가져오는 제제의 연구 개발에 주력하고 있습니다.
정부의 농약 구매 보조금 프로그램
북미 전역에서 정부의 재정 지원 정책을 통해 현대적인 농업 자재 도입 장벽이 낮아지고 있습니다. 2024년, 미국 농무부는 가격 변동을 억제하고 수입 의존도를 낮추기 위해 국내 비료 생산 확대를 위해 2억 3,600만 달러를 배정했습니다. 멕시코에서는 정부 프로그램이 지속 가능한 작물 보호 제품을 지원하고 있어, 글리포세이트 사용 제한에도 불구하고 수요가 유지되고 있습니다. 캐나다의 각 주에서는 가변 시비율 대응 살포 장비 및 토양 검사 서비스 등 정밀 농업 기술에 대한 비용 분담 프로그램을 시행하고 있습니다. 이러한 보조금은 농가의 투입 비용을 효과적으로 절감하는 동시에, 정밀 농업 장비 및 특수 농약의 투자 회수 기간을 단축함으로써 첨단 기술의 도입을 촉진하고 있습니다.
미국 환경보호청(EPA)의 엄격한 재등록 요건
제품 1개당 4,875달러의 연간 유지비와 강화된 생태학적 평가로 인해 규정 준수 비용이 증가하고 있으며, 이는 소규모 등록자에게 영향을 미쳐 제품 시장 철수로 이어지고 있습니다. ‘제초제 전략’의 시행에 따라 900종이 넘는 멸종 위기 종에 대한 완화 조치가 필요해졌으며, 여기에는 살포 제한 및 완충 지대 요건이 포함되어 제품의 사용 패턴에 영향을 미치고 있습니다. 2024년 10월, 유지비 미납으로 인해 ‘연방 살충제·살균제·살쥐제법’ 제3조에 근거한 등록 131건 및 동법 제24조(c)에 근거한 등록 44건이 취소되었습니다. 2022년 농약 등록 개선법에서는 두 가지 언어로 된 표시가 의무화되어 있으며, 고독성 제품의 경우 2025년까지, 모든 농약 라벨의 경우 2030년까지 건강 및 안전 관련 항목의 스페인어 번역이 필수입니다.
부문 분석
2025년 현재, 비료는 북미의 농약 시장 점유율의 45.75%를 차지하고 있으며, 주요 옥수수, 대두, 밀 생산 지역의 영양 관리에서 필수적인 위치를 유지하고 있습니다. 서방형 메커니즘을 갖춘 고효율 비료는 탄소 크레딧 제도 및 정밀 살포 장비와의 호환성을 통해 시장 점유율을 확대되고 있습니다. 디지털 토양 매핑을 통해 공급업체는 맞춤형 혼합물을 제공할 수 있게 되었으며, 전체 판매량은 정체 상태임에도 불구하고 1메트르톤당 수익은 증가하고 있습니다.
보조제는 2031년까지 연평균 성장률(CAGR)이 6.18%에 달하고, 북미의 농약 시장에서 가장 빠르게 성장하는 부문입니다. 이러한 성장은 드리프트를 최소화하고 엽면 흡수를 개선하는 살포 품질 향상제에 대한 수요 증가에 기인합니다. 이러한 성장은 드론 및 자율 살포기 기술의 채택 확대와 상관관계가 있으며, 이러한 기술은 운반 액체량이 적기 때문에 특수한 계면활성제가 필요합니다. 시장 점유율은 작지만, 규제 요건에서 살포의 명중 정확도 향상이 중시되고 있기 때문에 보조제는 한 자릿수 중반대의 CAGR을 달성하며 농약이나 비료를 상회하고 있습니다. 농약은 여전히 2위 제품 카테고리로서의 지위를 유지하고 있으며, 제초제 내성 작물의 보급과 잡초 방제 수요로 인해 제초제가 주류를 이루고 있습니다. 식물 성장 조절제는 여전히 전문성이 높은 부문이며, WinField United사의 ‘Ascend 2’와 같은 제품은 옥수수 수확량을 1에이커당 3부셸 증가시켜, 시장 침투율은 제한적이지만 프리미엄 가격 책정을 뒷받침하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.08.25According to Mordor Intelligence, the North America agrochemical market size is expected to grow from USD 40.0 billion in 2025 to USD 41.63 billion in 2026 and is forecast to reach USD 50.85 billion by 2031 at 4.08% CAGR over 2026-2031.
This report is Segmented by Type (Fertilizers, Pesticides, Adjuvants, and Plant Growth Regulators), by Application (Grains and Cereals, Pulses and Oilseeds, Fruits and Vegetables, Turfs and Ornamentals, and Other Applications), and by Geography (United States, Canada, Mexico, and Rest of North America). The Market Forecasts are Provided in Terms of Value (USD).
North America Agrochemical Market Trends and Insights
Rising Demand for Higher Crop Yields
The United States Department of Agriculture projects that corn productivity must increase by 1.2% annually to meet food demand by 2030. Field trials demonstrate that plant-growth regulators, specifically Ascend 2, increase corn yields by 3 bushels per acre. The combination of precision application techniques reduces nutrient losses while facilitating participation in carbon-credit programs. Agricultural producers across the Midwest United States and Canadian Prairies implement these yield-enhancing technologies, as incremental percentage improvements translate to substantial revenue increases. This market dynamic influences manufacturers to focus research and development on formulations that provide quantifiable yield improvements rather than maintaining existing productivity levels.
Government Agrochemicals Purchase Subsidy Programs
Government funding initiatives are reducing barriers to adopting modern agricultural inputs across North America. In 2024, the United States Department of Agriculture allocated USD 236 million to increase domestic fertilizer production, aiming to reduce price volatility and decrease import dependency. In Mexico, government programs support sustainable crop protection products, maintaining demand despite glyphosate limitations. Canadian provinces implement cost-sharing programs for precision agriculture technologies, including variable rate application equipment and soil testing services. These subsidies effectively reduce farmers' input costs and facilitate the adoption of advanced technologies by shortening the return on investment period for precision equipment and specialized agricultural chemicals.
Stringent Environmental Protection Agency (EPA) Re-Registration Requirements
The annual maintenance fees of USD 4,875 per product and enhanced ecological assessments increase compliance costs, affecting smaller registrants and leading to product withdrawals. The implementation of the Herbicide Strategy necessitates mitigation measures for over 900 endangered species, which include application restrictions and buffer zone requirements that impact product usage patterns. In October 2024, 131 Federal Insecticide, Fungicide, and Rodenticide Act section 3 registrations and 44 Federal Insecticide, Fungicide, and Rodenticide Act section 24(c) registrations were cancelled due to non-payment of maintenance fees. The Pesticide Registration Improvement Act of 2022 requires bilingual labeling, with Spanish translations for health and safety sections mandatory by 2025 for high-toxicity products and for all pesticide labels by 2030.
Other drivers and restraints analyzed in the detailed report include:
- Precision Farming Driving Optimized Inputs
- Carbon-Credit Linked Enhanced-Efficiency Agrochemicals
- Consumer Push for Residue-Free Produce
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fertilizers hold 45.75% of the North America agrochemical market share in 2025, maintaining their essential position in nutrient management across major corn, soybean, and wheat production areas. Enhanced-efficiency fertilizers, featuring controlled-release mechanisms, gain market share through their compatibility with carbon-credit programs and precision application equipment. Digital soil-mapping enables suppliers to offer customized blends, increasing revenue per metric ton despite stable overall volumes.
Adjuvants represent the fastest-growing segment in the North American agrochemical market, with a 6.18% CAGR through 2031. This growth stems from rising demand for spray-quality enhancers that minimize drift and improve foliar absorption. The growth correlates with increased adoption of drone and autonomous sprayer technologies, which require specialized surface-active agents due to lower carrier volumes. Despite their smaller market share, adjuvants achieve mid-single-digit CAGR, exceeding pesticides and fertilizers, as regulatory requirements emphasize improved spray deposition accuracy. Pesticides maintain their position as the second-largest product category, with herbicides predominant due to widespread herbicide-tolerant crop adoption and weed control needs. Plant growth regulators remain a specialized segment, with products like WinField United's Ascend 2 delivering corn yield increases of 3 bushels per acre, supporting premium pricing despite limited market reach.
Complete Report Scope:
- By Product Type
- Fertilizers
- Nitrogenous
- Phosphatic
- Potassic
- Other Fertilizers
- Pesticides
- Herbicides
- Insecticides
- Fungicides
- Other Pesticides
- Adjuvants
- Plant Growth Regulators
- Fertilizers
- By Application
- Grains and Cereals
- Pulses and Oilseeds
- Fruits and Vegetables
- Turfs and Ornamentals
- Other Applications
- By Geography
- United States
- Canada
- Mexico
- Rest of North America
List of Companies Covered in this Report:
- Syngenta Group
- Bayer AG
- Corteva Agriscience
- BASF SE
- FMC Corporation
- UPL Limited
- Nutrien Ltd.
- The Mosaic Company
- CF Industries Holdings, Inc.
- Yara International ASA
- Sumitomo Chemical America, Inc.
- ICL Group Ltd.
- Nufarm Limited
- Haifa Chemicals Ltd.
- Helena Agri-Enterprises, LLC (Marubeni Corporation)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Higher Crop Yields
- 4.2.2 Government Agrochemicals Purchase Subsidy Programs
- 4.2.3 Precision Farming Driving Optimized Inputs
- 4.2.4 Rising Pest Resistance and Demand for Modified Solutions
- 4.2.5 Carbon-Credit Linked Enhanced-Efficiency Agrochemicals
- 4.2.6 Expansion of Specialty Micronutrient Blends
- 4.3 Market Restraints
- 4.3.1 Stringent Environmental Protection Agency (EPA) Re-Registration Requirements
- 4.3.2 Escalating Research and Development and Registration Costs
- 4.3.3 Consumer Push for Residue-Free Produce
- 4.3.4 Biological Solutions Displacing Conventional Chemicals
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of Substitutes
- 4.6.4 Threat of New Entrants
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Fertilizers
- 5.1.1.1 Nitrogenous
- 5.1.1.2 Phosphatic
- 5.1.1.3 Potassic
- 5.1.1.4 Other Fertilizers
- 5.1.2 Pesticides
- 5.1.2.1 Herbicides
- 5.1.2.2 Insecticides
- 5.1.2.3 Fungicides
- 5.1.2.4 Other Pesticides
- 5.1.3 Adjuvants
- 5.1.4 Plant Growth Regulators
- 5.1.1 Fertilizers
- 5.2 By Application
- 5.2.1 Grains and Cereals
- 5.2.2 Pulses and Oilseeds
- 5.2.3 Fruits and Vegetables
- 5.2.4 Turfs and Ornamentals
- 5.2.5 Other Applications
- 5.3 By Geography
- 5.3.1 United States
- 5.3.2 Canada
- 5.3.3 Mexico
- 5.3.4 Rest of North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global-Level Overview, Market-Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Syngenta Group
- 6.4.2 Bayer AG
- 6.4.3 Corteva Agriscience
- 6.4.4 BASF SE
- 6.4.5 FMC Corporation
- 6.4.6 UPL Limited
- 6.4.7 Nutrien Ltd.
- 6.4.8 The Mosaic Company
- 6.4.9 CF Industries Holdings, Inc.
- 6.4.10 Yara International ASA
- 6.4.11 Sumitomo Chemical America, Inc.
- 6.4.12 ICL Group Ltd.
- 6.4.13 Nufarm Limited
- 6.4.14 Haifa Chemicals Ltd.
- 6.4.15 Helena Agri-Enterprises, LLC (Marubeni Corporation)


