

|
시장보고서
상품코드
2113706
인도네시아의 농약 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Indonesia Agrochemicals - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
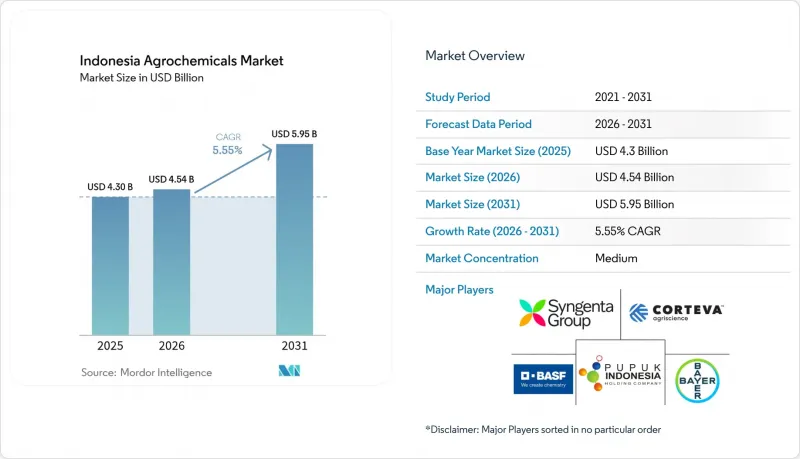
에 의하면, 인도네시아의 농약 시장 규모는 2025년 43억 달러로 평가되었습니다. 2026년에는 45억 4,000만 달러로 확대되어 2026년부터 2031년에 걸쳐 CAGR 5.55%로 성장을 지속하여, 2031년까지 59억 5,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 유형별(비료, 농약, 보조제, 식물 생장 조절제) 및 용도별(곡물, 콩류·유지종자, 과일 및 채소, 상업 작물)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
인도네시아의 농약 시장 동향 및 인사이트
정부의 비료 보조금 및 전자 바우처 지급
인도네시아의 비료 보조금 프로그램으로 인해, 보조금 대상인 영양 혼합 비료와 프리미엄 배합 비료가 경쟁하는 이중 시장이 형성되었습니다. 모바일 플랫폼을 통한 디지털 배급으로 대상 선정의 정확성과 투명성이 향상되었으며, 공급업체는 지역의 재배 요건에 맞춘 제품을 제공할 수 있게 되었습니다. 이 시스템은 기초 비료에 대한 안정적인 수요를 유지하고 농가의 국내 생산자에 대한 충성도를 높이는 한편, 국제 기업들에게 차별화된 배합 및 고성능 코팅 기술 개발을 촉진하고 있습니다. 동자바주는 보조금 수혜가 가장 많은 지역이며, 유통 네트워크는 주요 도시권을 중심으로 전개되어 있습니다. 보조금은 쌀 등 주곡 작물에 중점을 두고 있기 때문에 특수 자재 공급업체는 보조금 대상에서 제외된 원예 지역을 지원하기 위해 접근 방식을 조정해야 합니다. 이 프로그램은 가격 안정을 유지하는 동시에, 농약 업계에서 정부와의 협력이 얼마나 중요한지를 여실히 보여주고 있습니다.
국내 비료 생산 능력 확대
인도네시아는 비료 생산 인프라에 대규모 투자를 진행하고 있으며, 여기에는 각지의 신규 시설 건설 및 기존 시설 개보수가 포함됩니다. 이러한 확장은 수입 의존도를 낮추고, 특히 역사적으로 물류 문제를 겪어 온 외딴 섬에 대한 공급망 효율화를 도모하는 것을 목적으로 합니다. 생산량 증가에 따라 표준 비료 등급에서의 경쟁이 격화되고 있으며, 제조업체들은 이익률 향상을 위해 부가가치가 높은 배합에 주력하도록 유도되고 있습니다. 이러한 확대로 인해 업스트림 공정의 화학 성분에 대한 수요가 증가하여, 국제적인 특수 화학제품 공급업체들에게 비즈니스 기회가 창출되고 있습니다. 추가된 생산 능력은 생산 비용 절감과 프리미엄 카테고리로 시장 세분화를 촉진함으로써 시장 역학에 영향을 미칠 것으로 예측됩니다.
위조 및 불법 농약 유입
인도네시아 농업 부문은 시장에 유입되는 무허가 농약 제품으로 인해 심각한 문제에 직면해 있습니다. 많은 경우, 유명 브랜드를 모방한 이러한 불법 농약은 농가의 신뢰를 훼손하고 정식 유통망을 혼란에 빠뜨리고 있습니다. 기업들은 브랜드의 진위성을 유지하기 위해 위조 방지 포장 및 디지털 추적 시스템과 같은 보호 조치에 대한 투자를 강화하고 있습니다. 인도네시아의 해상 국경은 물류상의 복잡성과 법 집행상의 제약으로 인해 여전히 불법 수입의 침투에 취약한 상태입니다. 업계 관계자와 규제 당국이 협력하여 관리 및 법 집행 조치를 강화하고 있음에도 불구하고, 시장의 혼란은 계속되고 있습니다. 각 기업은 시장의 신뢰를 유지하고 매출을 보호하기 위해 소매점 점검 및 농가를 대상으로 한 인식 제고 프로그램 등의 예방 조치를 시행하고 있습니다.
부문 분석
2025년, 인도네시아의 농약 시장 규모 중 비료가 62.35%를 차지했습니다. 정부의 보조금으로 인해 수요는 안정적이지만, 시장의 상품화가 진행됨에 따라 제조업체들은 이익률 향상을 위해 코팅형, 서방형 및 미량 영양소를 강화한 제품 개발을 추진하고 있습니다. 국내 생산 능력 확대에 따라 기존 비료 제조업체들은 신기술 확보를 위해 특수 화학 기업과 제휴하고 있습니다. 농약은 여전히 2위 부문이며, 내성 관리가 유효 성분의 다양화와 스튜어드십 프로그램 추진을 뒷받침하고 있습니다. 살균제 및 보조제는 꾸준한 성장을 보이고 있으며, 특히 성능과 적합성이 필수적인 고빈도 살포 지역에서 두드러집니다.
식물 성장 조절제는 시장 점유율은 작지만, 수확의 균일화를 위해 호르몬 제제가 필요한 정밀 농업 및 관리 재배 기법에 힘입어 연평균 성장률(CAGR) 8.05%라는 가장 높은 성장률을 보이고 있습니다. 현재 다국적 기업들은 종합적인 작물 관리 솔루션을 제공하기 위해 생장 조절제 및 보조제를 농약 제품과 결합하고 있습니다. 등록 기간의 장기화는 진입 장벽이 되어 기존 기업에게는 유리하지만, 새로운 제제의 도입을 제한하고 있습니다. 시장에서 성공하기 위해서는 규제를 엄격히 준수하고, 진화하는 농업의 요구에 대응할 수 있는 유연한 연구 역량이 요구됩니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.26According to Mordor Intelligence, the Indonesia agrochemicals market size is expected to grow from USD 4.3 billion in 2025 to USD 4.54 billion in 2026 and is forecast to reach USD 5.95 billion by 2031 at 5.55% CAGR over 2026-2031.
This report is Segmented by Type (Fertilizers, Pesticides, Adjuvants, and Plant Growth Regulators) and by Application (Cereals and Grains, Pulses and Oilseeds, Fruits and Vegetables, and Commercial Crops). The Market Forecasts are Provided in Terms of Value (USD).
Indonesia Agrochemicals Market Trends and Insights
Government Fertilizer Subsidies and E-voucher Distribution
Indonesia's fertilizer subsidy program has created a dual-tier market where subsidized nutrient blends compete with premium formulations. The digital delivery through mobile platforms improves targeting and transparency, allowing suppliers to match products with regional cropping requirements. This system maintains steady demand for basic fertilizers and increases farmer loyalty to domestic producers, while encouraging international companies to develop differentiated blends and enhanced coatings. East Java receives the largest share of subsidies, with distribution networks centered around major urban areas. As the subsidy focuses on staple crops like rice, suppliers of specialty inputs must modify their approaches to serve horticultural zones outside the subsidy coverage. The program maintains price stability and highlights the importance of government collaboration in the agrochemical industry.
Expansion of Domestic Fertilizer Capacity
Indonesia's significant investment in fertilizer production infrastructure includes new facilities and upgrades across various regions. This expansion aims to decrease import dependence and enhance supply chain performance, particularly to remote islands with historical logistics challenges. The higher production volume increases competition in standard fertilizer grades, encouraging manufacturers to focus on value-added formulations for better profit margins. The expansion increases demand for upstream chemical components, creating opportunities for international specialty chemical suppliers. The additional capacity will influence market dynamics by reducing production costs and promoting market segmentation into premium categories.
Counterfeit and Illegal Pesticide Inflow
The Indonesian agricultural sector faces significant challenges from unauthorized agrochemical products entering the market. These illicit pesticides, which often mimic established brands, negatively impact farmer trust and disrupt authorized distribution networks. Companies have increased their investments in protective measures, including tamper-evident packaging and digital tracking systems, to maintain brand authenticity. The country's maritime borders remain susceptible to illegal imports due to logistical complexities and enforcement limitations. While industry participants and regulatory authorities work together to strengthen controls and enforcement measures, market disruptions continue. Companies are implementing preventive strategies, including retail outlet inspections and farmer awareness programs, to maintain market confidence and protect sales.
Other drivers and restraints analyzed in the detailed report include:
- Accelerating Mechanized Paddy Conversion Drives
- Chemical Use Surge in Horticulture Export Targets
- Growing Smallholder Shift to Organic Certifications
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fertilizers contributed 62.35% of Indonesia's agrochemicals market size in 2025. Government subsidies maintain consistent demand, while market commoditization has prompted manufacturers to develop coated, slow-release, and micronutrient-enriched products for improved margins. The expansion of domestic production capacity has led traditional fertilizer manufacturers to partner with specialty chemical companies to access new technologies. Pesticides remain the second-largest segment, with resistance management driving diversification in active ingredients and stewardship programs. Fungicides and adjuvants show steady growth, particularly in high-frequency application areas where performance and compatibility are essential.
Plant growth regulators, despite their small market share, demonstrate the highest growth rate at 8.05% CAGR, supported by precision farming practices and controlled cultivation methods that require hormonal products for harvest uniformity. Multinational companies now combine regulators and adjuvants with pesticide products to provide comprehensive crop management solutions. Extended registration periods create barriers to entry, benefiting established companies but limiting the introduction of new formulations. Market success requires strong regulatory compliance and adaptable research capabilities to address evolving agricultural needs.
Complete Report Scope:
- By Type
- Fertilizers
- Nitrogenous
- Phosphatic
- Potassic
- Other Fertilizers
- Pesticides
- Herbicides
- Insecticides
- Fungicides
- Other Pesticides
- Adjuvants
- Plant Growth Regulators
- Fertilizers
- By Application
- Cereals and Grains
- Pulses and Oilseeds
- Fruits and Vegetables
- Commercial Crops
List of Companies Covered in this Report:
- Bayer AG
- Syngenta Group
- Corteva Agriscience
- BASF SE
- FMC Corporation
- UPL Limited
- Yara International ASA
- PT. Sumitomo Indonesia
- PT. Pupuk Indonesia
- PT. Sentana Adidaya Pratama (Wilmar International)
- PT. Multi Mas Chemindo
- PT. Meroke Tetap Jaya
- PT. Asia Kimindo Prima
- PT. Mest Indonesiy (Mestindo Group)
- Grupa Azoty S.A. (Compo Expert)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government Fertilizer Subsidies and E-voucher Distribution
- 4.2.2 Expansion of Domestic Fertilizer Capacity
- 4.2.3 Accelerating Mechanized Paddy Conversion Drives
- 4.2.4 Chemical Use Surge in Horticulture Export Targets
- 4.2.5 AI-enabled Crop Advisory Apps Boosting Agrochemicals Intensity
- 4.2.6 Palm-oil By-product Plant Growth Regulators Gaining Regulatory Fast-track
- 4.3 Market Restraints
- 4.3.1 Counterfeit and Illegal Pesticide Inflow
- 4.3.2 Growing Smallholder Shift to Organic Certifications
- 4.3.3 Herbicide-resistant Weed Outbreaks
- 4.3.4 El-Nino Induced Fertilizer Price Shocks
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Fertilizers
- 5.1.1.1 Nitrogenous
- 5.1.1.2 Phosphatic
- 5.1.1.3 Potassic
- 5.1.1.4 Other Fertilizers
- 5.1.2 Pesticides
- 5.1.2.1 Herbicides
- 5.1.2.2 Insecticides
- 5.1.2.3 Fungicides
- 5.1.2.4 Other Pesticides
- 5.1.3 Adjuvants
- 5.1.4 Plant Growth Regulators
- 5.1.1 Fertilizers
- 5.2 By Application
- 5.2.1 Cereals and Grains
- 5.2.2 Pulses and Oilseeds
- 5.2.3 Fruits and Vegetables
- 5.2.4 Commercial Crops
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Bayer AG
- 6.4.2 Syngenta Group
- 6.4.3 Corteva Agriscience
- 6.4.4 BASF SE
- 6.4.5 FMC Corporation
- 6.4.6 UPL Limited
- 6.4.7 Yara International ASA
- 6.4.8 PT. Sumitomo Indonesia
- 6.4.9 PT. Pupuk Indonesia
- 6.4.10 PT. Sentana Adidaya Pratama (Wilmar International)
- 6.4.11 PT. Multi Mas Chemindo
- 6.4.12 PT. Meroke Tetap Jaya
- 6.4.13 PT. Asia Kimindo Prima
- 6.4.14 PT. Mest Indonesiy (Mestindo Group)
- 6.4.15 Grupa Azoty S.A. (Compo Expert)


