

|
시장보고서
상품코드
2115833
유럽의 자동차 유리 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Automotive Glass - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
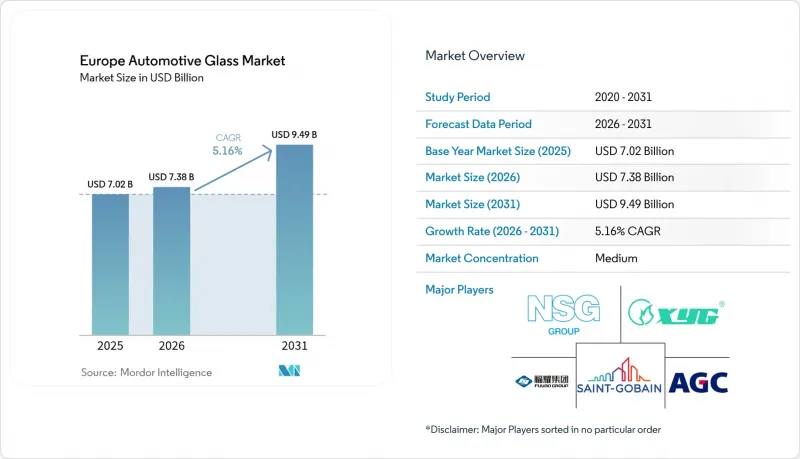
에 따르면 유럽의 자동차 유리 시장 규모는 2025년에 70억 2,000만 달러로 평가되며, 2026년 73억 8,000만 달러에서 2031년까지 94억 9,000만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 5.16%가 될 전망입니다.
본 보고서는 유리 종류(일반 유리 및 스마트 유리), 용도(전면 유리, 후면 유리 등), 차종(승용차 등), 구동 방식(내연기관(ICE) 등), 판매 채널(OEM 및 애프터마켓), 지역(독일, 영국, 프랑스 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽 자동차 유리 시장의 동향 및 인사이트
유럽에서 스포츠 유틸리티 차량(SUV) 및 크로스오버 차량의 신차 출시와 관련하여 파노라마 선루프 및 더 넓은 유리 면적의 채택이 급속히 진행되고 있습니다.
스포츠 유틸리티 차량(SUV) 및 크로스오버 차량의 신차 출시에서, 실내 공간의 넓음을 느끼게 하고 프리미엄 옵션으로서의 가격 책정이 요구되는 루프 글라스의 채택이 점점 더 증가하고 있습니다. 독일, 프랑스, 영국의 OEM에서는 소형 및 중형 SUV가 신규 등록 대수에서 높은 비중을 차지했습니다. 유리 면적의 확대는 차내 열 유입량을 증가시키기 때문에 공급업체들은 일사열 부하를 관리하기 위해 적외선을 흡수하는 PVB를 사용한 다층 적층 유리의 채택을 요구받고 있습니다. 또한, 유리 면적 확대에 따라 루프 프레임의 강성 향상도 필요해짐에 따라, 유리 제조사와 차체 엔지니어 간의 설계 협력이 진전되고 있습니다. 스위치 가능한 고분자 분산형 액정(PDLC) 패널은 소재 가격 하락에 따라 고급차 브랜드에서 상위 중형급 모델로 보급이 확대되고 있습니다. 중기적으로는 파노라마 글라스 루프에 태양전지가 탑재되어 액세서리용 배터리로 트리클 충전이 가능해질 것으로 예상되며, 차량 1대당 유리 면적당 부가가치가 더욱 높아질 것으로 전망됩니다.
고도의 적층 구조 및 HUD 대응 전면 유리를 의무화하는 EU 차량 안전 규정
유엔 규정 제43호에서는 탑승자의 차량 외부 방출 위험을 줄이기 위해 모든 카테고리에서 적층식 전면 유리의 채택이 의무화되어 있습니다. 한편, Euro NCAP의 2025년 로드맵에서는 HUD 기능을 내장한 전면 유리에 대해 추가 안전 점수가 부여됩니다. 이러한 규제로 인해 개발 주기가 단축되며, 카메라 마운트 및 반사 코팅에 대응하는 중간막을 공동 개발할 수 있는 공급업체가 유리한 입지를 차지하게 됩니다. OEM 엔지니어링 팀은 전방 감시 센서의 광학적 투명도를 유지하기 위해 0.2mm 미만의 더욱 엄격한 전면 유리 곡률 공차를 설계에 반영하고 있습니다. 또한, 이러한 규제로 인해 애프터마켓에서의 교체 작업이 복잡해지고 있어, 사내에 검증 실험실을 갖춘 1차 공급업체의 경우 설계 단계부터 진입할 때의 이점이 더욱 커지고 있습니다. 센서 스위트의 보급에 따라 2030년까지 HUD 지원 유리가 C부문 차량의 대부분에 기본 사양으로 장착될 전망입니다.
스마트/첨단 유리의 높은 생산 및 통합 비용이 대중 시장 부문에서의 보급을 제한
일렉트로크로믹 및 SPD 시스템은 차량당 약 300-800유로(353-941.5달러)의 비용 증가를 초래하지만, 이 차액을 가격 경쟁을 통해 상쇄하는 것은 양산차 제조사에게 어려운 과제가 되고 있습니다. 유기 일렉트로크로믹 필름은 더 단순한 적층 구조를 가능하게 하지만, 기밀 밀봉 문제에 직면해 있어 이로 인해 수율이 저하되고 있습니다. 폴란드, 스페인, 이탈리아의 주요 브랜드들은 비용 절감 프로그램을 우선시하고 있어 도입은 플래그십 등급으로 한정되어 있습니다. 이러한 제약으로 인해 소비자의 인지도는 높아지고 있음에도 불구하고 보급 속도는 둔화되고 있으며, 2027년까지 프리미엄 부문 이외의 시장에서 보급률은 낮은 수준에 머물 것으로 전망됩니다. 장기적으로는 대량 생산 확대와 소재 기술의 비약적인 발전을 통해 비용을 절감하고, 대량 생산 플랫폼으로의 확장을 실현해야 합니다.
부문 분석
2025년에는 일반 접합유리 및 강화유리가 매출의 60.85%를 차지했습니다. 이는 내구성과 비용 효율성이 입증된 전면 유리, 후면 유리, 측면 유리에의 채택이 주요 요인입니다. 유엔 규정 제43호에 따라 전면 유리의 접합 유리화가 의무화되어 있어, 이로 인해 기초적인 수요가 높은 수준을 유지하고 있으며, 유럽 자동차 유리 시장 규모 예측의 확실성을 뒷받침하고 있습니다. 사이드 글라스와 리어 글라스의 경우, 여전히 강화 유리가 표준으로 채택되고 있으며, 충격 시 빠르게 파손되는 특성은 탑승자의 탈출을 돕고 재활용 과정을 간소화합니다. 한편, 스마트 유리는 일렉트로크로믹, SPD, PDLC와 같은 기술이 럭셔리 자동차의 컨셉에서 양산 모델로 전환됨에 따라 연평균 성장률(CAGR) 6.03%로 급속히 확대되고 있습니다.
스마트 유리의 하위 부문에서는 일렉트로크로믹 솔루션이 수량 기준으로 주도적인 위치를 차지하고 있으며, 정밀한 착색 제어와 낮은 전력 소비로 폭넓은 지지를 받고 있습니다. 이러한 적층 구조에서는 전압을 가하면 어두워지는 산화 텅스텐 층 또는 리튬 이온 층을 채택하고 있어, 1% 단위로 무단계 조정이 가능합니다. SPD 필름은 전류가 흐를 때 부유 입자를 정렬시켜 투명화를 실현하며, 더 빠른 전환이 가능하지만 지속적인 전력 공급이 필요합니다. PDLC는 고급 MPV 및 라이드셰어용 셔틀의 프라이버시 윈도우로 주목받고 있습니다. 유럽의 자동차 유리 시장에서는 광학적 투명도나 방음 성능을 저해하지 않으면서 스마트 층을 통합할 수 있는 공급업체가 계속해서 높은 평가를 받고 있습니다.
앞유리는 그 크기와 카메라, 적외선 히터 메시, HUD 투사 필름 등을 포함한 내장 기술 스택 덕분에 2025년에는 매출의 46.55%를 차지했습니다. Euro NCAP의 2025년 프로토콜에서는 HUD 기능에 대해 점수가 부여되므로, 각 OEM 업체들은 소정의 굴절률에서 광투과율을 유지할 수 있는 적층 표면을 선호하는 경향이 강해지고 있습니다. ADAS 탑재 유리의 경우, 애프터마켓에서의 교체 비용이 상당히 비쌀 가능성이 있기 때문에 초기 장착(퍼스트 핏) 이외의 매출 잠재력이 확대되고 있습니다. 선루프는 자동차 제조사가 실내 공간의 넓이를 향상시키는 널찍한 유리를 사용하여 등급을 차별화하고 있기 때문에 연평균 성장률(CAGR) 5.62%로 성장할 것으로 예측됩니다. 전환 가능한 PDLC와 태양전지를 통합한 모듈은 최대 일사량 조건에서 최대 150W의 전력을 발전할 수 있어, 액세서리의 전력 부하를 분담하는 동시에 유럽 자동차 유리 시장에서 루프 용도의 점유율 확대에 기여하고 있습니다.
총 출하량의 약 3분의 1을 차지하는 백라이트 및 사이드라이트는 높아지는 방음성과 보안에 대한 기대에 부응하기 위해 강화유리에서 접합유리 구조로 전환되고 있습니다. 전동 파워트레인의 보급에 따라 새로운 소음원이 발생하고 있는 만큼, 방음성이 뛰어난 사이드라이트는 차량 내 환경을 개선하는 유력한 수단이 되고 있습니다. 미러는 면적은 작지만, 현재는 일렉트로크로믹 조광 기능이나 카메라 영상 표시 기능이 탑재되어 있으며, UNECE 규정 제46호에 따른 가상 미러 승인을 활용하고 있습니다. 쿼터 패널과 벤트 패널은 여전히 범용 제품이지만, 프리미엄 SUV에 적층 저소음 구역 유리가 채택됨에 따라 혜택을 보고 있습니다. 모든 용도에서 유럽 자동차 유리 시장에서는 코팅, 센서, 전자기기를 한 장의 유리에 통합한 다기능 설계가 높이 평가받고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.08.26According to Mordor Intelligence, the european automotive glass market size was valued at USD 7.02 billion in 2025 and estimated to grow from USD 7.38 billion in 2026 to reach USD 9.49 billion by 2031, at a CAGR of 5.16% during the forecast period (2026-2031).
This report is Segmented by Glass Type (Regular Glass and Smart Glass), Application (Windshield, Backlite, and More), Vehicle Type (Passenger Cars, and More), Propulsion (Internal Combustion Engine (ICE) and More), Sales Channel (Original Equipment Manufacturer (OEM) and Aftermarket), and Geography (Germany, UK, France, and More). Market Forecasts are Provided in Terms of Value (USD).
Europe Automotive Glass Market Trends and Insights
Rapid Adoption of Panoramic Sunroofs and Larger Glazing Areas in European Sport Utility Vehicle and Crossover Launches
Sport utility vehicle (SUV) and crossover launches increasingly specify roof glass that enlarges perceived cabin space and commands premium option pricing. OEMs in Germany, France, and the United Kingdom saw compact and mid-size SUVs lead the new-registration mix. Larger apertures lift interior heat gain, pushing suppliers toward multi-layer laminates with infrared-absorbing PVB to manage solar load. The additional area also necessitates stiffer roof frames, creating design collaboration between glassmakers and body engineers. Switchable polymer-dispersed-liquid-crystal (PDLC) panels are migrating from luxury nameplates into upper-mid trims as material prices fall. Over the medium term, panoramic glass roofs are expected to feature solar cells that trickle-charge accessory batteries, further increasing surface value per vehicle.
EU Vehicle Safety Regulations Mandating Advanced Laminated and HUD-Ready Windshields
UN Regulation No. 43 requires laminated windshields across all categories to reduce occupant ejection risk, while Euro NCAP's 2025 roadmap offers additional safety points for embedded HUD capability. These rules compress development cycles and favor suppliers that can co-engineer interlayers supporting camera mounts and reflective coatings. OEM engineering teams are incorporating windshield curvature tolerances tighter than 0.2 mm to maintain optical clarity for forward-looking sensors. The mandates also increase replacement complexity in the aftermarket, reinforcing design-in advantages for tier-one producers equipped with in-house validation labs. As sensor suites proliferate, HUD-ready glass is poised to become the baseline on most C-segment vehicles by 2030.
High Production and Integration Cost of Smart/Advanced Glazing Limiting Penetration in Mass-Market Segments
Electrochromic and SPD systems add approximately EUR 300-800 (USD 353 to 941.5) per vehicle, a delta that mass-market OEMs struggle to offset when competing on price. Organic electrochromic films promise simpler stacks yet face hermetic-sealing challenges that depress yield. Volume brands in Poland, Spain, and Italy prioritize cost-down programs, limiting deployment to flagship trims. The restraint moderates diffusion speed even as consumer awareness grows, keeping penetration below outside premium segments through 2027. Long-term, scale and material breakthroughs must cut costs to unlock high-volume platforms.
Other drivers and restraints analyzed in the detailed report include:
- Accelerating OEM Integration of Smart/Electrochromic Glass for Energy Efficiency and Occupant Comfort
- Lightweight Acoustic Glazing Demand Driven by EV Range Optimization Targets
- Skills Shortage for ADAS Windshield Calibration in Aftermarket Service Networks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Regular laminated and tempered variants commanded 60.85% revenue in 2025, driven by their use in windshields, backlites, and sidelites where proven durability and cost efficiency prevail. UN Regulation No. 43 mandates laminated windshields, keeping baseline demand high and supporting the Europe automotive glass market size predictability. Tempered glass continues as standard for sidelites and backlites; its rapid disintegration upon impact aids passenger egress and simplifies recycling streams. Smart glass, however, is accelerating at a 6.03% CAGR as electrochromic, SPD, and PDLC technologies migrate from luxury concepts into series production.
Electrochromic solutions lead the smart subset by volume and are widely favored for precise tint control and low power draw. These stacks employ tungsten-oxide or lithium-ion layers that darken under applied voltage, offering step-less modulation within one percent increments. SPD films align suspended particles to enable transparency when energized, delivering faster switching but requiring continuous power. PDLC is gaining traction for privacy windows in luxury MPVs and ride-sharing shuttles. The European automotive glass market continues to reward suppliers who can integrate smart layers without sacrificing optical clarity or acoustic damping.
Windshields held 46.55% revenue in 2025 because of their size and the embedded technology stack that now includes cameras, infrared heating meshes, and HUD projection foils. Euro NCAP's 2025 protocol awards points for HUD functions, reinforcing OEM preference for laminated surfaces able to maintain optical transmittance at defined refractive indices. Aftermarket replacement can cost significantly for ADAS-equipped panes, expanding revenue potential beyond first fit. Sunroofs are projected to grow at a 5.62% CAGR as automakers differentiate trims with expansive glass that improves perceived cabin space. Modules integrating switchable PDLC and solar cells can harvest up to 150 W under peak irradiance, contributing to accessory loads and boosting the European automotive glass market share for roof applications.
Backlites and sidelites, accounting for roughly one-third of volume, are transitioning from tempered to laminated construction to meet rising acoustic and security expectations. Electrified drivetrains reveal new noise sources, making acoustic sidelites a potent refinement tool. Mirrors, although small in area, now incorporate electrochromic dimming and camera feeds, capitalizing on UN Regulation No. 46's allowance for virtual mirrors UNECE. Quarter and vent panels remain commodity items yet benefit from adoption of laminated quiet-zone glass in premium SUVs. Across all applications, the Europe automotive glass market rewards multi-function designs that couple coatings, sensors, and electronics into a single pane.
Complete Report Scope:
- By Glass Type
- Regular Glass
- Laminated Glass
- Tempered Glass
- Smart Glass
- Electrochromic
- Suspended Particle Device (SPD)
- Polymer Dispersed Liquid Crystal (PDLC)
- Thermochromic
- Regular Glass
- By Application
- Windshield
- Backlite (Rear Window)
- Sidelite (Side Windows)
- Sunroof
- Rear-view and Side-view Mirrors
- Other Glazing (Quarter and Vent)
- By Vehicle Type
- Passenger Cars
- Hatchback
- Sedan
- Sport Utility Vehicle and Crossover
- Luxury and Sports
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Passenger Cars
- By Propulsion
- Internal Combustion Engine (ICE)
- Battery Electric Vehicle (BEV)
- Hybrid Electric Vehicle (HEV/PHEV)
- Fuel Cell Electric Vehicle (FCEV)
- By Sales Channel
- Original Equipment Manufacturer (OEM)
- Aftermarket
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Saint-Gobain Sekurit
- AGC Inc. (Asahi Glass)
- NSG Group (Pilkington)
- Fuyao Glass Industry Group Co., Ltd.
- Guardian Industries (PPG/Koch)
- Webasto SE
- Inalfa Roof Systems Group B.V.
- CIE Automotive
- Magna International Inc.
- Gentex Corporation
- Inteva Products
- Xinyi Glass Holdings Ltd.
- Vitro Automotive
- Sisecam Group
- Corning Incorporated
- Covestro AG
- Teijin Limited
- Smartglass International
- Gauzy Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Adoption of Panoramic Sunroofs and Larger Glazing Areas in European SUV and Crossover Launches
- 4.2.2 EU Vehicle Safety Regulations Mandating Advanced Laminated and HUD-Ready Windshields
- 4.2.3 Accelerating OEM Integration of Smart/Electrochromic Glass for Energy Efficiency and Occupant Comfort
- 4.2.4 Lightweight Acoustic Glazing Demand Driven by EV Range Optimization Targets
- 4.2.5 Supply-Chain Localization Incentives in Eastern Europe Reducing Lead-Time and Cost for OEM Glass Sourcing
- 4.2.6 Automotive Circular-Economy Mandates Pushing Recycled, Low-Carbon Glass Innovation
- 4.3 Market Restraints
- 4.3.1 High Production and Integration Cost of Smart/Advanced Glazing Limiting Penetration in Mass-Market Segments
- 4.3.2 Skills Shortage for ADAS Windshield Calibration in Aftermarket Service Networks
- 4.3.3 Volatility in Soda Ash and Energy Prices Impacting European Float-Glass Profitability
- 4.3.4 Stringent Europe End-of-Life Recycling Targets Raising Compliance Costs for Laminated Glass Recovery
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts
- 5.1 By Glass Type
- 5.1.1 Regular Glass
- 5.1.1.1 Laminated Glass
- 5.1.1.2 Tempered Glass
- 5.1.2 Smart Glass
- 5.1.2.1 Electrochromic
- 5.1.2.2 Suspended Particle Device (SPD)
- 5.1.2.3 Polymer Dispersed Liquid Crystal (PDLC)
- 5.1.2.4 Thermochromic
- 5.1.1 Regular Glass
- 5.2 By Application
- 5.2.1 Windshield
- 5.2.2 Backlite (Rear Window)
- 5.2.3 Sidelite (Side Windows)
- 5.2.4 Sunroof
- 5.2.5 Rear-view and Side-view Mirrors
- 5.2.6 Other Glazing (Quarter and Vent)
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.1.1 Hatchback
- 5.3.1.2 Sedan
- 5.3.1.3 Sport Utility Vehicle and Crossover
- 5.3.1.4 Luxury and Sports
- 5.3.2 Light Commercial Vehicles
- 5.3.3 Medium and Heavy Commercial Vehicles
- 5.3.1 Passenger Cars
- 5.4 By Propulsion
- 5.4.1 Internal Combustion Engine (ICE)
- 5.4.2 Battery Electric Vehicle (BEV)
- 5.4.3 Hybrid Electric Vehicle (HEV/PHEV)
- 5.4.4 Fuel Cell Electric Vehicle (FCEV)
- 5.5 By Sales Channel
- 5.5.1 Original Equipment Manufacturer (OEM)
- 5.5.2 Aftermarket
- 5.6 By Country
- 5.6.1 Germany
- 5.6.2 United Kingdom
- 5.6.3 France
- 5.6.4 Italy
- 5.6.5 Spain
- 5.6.6 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Saint-Gobain Sekurit
- 6.4.2 AGC Inc. (Asahi Glass)
- 6.4.3 NSG Group (Pilkington)
- 6.4.4 Fuyao Glass Industry Group Co., Ltd.
- 6.4.5 Guardian Industries (PPG/Koch)
- 6.4.6 Webasto SE
- 6.4.7 Inalfa Roof Systems Group B.V.
- 6.4.8 CIE Automotive
- 6.4.9 Magna International Inc.
- 6.4.10 Gentex Corporation
- 6.4.11 Inteva Products
- 6.4.12 Xinyi Glass Holdings Ltd.
- 6.4.13 Vitro Automotive
- 6.4.14 Sisecam Group
- 6.4.15 Corning Incorporated
- 6.4.16 Covestro AG
- 6.4.17 Teijin Limited
- 6.4.18 Smartglass International
- 6.4.19 Gauzy Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


