

|
시장보고서
상품코드
2115834
북미의 자동차 유리 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America Automotive Glass - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
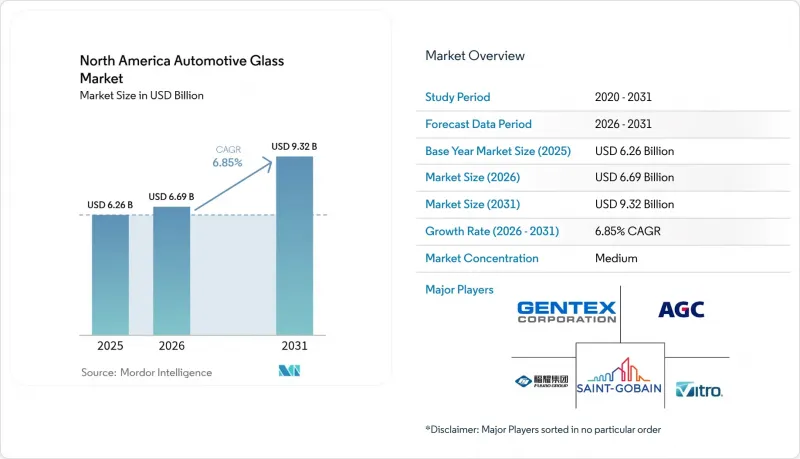
에 따르면 북미의 자동차 유리 시장 규모는 2025년 62억 6,000만 달러에서 2026년에는 66억 9,000만 달러로 확대되고, 2026년부터 2031년까지 CAGR 6.85%를 기록하며 2031년에는 93억 2,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 종류(접합 유리, 강화 유리 등), 용도(전면 유리, 측면 유리 등), 판매 채널(OEM 및 애프터마켓(교체·조정)), 차종(승용차, 소형 상용차 등), 국가(미국, 캐나다 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
북미 자동차 유리 시장의 동향 및 인사이트
프리미엄 등급에서의 스마트 유리/스위칭 유리의 급속한 보급
각 OEM 업체들이 차량 실내의 차별화를 꾀하는 가운데, 일렉트로크로믹 선루프, 조광 가능한 사이드 라이트, 그리고 유리 내 디스플레이는 고급차 전용에서 중상급 등급으로 확대되고 있습니다. 젠텍스(Gentex)는 연간 5,000만 개 이상의 조광 장치를 출하하고 있으며, 이는 비용 장벽을 낮추는 제조 기술의 성숙도를 보여줍니다. 필름 기반의 일렉트로크로믹 스택은 기존의 유리-유리-셀 구조에 비해 경량화를 실현하여, 스마트 글라스와 전기자동차(EV)의 주행 거리 목표를 동시에 달성하고 있습니다. 추가된 디지털 레이어는 헤드업 디스플레이 및 운전자 모니터링 센서를 지원하여, 제조사는 안전성과 인포테인먼트 기능을 일체화한 솔루션을 제공할 수 있게 되었습니다. 규제 당국이 운전자 모니터링 기술 도입을 권장하는 가운데, 스마트 글라스의 채택도 병행하여 증가하고 있어 북미 자동차 유리 시장을 강화하고 있습니다.
ADAS 재조정 서비스가 세트로 제공됨에 따라 교체 수요가 확대되고 있습니다
앞유리에 탑재된 카메라 기반 시스템은 유리 교체 후 재조정이 필요하며, 과거에는 단순한 작업이었던 것이 전자기기 서비스 점검으로 변화하고 있습니다. 보험사는 현재 인증된 절차를 요구하고 있어, 이에 따라 기술자에게 요구되는 기술 수준이 높아졌으며, 재조정 장비를 보유한 체인점은 추가 요금을 청구할 수 있게 되었습니다. 전면 유리 유닛의 작업 복잡도가 높아지고 있을 뿐만 아니라, 사이드 윈도우에 탑재된 보완적인 센서 모듈도 애프터마켓 라인업에 점차 포함되고 있습니다. 기술적 장벽이 높아짐에 따라 건당 수익이 향상되어, 자동차 보유 대수의 자연스러운 증가를 넘어 북미 자동차 유리 시장을 지속시키는 요인이 되고 있습니다.
소다회, PVB, EVA 중간막 가격 변동
세키스이 화학공업은 에너지 및 물류 비용 급등을 이유로 2024년 하반기에 PVB 가격을 6-15% 인상했습니다. 시세캄이 시너 그룹의 미국 소다회 자산을 인수함에 따라, 2030년까지 수요가 8,300만 톤으로 증가할 것으로 예상되는 가운데 공급이 집중되고 있습니다. 천연 소다회 광산이 한정되어 있고 전 세계 PVB 생산자가 소수에 불과하기 때문에 업스트림 공급업체에 가격 결정권이 생겨나고 있으며, 이는 플로트 유리의 이익률을 압박하고 가공업체로 하여금 헤지나 수직 통합을 강요하고 있습니다. 비용의 급격한 상승은 가격 전가가 지연될 경우 북미 자동차 유리 시장 전체의 수익성을 저해하게 될 것입니다.
부문 분석
북미 자동차 유리 시장에서 2025년 매출의 56.78%를 접합 유리가 차지했습니다. 이는 앞유리에서 필수적인 역할을 하는 것 외에도, 보안 및 방음성 향상을 목적으로 한 접합 유리 사이드라이트의 사용 확대가 배경에 있습니다. 일렉트로크로믹식 선루프가 더 다양한 차종에 채택됨에 따라, 스마트 유리 및 스위칭 유리는 연평균 성장률(CAGR) 8.28%로 성장하고 있습니다. 한때는 비용 측면에서 주류를 이루었던 강화유리는, 제조사들이 비용 절감과 높은 단열 성능을 추구함에 따라 중요도가 낮은 부위에서 점차 대체되고 있습니다. 한편, 배터리 주행 거리를 확보하기 위해 일사열 유입 억제가 요구되는 전기자동차(EV) 프로그램의 부양에 힘입어 코팅 유리 부문도 병행하여 확대되고 있습니다.
끊임없는 혁신이 이 부문의 성장세를 뒷받침하고 있습니다. 젠텍스(Gentex)사의 필름 기반 접근 방식은 두께를 줄이면서도 루프 모듈에 상당한 형상적 자유도를 제공하고 있습니다. 통합 디스플레이 기술은 눈부심 제어와 인포테인먼트 기능을 융합하여 유리 제조업체에 새로운 수익원을 개척하고 있습니다. 현재 접합 유리 구조에는 방음, 차열, 구조용 등 여러 중간층이 통합되어 있어, 단일 부품으로 안전성, 쾌적성, 에너지 효율을 모두 충족시킬 수 있게 되었습니다. 기술이 점점 더 복잡해짐에 따라 화학, 코팅, 전자 분야 기술력을 갖춘 공급업체들은 북미 자동차 유리 시장에서 입지를 더욱 공고히 하고 있습니다.
앞유리는 장착 의무 및 엄격한 충격 규제의 뒷받침을 받아 2025년 북미 자동차 유리 시장에서 48.10%의 점유율을 유지했습니다. 한편, 파노라마 루프가 주류 스타일링 요소로 자리 잡으면서, 선루프 및 루프라이트 모듈은 2031년까지 연평균 성장률(CAGR) 7.62%로 가장 높은 성장률을 기록할 전망입니다. 접합 유리로 제작된 루프 패널에는 일렉트로크로믹 조광 기능, 자외선 차단 기능 및 히터 그리드가 통합되어 있어, 불투명한 쉐이드를 추가하지 않고도 차량 내 환경을 개선합니다.
사이드라이트는 상위 트림에서 강화유리에서 접합유리로 전환되고 있으며, 방범 성능 향상과 실내 정숙성 향상을 실현하고 있습니다. 이러한 특징들은 거의 소음이 없는 전기자동차에서 높이 평가되는 특성입니다. 백라이트 출하량은 안정적이지만, 내장 안테나나 성에 제거 라인과 같은 스마트 기능이 서서히 진화하고 있습니다. 외부 미러 유리는 카메라 기반의 전자 미러로 전환되어 하드웨어 구성이 완전히 새로워지지만, 여전히 정밀하게 연마된 기판에 의존하고 있습니다. 개구부 확대와 다기능 코팅의 도입으로 기술적 난이도가 높아짐에 따라, 북미 자동차 유리 시장에서 각 OEM 업체들은 경험이 풍부한 유리 파트너에 대한 의존도를 더욱 강화하게 될 것입니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.08.26According to Mordor Intelligence, the North America automotive glass market size is expected to grow from USD 6.26 billion in 2025 to USD 6.69 billion in 2026 and is forecast to reach USD 9.32 billion by 2031 at 6.85% CAGR over 2026-2031.
This report is Segmented by Type (Laminated Glass, Tempered Glass, and More), Application (Windshield, Sidelite, and More), Sales Channel (OEM and Aftermarket (Replacement and Calibration)), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), and Country (United States, Canada, and More). The Market Forecasts are Provided in Terms of Value (USD).
North America Automotive Glass Market Trends and Insights
Rapid adoption of smart/switchable glass in premium trims
Electrochromic sunroofs, dimmable sidelites, and in-glass displays are crossing from luxury badges into upper-mid trims as OEMs seek cabin differentiation. Gentex ships more than 50 million dimmable devices annually, demonstrating manufacturing maturity that lowers cost barriers. Film-based electrochromic stacks trim weight compared with traditional glass-glass cell construction, aligning smart glazing with EV range targets. Added digital layers accommodate heads-up images and driver-monitoring sensors, letting manufacturers bundle safety and infotainment. As regulatory bodies encourage driver-monitoring technology, smart glass adoption rises in parallel, strengthening the North America automotive glass market.
Bundled ADAS recalibration services boosting replacement demand
Camera-based systems mounted on windshields must be recalibrated after glass replacement, turning a once-simple job into an electronics service visit. Insurers now require certified procedures, raising the skill floor for technicians and allowing chains that own calibration equipment to charge premiums. Windshield units grow in billable complexity, and complementary sensor modules on sidelites are also entering the aftermarket mix. The heightened technical barrier lifts revenue per job and helps sustain the North America automotive glass market beyond natural vehicle parc growth.
Volatility in soda ash, PVB, and EVA interlayer prices
Sekisui Chemical raised PVB prices by 6-15% in late 2024, citing energy and logistics inflation. Sisecam's acquisition of Ciner Group's U.S. soda-ash assets concentrates supply at a time when demand is rising toward 83 million tons by 2030. Limited natural soda-ash mines and a small group of global PVB producers give upstream vendors pricing power, squeezing float margins and forcing processors to hedge or vertically integrate. Sudden cost spikes erode profitability across the North America automotive glass market when price pass-throughs lag.
Other drivers and restraints analyzed in the detailed report include:
- Rising light-vehicle production across North America
- Electrification push favoring lightweight laminated glazing
- High incremental cost of smart and coated glass solutions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Laminated glazing generated 56.78% of 2025 revenue in the North America automotive glass market, anchored by its indispensable role in windshields and the growing use of laminated sidelites for security and acoustic comfort. Smart or switchable glass leads to growth with an 8.28% CAGR as electrochromic sunroofs migrate into broader vehicle lines. Tempered panes, once dominant for cost reasons, are slowly being displaced in non-critical areas as manufacturers chase mass savings and higher thermal performance. Coated glass segments expand in parallel, propelled by EV programs that demand low solar heat gain to protect battery range.
Continuous innovation underpins segment momentum. Gentex's film-based approach trims thickness while enabling large geometric freedom for roof modules. Integrated display technology merges glare control with infotainment, opening new revenue pools for glass makers. Laminated constructions now embed multiple interlayers-acoustic, solar, and structural-demonstrating how a single part can satisfy safety, comfort, and energy efficiency. As technology complexity climbs, suppliers with chemistry, coating, and electronics capabilities deepen their hold on the North America automotive glass market.
Windshields retained a 48.10% share of the North America automotive glass market in 2025, supported by mandatory fitment and strict impact regulations. Sunroof and rooflite modules, however, clock the fastest 7.62% CAGR through 2031 as panoramic roofs become a mainstream styling element. Laminated roof panels integrate electrochromic dimming, UV filtration, and heating grids, enhancing the cabin experience without adding opaque shades.
Sidelites transition from tempered to laminated formats in higher trims, providing burglary resistance and quieter cabins-attributes prized in near-silent EVs. Backlites remain stable in volume, yet see incremental smart features like integrated antennas and defog lines evolve. Exterior mirror glass migrates toward camera-based e-mirrors, reshaping the hardware stack but still relying on precision-polished substrates. Larger apertures and multi-functional coatings raise the engineering bar and reinforce OEM dependency on experienced glazing partners within the North America automotive glass market.
Complete Report Scope:
- By Type
- Laminated Glass
- Tempered Glass
- Coated and Solar-Control Glass
- Smart/Switchable Glass
- By Application
- Windshield
- Sidelite
- Backlite
- Sunroof/Rooflite
- Rear-view and Exterior Mirrors
- By Sales Channel
- OEM
- Aftermarket (Replacement and Calibration)
- By Vehicle Type
- Passenger Cars
- Hatchback
- Sedan
- Sport Utility Vehicle
- Multi-purpose Vehicle
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Passenger Cars
- By Country
- United States
- Canada
- Rest of North America
List of Companies Covered in this Report:
- AGC Inc.
- Saint-Gobain Sekurit
- Fuyao Glass Industry Group Co., Ltd.
- NSG Group/Pilkington
- Gentex Corporation
- Vitro S.A.B. de C.V.
- Samvardhana Motherson (SMR)
- Xinyi Glass Holdings Ltd.
- Webasto SE
- Magna International Inc.
- Guardian Industries
- PPG Industries Inc.
- Corning Incorporated
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid adoption of smart/switchable glass in premium trims
- 4.2.2 Bundled ADAS recalibration services boosting replacement demand
- 4.2.3 Rising light-vehicle production across North America
- 4.2.4 Electrification push favouring lightweight laminated glazing
- 4.2.5 OEM near-shoring of glass supply to cut Asia risk
- 4.2.6 Stringent FMVSS and Transport Canada glazing safety regulations
- 4.3 Market Restraints
- 4.3.1 Volatility in soda ash, PVB, and EVA interlayer prices
- 4.3.2 High incremental cost of smart and coated glass solutions
- 4.3.3 Capacity constraints in low-iron float lines (under-radar)
- 4.3.4 Insurance-driven preference for low-cost aftermarket glass
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Type
- 5.1.1 Laminated Glass
- 5.1.2 Tempered Glass
- 5.1.3 Coated and Solar-Control Glass
- 5.1.4 Smart/Switchable Glass
- 5.2 By Application
- 5.2.1 Windshield
- 5.2.2 Sidelite
- 5.2.3 Backlite
- 5.2.4 Sunroof/Rooflite
- 5.2.5 Rear-view and Exterior Mirrors
- 5.3 By Sales Channel
- 5.3.1 OEM
- 5.3.2 Aftermarket (Replacement and Calibration)
- 5.4 By Vehicle Type
- 5.4.1 Passenger Cars
- 5.4.1.1 Hatchback
- 5.4.1.2 Sedan
- 5.4.1.3 Sport Utility Vehicle
- 5.4.1.4 Multi-purpose Vehicle
- 5.4.2 Light Commercial Vehicles
- 5.4.3 Medium and Heavy Commercial Vehicles
- 5.4.1 Passenger Cars
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Rest of North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 AGC Inc.
- 6.4.2 Saint-Gobain Sekurit
- 6.4.3 Fuyao Glass Industry Group Co., Ltd.
- 6.4.4 NSG Group/Pilkington
- 6.4.5 Gentex Corporation
- 6.4.6 Vitro S.A.B. de C.V.
- 6.4.7 Samvardhana Motherson (SMR)
- 6.4.8 Xinyi Glass Holdings Ltd.
- 6.4.9 Webasto SE
- 6.4.10 Magna International Inc.
- 6.4.11 Guardian Industries
- 6.4.12 PPG Industries Inc.
- 6.4.13 Corning Incorporated
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


