

|
시장보고서
상품코드
2121462
자동차 유리 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Automotive Glass - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
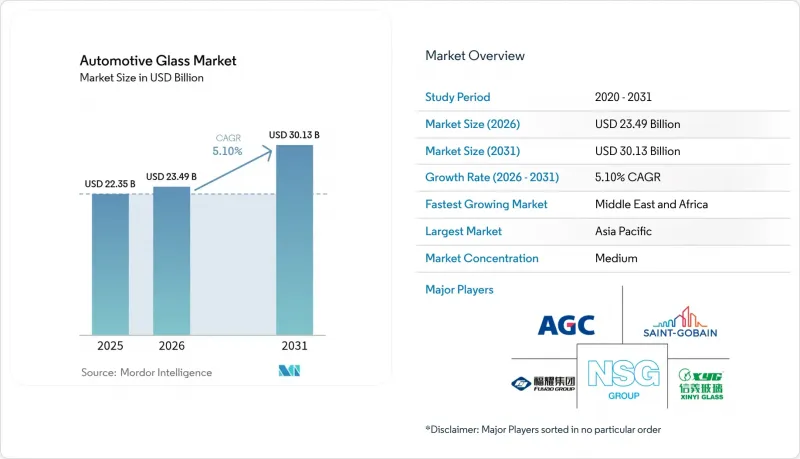
자동차 유리 시장 규모는 2025년 223억 5,000만 달러에서 2026년에는 234억 9,000만 달러로 확대되고, 2026년부터 2031년까지 CAGR 5.1%를 기록하며 2031년까지 301억 3,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 유리 종류(일반 유리 및 스마트 유리), 용도(앞유리, 선루프 등), 차종(승용차 등), 구동 방식(내연기관, 배터리 전기자동차(BEV) 등), 판매 채널(OEM 및 애프터마켓), 그리고 지역별로 분류되어 있습니다. 시장 규모 및 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 자동차 유리 시장의 동향 및 인사이트
EV 플랫폼에서의 파노라마 유리로의 전환
각 전기자동차 제조사들은 차량 내부의 분위기와 브랜드 정체성을 높이기 위해 더 큰 루프 유리를 채택하고 있습니다. 테슬라의 ‘사이버트럭’과 메르세데스-벤츠의 컨셉트카 ‘비전 V’에는 착색 수준을 조절할 수 있는 일렉트로크로믹 루프가 탑재되어 있어, 실내 온도를 최대 18°F까지 낮추고 공조 시스템의 부하를 경감시킵니다. 차량 1대당 유리 면적은 급증할 것으로 예상되며, 이에 따라 각 공급업체들은 와이드 포맷 굽힘 가공, Low-E 코팅, 그리고 적외선 흡수 중간막에 대한 투자를 진행하고 있습니다. 이러한 프리미엄 사양은 생산 비용의 하락에 따라 중가대 전기자동차로도 보급될 것으로 예상되며, 자동차용 유리 시장의 지속적인 성장을 뒷받침할 것으로 기대됩니다.
CO₂ 배출 목표 달성을 위한 OEM의 경량 접합 유리 수요
유럽의 규제에서는 2030년까지 차량군 평균 CO2 배출량을 100 g/km로 하는 목표가 설정되어 있어, 자동차 제조사들은 1kg 단위의 경량화를 추진해야 하는 상황에 놓여 있습니다. 2017년형 포드 GT에 대한 EPA의 조사에 따르면, 접합 유리가 질량의 30% 감축에 크게 기여한 것으로 나타났습니다. 이오노플라스트 중간막을 사용한 얇은 접합 유리는 내충격 성능을 저해하지 않으면서 최대 30%의 경량화를 실현하고 있습니다. AGC와 생고뱅은 경량화와 방음 성능을 모두 갖춘 1.6mm 전면 유리 구조를 상용화하여, 자동차용 유리 시장의 장기적인 전망을 한층 더 공고히 하고 있습니다.
특수 중간막(PVB, 아이오노플라스트)의 공급망 부족
쿠라레의 PVB 생산능력 확대는 방음용 및 HUD용 필름에 대한 수요 증가를 따라가지 못하고 있어 리드타임이 장기화되고, 할당 프로그램을 시행할 수밖에 없는 상황입니다. 유럽의 접합 유리 제조사들로부터는 단기적인 공급 부족이 보고되고 있어, 애프터마켓 주문보다 OEM 생산을 우선시할 수밖에 없는 상황입니다. 실험 단계에 있는 바이오 기반 중간막은 53.1%라는 유망한 기계적 성능 향상을 보이고 있지만, 양산화까지는 아직 수년이 소요될 전망입니다. 신공장이 가동되기 전까지 단기적인 공급 부족이 자동차용 유리 시장의 성장을 둔화시킬 가능성이 있습니다.
부문 분석
2025년, 일반 유리는 비용 효율성과 확립된 생산 설비 덕분에 자동차용 유리 시장 점유율의 82.05%를 차지했습니다. 접합 유리는 충격을 받아도 파편이 흩어지지 않아 전 세계 안전 기준을 충족하며, 강화 유리에 비해 시장 점유율을 확대하고 있습니다. 이러한 변화로 인해 특수 중간막의 공급은 부족하지만, OEM 업체들이 더 얇고 가벼운 구조를 추구하는 가운데, 접합 유리 제조업체들은 더 높은 부가가치를 창출할 수 있는 위치에 있습니다. 스마트 유리는 현재로서는 극히 일부에 불과하지만, 연평균 성장률(CAGR) 12.1%를 기록하며, 고급차 및 하이엔드 전기자동차의 틈새 시장을 개척할 것으로 예상됩니다.
일렉트로크로믹 루프는 초기 도입 단계에서 주류를 이루고 있으며, 메르세데스-벤츠의 ‘Vision V’ 프로토타입에서 볼 수 있듯이, 부유 입자 장치(SPD)는 더 빠른 전환 속도와 내구성을 실현하고 있습니다. 폴리머 분산형 액정(PDLC) 윈도우는 프라이버시 파티션을 목표로 하고 있으나, 열변색 필름은 여전히 상용화 전 단계에 있습니다. 규모의 경제가 향상됨에 따라 스마트 유리는 플래그십 모델을 넘어 보급되어 자동차 유리 시장을 견인할 것입니다.
2025년 현재, 전면 유리는 자동차 유리 시장 규모의 44.15%를 차지하고 있으며, 이는 장착 의무화와 ADAS 센서 탑재 증가에 힘입은 결과입니다. 복잡성으로 인해 단가가 상승함에 따라, 공급업체와 OEM 간의 공동 개발 주기가 강화되고 있습니다. 한편, SUV에서 파노라마 뷰를 위한 큰 개구부가 표준화됨에 따라 선루프는 연평균 성장률(CAGR) 9.6%로 가장 빠르게 성장하는 용도가 되고 있습니다.
백라이트의 경우, 방음용 접합 유리에 대한 수요가 완만하게 확대되고 있으나, 보증상의 문제가 그 속도를 둔화시키고 있습니다. 사이드라이트는 특히 유럽과 일본에서 승객 이탈 방지법에 대응하기 위해 접합 유리 구조로의 전환이 진행되고 있습니다. 백미러와 쿼터 윈도우에는 일렉트로크로믹식 눈부심 방지 코팅이 채택되어, 넓은 면적을 차지하지 않으면서도 기능성을 높이고 있습니다. 이러한 용도 구성 전체가 자동차용 유리 시장의 꾸준한 확장을 뒷받침하고 있습니다.
지역별 분석
아시아태평양은 중국의 막대한 생산량과 국내에서의 급속한 보급을 배경으로, 2025년에는 매출의 48.75%를 차지하며 자동차용 유리 시장을 견인했습니다. 정부의 인센티브로 인해 공장은 거의 풀가동을 유지하고 있으며, 인도의 생산량 증가가 새로운 수요의 주축이 되고 있습니다. 상하이에서 개최된 컨퍼런스에서는 스마트 글라스, LiDAR 투과성, AR-HUD 통합이 주목받으며 지속적인 혁신이 드러났습니다. 일본과 한국은 프리미엄 OEM을 대상으로 첨단 접합 유리 및 코팅 제품을 공급하고 있으며, 자동차용 유리 시장 전체의 일부로서 고수익성 틈새 시장을 유지하고 있습니다.
각 제조사는 중국산 수입으로 인한 이익률 압박에 대응하기 위해 스마트 글라스 및 지속가능성 프로그램으로의 전환을 모색하고 있습니다. AGC와 생고뱅이 공동 개발한 ‘Volta’ 용광로는 CO₂ 배출 강도를 대폭 줄이기 위한 전략적 움직임을 보여줍니다. 한편, 북미는 SUV 수요에 힘입어 여전히 큰 영향력을 유지하고 있습니다. 미국에서는 애프터마켓이 활기를 띠고 있으며, ‘Auto Glass Now’와 같은 브랜드가 전국적인 사업 확장을 통해 교체용 유리 매출을 확보하고 있습니다.
중동 및 아프리카는 2031년까지 연평균 성장률(CAGR) 6.8%로 가장 빠른 성장이 예상됩니다. 사우디아라비아의 실리카가 풍부한 광상은 공급 현지화를 목적으로 한 플로트 유리 투자를 유치하고 있습니다. 산업 다각화라는 광범위한 정책에 따른 보조금 제도가 자동차 부품 생산을 촉진하고 있으며, 이는 자동차 유리 시장에서 해당 지역의 점유율 확대로 이어지고 있습니다. 남미의 전망은 주로 브라질의 조립 대수에 좌우되는 반면, 아프리카의 성장은 남아프리카공화국의 비교적 성숙한 부문이 주도하고 있습니다. 인근 생산 전략을 통해 세계 공급업체들은 이러한 다양한 지역에서 운송 비용과 적시(JIT) 수요 간의 균형을 맞출 수 있게 되었습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the automotive glass market size is expected to grow from USD 22.35 billion in 2025 to USD 23.49 billion in 2026 and is forecast to reach USD 30.13 billion by 2031 at 5.1% CAGR over 2026-2031.
This report is Segmented by Glass Type (Regular Glass and Smart Glass), Application (Windshield, Sunroof and More), Vehicle Type (Passenger Cars, and More), Propulsion (Internal Combustion Engine, Battery Electric Vehicle (BEV), and More), Sales Channel (OEM, and Aftermarket), and Geography. The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Automotive Glass Market Trends and Insights
Shift Toward Panoramic Glazing In EV Platforms
Electric-vehicle makers are installing larger roof panes to enhance cabin ambience and brand identity. Tesla's Cybertruck and Mercedes-Benz's Vision V concept integrate electrochromic roofs that modulate tint levels, cutting cabin temperatures by up to 18°F and lowering HVAC loads. Glass area per vehicle is forecast to surge, prompting suppliers to invest in wide-format bending, low-E coatings, and infrared-absorbing interlayers. This premium specification is expected to permeate mid-priced EVs as production costs fall, supporting sustained growth in the automotive glass market.
OEM Demand For Lightweight Laminated Glass To Meet CO2 Targets
European regulations set a 100 g/km fleet-average CO2 goal for 2030, pushing automakers to shave every kilogram. EPA studies of the 2017 Ford GT show laminated glazing contributed materially to a 30% mass drop. Thin-gauge laminates using ionoplast interlayers now trim weight by up to 30% without compromising impact performance. AGC and Saint-Gobain are commercializing 1.6-mm windshield constructions that pair weight savings with acoustic damping, reinforcing long-term prospects for the automotive glass market.
Supply-Chain Crunch Of Specialty Interlayers (PVB, Ionoplast)
Kuraray's PVB capacity expansions have not kept pace with rising demand for acoustic and HUD-grade films, extending lead times and forcing allocation programs. European laminators report spot shortages, compelling them to prioritize OEM production over aftermarket orders. Experimental bio-based interlayers deliver promising mechanical gains of 53.1% but remain years from scale. Short-term supply stress may temper automotive glass market growth until new plants start up.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Sunroof Penetration In SUVs
- Regulation-Led Mandatory Safety Glazing For Side Windows
- Margin Erosion From Chinese Float-Glass Overcapacity Flooding EU Market
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Regular glass commanded 82.05% of the automotive glass market share in 2025, thanks to cost efficiency and entrenched production assets. Laminated variants are gaining against tempered formats because they keep shards intact on impact, satisfying global safety norms. The shift tightens the supply of specialty interlayers, yet it positions laminators for higher value capture as OEMs demand thinner, lighter constructions. Smart glass, though only a minority today, is projected to post a 12.1% CAGR, carving out niches in luxury vehicles and high-end EVs.
Electrochromic roofs dominate early adoption; suspended particle devices (SPD) deliver faster switching and durability, as shown in Mercedes-Benz's Vision V prototype. Polymer-dispersed liquid crystal (PDLC) windows target privacy partitions, while thermochromic films remain pre-commercial. As economies of scale improve, smart glass will expand beyond flagships, bolstering the automotive glass market.
Windshields held 44.15% of the automotive glass market size in 2025, underpinned by mandatory fitment and rising ADAS sensor content. Complexity drives up unit value, reinforcing supplier-OEM co-development cycles. Sunroofs, however, are the fastest-growing application at 9.6% CAGR as SUVs standardize large openings for panoramic vistas.
Backlites see modest traction from acoustic laminates, though warranty issues temper speed. Sidelites transition to laminated construction to meet ejection-prevention laws, especially in Europe and Japan. Rear-view mirrors and quarter windows integrate electrochromic anti-glare coatings, adding feature content without large area demand. Collectively, the application mix underpins steady expansion in the automotive glass market.
Complete Report Scope:
- By Glass Type
- Regular Glass
- Laminated Glass
- Tempered Glass
- Smart Glass
- Electrochromic
- Suspended Particle Device (SPD)
- Polymer Dispersed Liquid Crystal (PDLC)
- Thermochromic
- Regular Glass
- By Application
- Windshield
- Backlite (Rear Window)
- Sidelite (Side Windows)
- Sunroof
- Rear-view & Side-view Mirrors
- Other Glazing (Quarter & Vent)
- By Vehicle Type
- Passenger Cars
- Hatchback
- Sedan
- SUV & Crossover
- Luxury & Sports
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Passenger Cars
- By Propulsion
- Internal Combustion Engine (ICE)
- Battery Electric Vehicle (BEV)
- Hybrid Electric Vehicle (HEV/PHEV)
- Fuel Cell Electric Vehicles (FCEV)
- By Sales Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific dominated the automotive glass market, with 48.75% of the revenue in 2025, anchored by China's vast output and rapid domestic uptake. Government incentives have kept plants near capacity, while India's production climb adds a fresh demand axis. Conferences in Shanghai spotlight intelligent glazing, LiDAR transparency, and AR-HUD integration, showcasing continual innovation. Japan and South Korea supply advanced laminated and coated products for premium OEMs, preserving high-margin niches as part of the broader automotive glass market.
Producers combat margin squeeze from Chinese imports by pivoting into smart glass and sustainability programs. AGC and Saint-Gobain's joint Volta furnace evidences a strategic move to slash CO2 intensity. Meanwhile, North America remains influential due to the demand for SUVs. The United States features vibrant aftermarket activity; brands such as Auto Glass Now scale national footprints to capture replacement revenue.
The Middle East and Africa are expected to be the fastest climbers at 6.8% CAGR through 2031. Saudi Arabia's silica-rich deposits attract float-glass investments intended to localize supply. Subsidies aligned with broader industrial-diversification agendas incentivize auto-component production, broadening the region's stake in the automotive glass market. South America's outlook is tied chiefly to Brazilian assembly volumes, while Africa's growth centers on South Africa's relatively mature sector. Proximity production strategies help global suppliers balance freight costs and just-in-time expectations across these varied geographies.
- AGC Inc. (Asahi Glass)
- Saint-Gobain S.A.
- Nippon Sheet Glass Co. Ltd.
- Fuyao Glass Industry Group Co. Ltd.
- Xinyi Glass Holdings Ltd.
- Guardian Automotive (Koch Industries)
- Webasto SE
- Carlex Glass America LLC
- Magna International Inc.
- Vitro Automotive
- Corning Incorporated
- Sisecam Automotive
- Shanghai Yaohua Pilkington Glass
- Gentex Corporation
- AGP Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Shift Toward Panoramic Glazing In EV Platforms
- 4.2.2 OEM Demand For Lightweight Laminated Glass To Meet CO2 Targets
- 4.2.3 Rapid Sunroof Penetration In SUVs
- 4.2.4 Regulation-Led Mandatory Safety Glazing For Side Windows
- 4.2.5 Growing Retrofit Of HUD-Compatible Windshields By Premium OEMs
- 4.2.6 Integration Of Embedded Sensors For ADAS Functionality
- 4.3 Market Restraints
- 4.3.1 Supply-Chain Crunch Of Specialty Interlayers (PVB, Ionoplast)
- 4.3.2 Margin Erosion From Chinese Float-Glass Overcapacity Flooding EU Market
- 4.3.3 High Warranty Costs Linked To Acoustic Laminated Backlights In SUVs
- 4.3.4 Slow Replacement Cycles In Mature Aftermarket Channels
- 4.4 Value-Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
- 4.6 OEM vs. Aftermarket Trend Analysis
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Glass Type
- 5.1.1 Regular Glass
- 5.1.1.1 Laminated Glass
- 5.1.1.2 Tempered Glass
- 5.1.2 Smart Glass
- 5.1.2.1 Electrochromic
- 5.1.2.2 Suspended Particle Device (SPD)
- 5.1.2.3 Polymer Dispersed Liquid Crystal (PDLC)
- 5.1.2.4 Thermochromic
- 5.1.1 Regular Glass
- 5.2 By Application
- 5.2.1 Windshield
- 5.2.2 Backlite (Rear Window)
- 5.2.3 Sidelite (Side Windows)
- 5.2.4 Sunroof
- 5.2.5 Rear-view & Side-view Mirrors
- 5.2.6 Other Glazing (Quarter & Vent)
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.1.1 Hatchback
- 5.3.1.2 Sedan
- 5.3.1.3 SUV & Crossover
- 5.3.1.4 Luxury & Sports
- 5.3.2 Light Commercial Vehicles
- 5.3.3 Medium and Heavy Commercial Vehicles
- 5.3.1 Passenger Cars
- 5.4 By Propulsion
- 5.4.1 Internal Combustion Engine (ICE)
- 5.4.2 Battery Electric Vehicle (BEV)
- 5.4.3 Hybrid Electric Vehicle (HEV/PHEV)
- 5.4.4 Fuel Cell Electric Vehicles (FCEV)
- 5.5 By Sales Channel
- 5.5.1 OEM
- 5.5.2 Aftermarket
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Spain
- 5.6.3.5 Italy
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Australia
- 5.6.4.6 New Zealand
- 5.6.4.7 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 South Africa
- 5.6.5.4 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 AGC Inc. (Asahi Glass)
- 6.4.2 Saint-Gobain S.A.
- 6.4.3 Nippon Sheet Glass Co. Ltd.
- 6.4.4 Fuyao Glass Industry Group Co. Ltd.
- 6.4.5 Xinyi Glass Holdings Ltd.
- 6.4.6 Guardian Automotive (Koch Industries)
- 6.4.7 Webasto SE
- 6.4.8 Carlex Glass America LLC
- 6.4.9 Magna International Inc.
- 6.4.10 Vitro Automotive
- 6.4.11 Corning Incorporated
- 6.4.12 Sisecam Automotive
- 6.4.13 Shanghai Yaohua Pilkington Glass
- 6.4.14 Gentex Corporation
- 6.4.15 AGP Group
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


