|
시장보고서
상품코드
2116928
하드 시설 관리 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Hard Facility Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
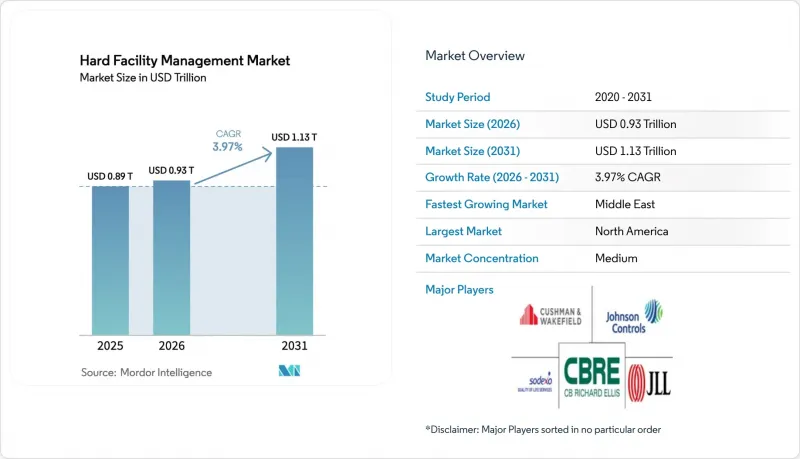
에 의하면, 하드 시설 관리 시장 규모는 2025년 8,900억 달러에서 2026년에는 9,300억 달러로 확대되어 2031년까지 1조 1,300억 달러에 이를 것으로 예상되고 있어 2026년부터 2031년까지 CAGR 3.97%로 성장할 전망입니다.
본 보고서는 서비스 유형(자산 관리, MEP 및 HVAC 서비스, 소방 시스템 및 안전, 기타), 제공 형태(사내 FM, 외부 위탁 FM(싱글 FM, 번들 FM, 기타)), 최종 사용자 산업(상업, 호스피탈리티, 기관·공공 인프라, 산업·공정 부문, 기타), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 하드 시설 관리 시장 동향 및 인사이트
AI를 활용한 예측 유지보수 플랫폼이 업무 혁신을 주도
현재, 머신러닝 모델이 HVAC 칠러, 보일러, 개폐 장치에서 발생하는 진동, 온도, 전력 소비 데이터를 분석하여 고장이 발생하기 몇 주 전에 이상을 감지함으로써, 예기치 못한 가동 중단을 계획적인 유지보수로 전환하고 있습니다. ABM Industries는 2025년 Ingredion의 사업장에 이 기법을 도입하여 압축기 정지를 방지하는 동시에 연간 120만 달러의 비용 절감을 실현했습니다. 건물 소유주는 서비스 계약에 가동률 조항을 포함시켜, 공급업체가 센서 네트워크 및 데이터 사이언스자에 대한 투자를 하도록 유도하고 있습니다. 이러한 변화는 초기 디지털 비용을 감당할 수 있는 자본력을 갖춘 대형 사업자에게 유리하게 작용하며, 업계 재편을 가속화하고 있습니다. 또한, 예측형 계약은 공급업체와의 관계를 더욱 긴밀하게 만듭니다. 분석 플랫폼이 자산 상태를 제조업체의 데이터와 대조하여 벤치마킹을 수행하기 때문에 부품 재고 및 보증 범위의 공동 최적화가 요구되기 때문입니다. 그 결과, 어려운 상황에 처한 시설 관리 시장은 평균 고장 간격(MTBF) 지표에 연동된 성과 기반 가격 책정으로 전환되고 있습니다.
탈탄소화 의무화가 HVAC 및 에너지 개보수 투자를 가속화한다.
캘리포니아주의 2025년 건축 기준에서는 신규 상업용 건물에 히트펌프 설치가 의무화되어 있으며, EU 개정 지침에서는 2030년까지 신축 건물의 제로 배출이 의무화되어 있어 난방 및 환기 시스템의 급속한 전기화가 시급합니다. 가변 냉매 유량(VRF) 시스템,지열 히트펌프, 그리고 열교를 줄여주는 고성능 파사드에 대한 수요가 급증하고 있습니다. 시설 관리자들은 기존 계약 기간을 초과할 가능성이 있는 개보수 자금 확보에 어려움을 겪고 있으며, 절감분을 통해 상환을 분산시키는 에너지 서비스 회사(ESCO)형 계약에 대한 관심이 높아지고 있습니다. 조달 팀은 압축기나 인버터의 긴 리드타임이라는 병목 현상에 직면해 있으며, 이러한 상황으로 인해 조달 역량을 갖춘 통합형 FM 제공업체의 역할이 확대되고 있습니다. ISO 50001과 같은 규정 준수 체계는 현재 공공 입찰의 필수 요건이 되어, 중소규모 도급업체 시장 진입 장벽이 높아지고 있을 뿐만 아니라, 하드 시설 관리 시장에서 탈탄소화 실적이 갖는 전략적 중요성이 커지고 있습니다.
숙련 기술자 인력 부족이 서비스 제공 능력을 제약
전미종합건설업협회(AGC)의 발표에 따르면, 2025년 프로젝트에서 미국 내 43만 9,000명의 인력 부족이 예상됩니다. 기술자의 68%가 45세 이상이며, 퇴직자 수가 견습생 수용 수를 초과하고 있습니다. 임금 상승률은 연 6%를 넘어, 고정 가격 계약의 이익률을 압박하고 있습니다. 빌딩 자동화 프로그래밍이나 화재 경보기 통합과 같은 전문직의 경우, 자격 취득까지의 과정이 길고 벤더별 고유한 요건이 있어 인력 부족이 가장 심각합니다. 이민 규제로 인해 북미와 유럽에서는 인력 부족이 더욱 심화되고 있습니다. 임금 인상만으로는 인력 부족 문제를 해결할 수 없어, 서비스 제공 기업들은 제한된 인력을 최대한 활용하기 위해 증강현실(AR)을 활용한 교육 및 원격 전문가 지원에 대한 투자를 확대되고 있습니다. 이러한 만성적인 인력 부족으로 인해 하드 시설 관리 시장이 급증하는 리모델링 수요를 흡수하는 능력이 제한되고 있습니다.
부문 분석
MEP 및 HVAC 서비스는 2025년 매출의 44.63%를 차지하며, 시설 수준에서 하드 시설 관리 시장 규모를 지탱하는 핵심 역할을 하고 있음을 보여줍니다. 데이터센터의 전력 밀도가 랙당 100kW로 급증함에 따라, 액체 냉각, 이중화 전원 공급 및 정밀 제어에 대한 수요가 가속화되고 있습니다. 의료 분야에서 Joint Commission이 의무화한 분기별 점검은 화재 안전 관련 업무를 뒷받침하고 있지만, 외관 및 구조물의 수리량은 사건에 따라 좌우되며, 기후 변화에 따른 사건 발생 후 증가하는 경향을 보입니다.
전산화된 유지보수 관리 시스템의 부상으로, 연평균 성장률(CAGR) 4.32%로 가장 빠르게 성장하고 있는 서비스 분야인 자산 관리가 고도화되고 있습니다. 이 플랫폼은 칠러, 펌프, 비상 전원 시스템에서 운영 데이터를 수집하여 잔여 수명을 산출하고, 작업을 자동으로 스케줄링합니다. 이러한 융합으로 인해 분석을 통해 MEP 원격 측정 데이터가 전략적 계획에 통합됨에 따라 각 전문 분야 간의 경계가 모호해지고 있습니다. 소유주가 관리 업무의 부담을 경감시켜 줄 통합형 패키지를 요구하는 가운데, HVAC만을 다루는 소규모 업체들은 업계 재편의 압박에 직면하고 있습니다. NFPA 72-2025 인증을 받은 무선 연기 감지기 및 클라우드 기반 경보 시스템은 점검 업무의 디지털화를 더욱 촉진하고 있습니다. 전반적으로, 이 부문이 ‘고장 대응형’에서 ‘성과 지향형’ 서비스로 전환되고 있는 것은 하드 시설 관리 시장의 결정적인 흐름이 되고 있습니다.
지역별 분석
북미는 방대한 기존 건축물 재고와 전기화에 관한 규제의 추진력에 힘입어 2025년 매출의 37.28%를 계속 차지했습니다. 연방 정부의 인센티브와 주 정부의 건축 기준에 따라 개보수 주기가 촉진되고 있으며, 특히 캘리포니아주에서는 히트 펌프 설치가 의무화되어 설계 기준으로 정착되었습니다. 버지니아주와 텍사스주에 집중된 미국의 데이터센터 군은 고밀도 전력 및 절수형 냉각에 대한 수요를 더욱 높이고 있습니다. 캐나다의 인프라 갱신 사업은 FM(시설 관리) 보증을 포함한 P3(민관 협력) 모델과 연계되어 있어 장기적인 수익을 확보하고 있습니다.
유럽의 동향은 2030년까지 신축 건물에 대한 제로 배출 목표를 정한 개정 지침에 의해 주도되고 있으며, 이에 따라 자본이 HVAC의 전기화 및 건축 외피 개보수로 유도되고 있습니다. 독일은 에너지 효율화를 위해 140억 유로(159억 달러)를 배정하고, FM 주도의 개보수 공사에 보조금을 지급하고 있습니다. EPC 클래스 A 및 B 준수가 조달 기준을 재구성하고 있으며, ISO 50001에 따라 검증된 탈탄소화 로드맵을 보유한 공급업체가 우선적으로 선정되고 있습니다.
중동은 5.81%라는 가장 높은 연평균 성장률(CAGR)을 보이고 있으며, NEOM 및 레드씨 리조트 시티를 포함한 ‘사우디 비전 2030’의 메가 프로젝트에서 기후 변화에 적응한 HVAC 및 에너지 관리가 요구되고 있습니다. 두바이 2040 마스터 플랜에 기반한 UAE의 지침은 스마트 빌딩 통합과 LEED 골드 인증 획득을 추진하고 있습니다. 높은 주변 온도로 인해 축열 기능을 갖춘 칠러 설비나 여름철 기온 50℃를 견딜 수 있는 소재가 필요하며, 1제곱피트당 지출이 증가하고 있습니다. 아시아태평양의 성장은 대규모 상업시설에 대한 중국의 자동화 의무화 및 인도의 ‘스마트 시티 미션’에 의해 주도되고 있습니다. 한편, 남미와 아프리카에서는 도시화가 진행됨에 따라 다국적 기업 입주자가 증가하며 지역별로 진전이 나타나고 있습니다. 각 지역에서 규제 기반의 에너지 목표, 극한 기후, 스마트 시티 프로그램이 하드 시설 관리 시장의 대상 시장 규모를 확대시키고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.03According to Mordor Intelligence, the hard facility management market size is expected to increase from USD 890 billion in 2025 to USD 930 billion in 2026 and reach USD 1.13 trillion by 2031, growing at a CAGR of 3.97% over 2026-2031.
This report is Segmented by Service Type (Asset Management, MEP and HVAC Services, Fire Systems and Safety, and More), Offering Type (In-House FM, and Outsourced FM [Single FM, Bundled FM, and More]), End-User Industry (Commercial, Hospitality, Institutional and Public Infrastructure, Industrial and Process Sector, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Hard Facility Management Market Trends and Insights
AI-Enabled Predictive Maintenance Platforms Drive Operational Transformation
Machine-learning models now analyze vibration, temperature, and power-draw data from HVAC chillers, boilers, and switchgear to flag anomalies weeks before a failure occurs, converting unplanned downtime into scheduled interventions. ABM Industries deployed the approach at an Ingredion site in 2025, avoiding compressor outages and saving USD 1.2 million annually. Building owners are embedding uptime clauses in service agreements, pushing providers to invest in sensor networks and data scientists. The shift favors large, capital-rich operators that can absorb upfront digital costs, accelerating consolidation. Predictive contracts also tighten supplier relationships because analytics platforms benchmark asset health against manufacturer data, compelling joint optimization of parts inventory and warranty coverage. As a result, the hard facility management market is moving toward outcome-based pricing tied to mean-time-between-failure metrics.
Decarbonization Mandates Accelerate HVAC and Energy Retrofit Investments
California's 2025 code now requires heat pumps in new commercial builds, and the EU's revised directive mandates zero-emission status for new structures by 2030, forcing rapid electrification of heating and ventilation. Demand has spiked for variable-refrigerant-flow systems, ground-source heat pumps, and high-performance facades that cut thermal bridging. Facility managers wrestle with securing retrofit capital that may exceed traditional contract horizons, amplifying interest in energy-service-company style agreements that spread repayment over savings. Procurement teams face lengthy lead times for compressors and inverters, a bottleneck that expands the role of integrated FM providers with sourcing leverage. Compliance frameworks such as ISO 50001 are now prerequisites for public tenders, raising entry barriers for smaller contractors and increasing the strategic importance of decarbonization credentials within the hard facility management market.
Skilled-Trades Labor Shortages Constrain Service Delivery Capacity
The Associated General Contractors of America revealed a 439,000-worker shortfall in the United States for 2025 projects, with 68% of technicians aged 45 plus and retirement outpacing apprenticeship intake. Wage inflation passed 6% annually, eroding fixed-price margins. Specialized roles in building-automation programming and fire-alarm integration face the steepest gaps because certification pathways are lengthy and vendor-specific. Immigration curbs intensify the squeeze in North America and Europe. Higher pay alone has not resolved the scarcity, prompting providers to invest in augmented-reality training and remote expert support to stretch scarce talent. Persistent shortages limit the capacity of the hard facility management market to absorb surging retrofit demand.
Other drivers and restraints analyzed in the detailed report include:
- Integrated Hard-Soft FM Outsourcing Reduces Lifecycle Costs
- Data-Driven FM Procurement Enables Cost-Inflation Hedging Strategies
- Volatile Input Prices for Critical MEP Spare Parts Increase Operational Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
MEP and HVAC services claimed 44.63% of 2025 revenue, underscoring their role as the backbone of the hard facility management market size at facility level. Data-center power densities jumping toward 100 kW per rack accelerate demand for liquid cooling, redundant feeds, and precision controls. Quarterly inspections mandated by Joint Commission in healthcare sustain fire-safety work, while facade and structural repair volumes are event-driven, rising after climate events.
The rise of computerized maintenance management systems is elevating asset management, the fastest-growing service line at 4.32% CAGR. Platforms capture run-time data from chillers, pumps, and emergency power systems, calculate remaining useful life, and auto-schedule tasks. This convergence blurs distinctions between trades because analytics pull MEP telemetry into strategic planning. Smaller HVAC-only shops face consolidation pressure as owners pursue integrated bundles that cut administrative effort. Wireless smoke detectors and cloud alarms, recognized in NFPA 72-2025, further digitize inspection routines. Overall, the segment's transition from break-fix to outcome-oriented service is a defining current for the hard facility management market.
Complete Report Scope:
- By Service Type
- Asset Management
- MEP and HVAC Services
- Fire Systems and Safety
- Other Hard FM Services
- By Offering Type
- In-House FM
- Outsourced FM
- Single Facility Management
- Bundled Facility Management
- Integrated Facility Management
- By End-User Industry
- Commercial
- Hospitality
- Institutional and Public Infrastructure
- Healthcare
- Industrial and Process Sector
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 37.28% of 2025 revenue because of vast legacy building stock and regulatory momentum around electrification. Federal incentives and state codes encourage retrofit cycles, especially in California where compulsory heat pumps now set design baselines. U.S. data-center clusters in Virginia and Texas amplify demand for high-density power and water-efficient cooling. Canada's infrastructure renewals concur with P3 models that embed FM guarantees, binding long-term revenue.
Europe's trajectory is dominated by the revised directive setting zero-emission goals for new buildings by 2030, which channels capital into HVAC electrification and envelope upgrades. Germany earmarked EUR 14 billion (USD 15.9 billion) for energy efficiency, subsidizing FM-led retrofits. Compliance with EPC classes A and B is reshaping procurement criteria, shunting preference toward providers with decarbonization roadmaps verified under ISO 50001.
The Middle East carries the fastest CAGR at 5.81% as Saudi Vision 2030 mega projects including NEOM and the Red Sea resort city demand climate-adapted HVAC and energy management. UAE directives under the Dubai 2040 master plan push smart-building integration and LEED Gold certifications. High ambient temperatures necessitate chiller plants with thermal storage and materials rated for 50 °C summers, intensifying per-square-foot spend. Asia-Pacific growth is propelled by China's automation mandate for large commercial builds and India's Smart Cities Mission, while South America and Africa progress in pockets as urbanization lures multinational occupiers. Across regions, regulatory energy targets, climatic extremes, and smart-city programs expand addressable volumes within the hard facility management market.
- CBRE Group, Inc.
- ISS A/S
- Sodexo S.A.
- EMCOR Group, Inc.
- Mitie Group plc
- ABM Industries Incorporated
- Aramark Corporation
- Apleona GmbH
- GDI Integrated Facility Services Inc.
- OCS Group Limited
- Atalian Holding Development and Strategy
- Compass Group PLC
- Cushman and Wakefield plc
- Jones Lang LaSalle Incorporated
- Bouygues Energies and Services S.A.S.
- Dussmann Stiftung and Co. KGaA
- SBFM Limited
- BGIS Global Integrated Solutions, Inc.
- Al Shafar United for Facilities Management LLC
- Serco Group plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 AI-Enabled Predictive Maintenance Platforms
- 4.2.2 Decarbonization Mandates Driving HVAC and Energy Retrofits
- 4.2.3 Integrated Hard-Soft FM Outsourcing to Reduce Lifecycle Cost
- 4.2.4 Data-Driven FM Procurement and Cost-Inflation Hedging
- 4.2.5 Resilience Upgrades for Climate-Related Extreme Weather Events
- 4.2.6 Private-Equity Roll-Ups Accelerating Hard-FM Tech Adoption
- 4.3 Market Restraints
- 4.3.1 Skilled-Trades Labor Shortages and Aging Workforce
- 4.3.2 Volatile Input Prices for Critical MEP Spare Parts
- 4.3.3 Cyber-Security Vulnerabilities in Connected BMS
- 4.3.4 Short Contract Tenures Limiting ROI on Hard-FM Capex
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Impact of Macroeconomic Factors
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Asset Management
- 5.1.2 MEP and HVAC Services
- 5.1.3 Fire Systems and Safety
- 5.1.4 Other Hard FM Services
- 5.2 By Offering Type
- 5.2.1 In-House FM
- 5.2.2 Outsourced FM
- 5.2.2.1 Single Facility Management
- 5.2.2.2 Bundled Facility Management
- 5.2.2.3 Integrated Facility Management
- 5.3 By End-User Industry
- 5.3.1 Commercial
- 5.3.2 Hospitality
- 5.3.3 Institutional and Public Infrastructure
- 5.3.4 Healthcare
- 5.3.5 Industrial and Process Sector
- 5.3.6 Other End-User Industries
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 United Kingdom
- 5.4.2.2 Germany
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Rest of Asia
- 5.4.4 Middle East
- 5.4.4.1 Israel
- 5.4.4.2 Saudi Arabia
- 5.4.4.3 United Arab Emirates
- 5.4.4.4 Turkey
- 5.4.4.5 Rest of Middle East
- 5.4.5 Africa
- 5.4.5.1 South Africa
- 5.4.5.2 Egypt
- 5.4.5.3 Rest of Africa
- 5.4.6 South America
- 5.4.6.1 Brazil
- 5.4.6.2 Argentina
- 5.4.6.3 Rest of South America
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 CBRE Group, Inc.
- 6.4.2 ISS A/S
- 6.4.3 Sodexo S.A.
- 6.4.4 EMCOR Group, Inc.
- 6.4.5 Mitie Group plc
- 6.4.6 ABM Industries Incorporated
- 6.4.7 Aramark Corporation
- 6.4.8 Apleona GmbH
- 6.4.9 GDI Integrated Facility Services Inc.
- 6.4.10 OCS Group Limited
- 6.4.11 Atalian Holding Development and Strategy
- 6.4.12 Compass Group PLC
- 6.4.13 Cushman and Wakefield plc
- 6.4.14 Jones Lang LaSalle Incorporated
- 6.4.15 Bouygues Energies and Services S.A.S.
- 6.4.16 Dussmann Stiftung and Co. KGaA
- 6.4.17 SBFM Limited
- 6.4.18 BGIS Global Integrated Solutions, Inc.
- 6.4.19 Al Shafar United for Facilities Management LLC
- 6.4.20 Serco Group plc
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment