|
시장보고서
상품코드
2125579
시설 관리(FM) 소프트웨어 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Facility Management Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
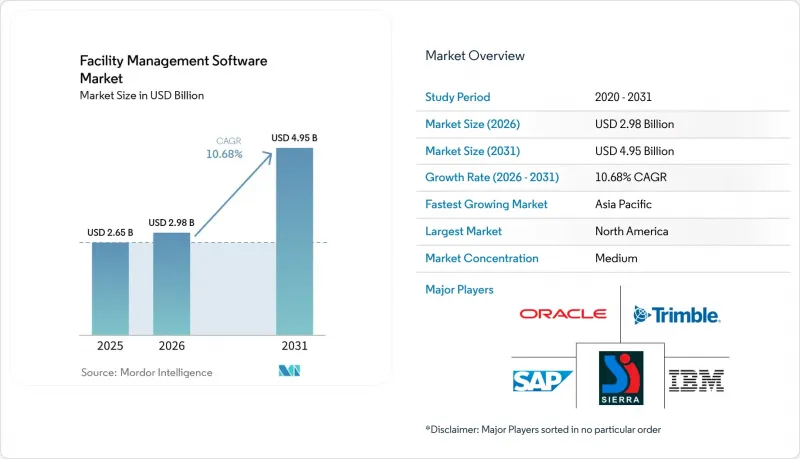
에 의하면, 시설 관리(FM) 소프트웨어 시장 규모는 2025년 26억 5,000만 달러에서 2026년에는 29억 8,000만 달러로 확대되어 2031년까지 49억 5,000만 달러에 이를 것으로 예상되고 있어 2026년부터 2031년까지 CAGR 10.68%로 성장할 전망입니다.

본 보고서는 소프트웨어 유형(CAFM, IWMS, CMMS), 배포 모델(클라우드, On-Premise, 하이브리드), 최종 사용자(상업, 기관, 공공 인프라, 산업 등), 기능(자산 관리, 유지보수 관리, 공간 관리, 에너지 관리), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 시설 관리(FM) 소프트웨어 시장 동향 및 인사이트
클라우드 기반 SaaS 플랫폼 채택 확대
구독 모델을 통해 설비 투자가 운영비로 전환됨에 따라 중견 기업 구매자층에 대한 접근성이 확대되는 동시에, 도입 주기가 18개월에서 약 6개월로 단축되고 있습니다. ServiceNow의 워크플레이스 제품군은 2025년에 1,200개의 기업 고객을 확보했으며, 그 가장 큰 요인으로 가격 책정의 유연성이 꼽히고 있습니다. 멀티테넌트 아키텍처를 통해 벤더는 AI 업데이트를 지속적으로 제공할 수 있습니다. 이는 On-Premise형 시스템에는 없는 장점입니다. 이러한 민첩성은 벤더 종속성을 강화하고 전환 비용을 높임으로써 지속적인 두 자릿수 성장을 뒷받침하고 있습니다.
예지 보전을 위한 IoT 센서 통합
센서의 보급으로 사후 대응형 유지보수에서 예측 유지보수로의 전환이 가능해져, 가동 중단 시간을 최대 40%까지 줄일 수 있습니다. Fracttal사가 라틴아메리카의 공장에 5만 개의 진동 센서를 도입한 결과, 고장을 72시간 전에 감지하여 2024년에는 1,200만 달러의 비용 절감을 실현했습니다. 엣지 컴퓨팅과 5G 연결을 통해 1초 미만의 알림 통지가 가능해졌으며, SAP가 2025년에 지멘스의 MindSphere와 제휴한 것과 같은 파트너십을 통해 텔레메트리 데이터를 자산 이력과 통합하여 예비 부품 계획을 최적화하고 있습니다.
레거시 시스템 통합의 복잡성
독자적인 프로토콜로 인해 프로젝트 비용이 40-60% 증가하고 있으며, 지멘스의 Desigo CC 컨트롤러의 경우 타사 IWMS와의 통합을 위해 맞춤형 미들웨어가 필요합니다. 하네웰이 2024년에 47유형의 사전 구축된 커넥터를 출시함으로써 일부 과제는 해소되었지만, 여전히 프로젝트의 38%가 예산을 초과하고 있습니다. 의료시설 캠퍼스에서는 이러한 과제가 두드러지게 나타납니다. 12개 건물에 걸친 존슨 컨트롤즈의 ‘OpenBlue’로의 전환은 구형 공압 제어 시스템으로 인해 14개월이 소요되었습니다.
부문 분석
통합 업무 공간 관리 시스템(IWMS)은 가장 빠르게 성장하는 부문으로, 2031년까지 연평균 성장률(CAGR)이 16.80%를 나타낼 것으로 예측됩니다. 그러나 2025년 현재, 컴퓨터 지원 시설 관리(CAM)가 시설 관리(FM) 소프트웨어 시장의 41.40% 점유율을 계속 차지하고 있습니다. 대기업들은 리스, 자본 프로젝트, 에너지 분석을 일원화하여 관리하기 위해 IWMS를 선호하고 있으며, IBM TRIRIGA 및 Oracle Primavera Unifier의 도입이 그 증거입니다. 전산화된 유지보수 관리 시스템(CMMS)은 자산 집약적인 업종에서 지지를 받고 있으며, UpKeep이나 MaintainX와 같은 ‘모바일 퍼스트’ 벤더의 경우 도입 후 60일 이내에 89%의 도입률을 기록하고 있습니다. CFO들이 2027년까지 3개 이상의 포인트 솔루션을 대체하는 것을 목표로 하는 가운데, IWMS의 시설 관리(FM) 소프트웨어 시장 규모는 급속히 확대될 것으로 예상되는 반면, CAFM은 신속한 도입과 낮은 복잡성을 우선시하는 분야에서 꾸준한 지지를 유지하고 있습니다.
IWMS의 복잡성으로 인해 도입에 더 긴 기간(대개 6-12개월)이 필요한 반면, CMMS는 기술자 중심의 워크플로우를 통해 더 신속한 가치 실현을 가능하게 합니다. 2024년 Planon이 자사의 IWMS 아키텍처 내에 CMMS를 통합함에 따라, 부문 간의 경계가 모호해졌습니다. Archibus는 2025년에 디지털 트윈을 통한 시각화 기능을 도입하여 기능적 격차를 좁혔지만, 그 가치 제안의 근간에는 여전히 CAFM 기반이 자리 잡고 있습니다. 시장의 양극화는 계속되고 있으며, 포춘 500에 선정된 부동산 소유주는 IWMS를 중심으로 통합을 추진하고, 중견 산업 기업은 CMMS의 단순성을 중시하며, 상업용 부동산 그룹은 CAFM에 대한 익숙함과 IWMS로의 선택적 업그레이드 사이에서 균형을 맞추고 있습니다.
2025년에는 클라우드 솔루션이 매출의 72.12%를 차지하며, 2031년까지 연평균 성장률(CAGR) 11.30%로 성장을 이어갈 전망입니다. 이는 구독 방식의 높은 비용 대비 효과, 지속적인 AI 업데이트, IT 운영 비용 절감을 반영한 결과입니다. Oracle이 Primavera를 Oracle Cloud Infrastructure로 이전함에 따라, 클라우드 도입에 있어 시설 관리(FM) 소프트웨어 시장 규모는 급속히 확대되었으며, 2024년에는 신규 고객의 78%가 SaaS를 선택했습니다. 데이터 주권이 중시되는 국방 분야나 규제 대상 부문에서는 여전히 On-Premise 도입이 이어지고 있습니다. 그러나 연구개발비 지출은 클라우드 기능 강화에 중점을 두고 있습니다. 하이브리드 도입은 보안과 분석의 요구를 모두 충족시킵니다. SAP S/4HANA for Real Estate를 활용함으로써 병원은 기밀성이 높은 병실 배정 정보를 On-Premise에서 관리하면서, Azure 상에서 가동 현황에 관한 분석 정보를 처리할 수 있게 됩니다.
멀티테넌트의 경제성 덕분에 순수 SaaS 벤더는 기존 가격보다 40-50% 저렴한 가격 책정이 가능해졌습니다. ServiceChannel은 2024년에 1,400만 건의 작업 지시를 처리하며 확장성의 이점을 입증했습니다. ISO 27001 인증은 표준이 되었으며, Eptura와 Planon은 모두 2024년에 준수를 달성하여 기업의 보안 우려를 해소했습니다. 앞으로 클라우드 도입으로 인해 On-Premise 지원의 이익률은 축소될 것으로 예상되는 반면, AI, 디지털 트윈, IoT 텔레메트리를 중심으로 한 생태계 파트너십은 촉진될 전망입니다.
지역별 분석
북미는 2025년 매출의 37.46%를 차지했으며, 뉴욕이나 샌프란시스코와 같은 도시에서 에너지 벤치마킹을 의무화하는 엄격한 성능 조례가 견인차 역할을 했습니다. 미국 연방조달청(GSA)이 2024년에 제정한 디지털 빌딩 관리 의무화로 인해 3억 4,000만 달러 규모의 조달 기회가 창출되었습니다. 캐나다는 약 2년 뒤처져 있지만, 브리티시컬럼비아주의 2024년 건축기준법 개정에 따라 밴쿠버에서의 도입이 가속화되었습니다. 멕시코에서는 니어쇼어링 붐으로 인해 제조업체들이 가동 시간을 최우선으로 삼은 결과, 2024년 CMMS 시장은 28%의 성장을 기록했습니다.
유럽에서는 2024년 개정된 EPBD(에너지 성능에 관한 건축물 지침)에 따라 신축 건물에 니어 제로 에너지 기준이 의무화되었으며, 독일의 5억 유로(5억 6,500만 미 달러) 규모의 보조금이 IWMS 및 에너지 플랫폼에 투입되었습니다. 프랑스와 북유럽 국가들도 독일과 유사한 인센티브를 도입하고 있는 반면, 영국의 2025년 건축물 안전법에서는 유지보수 문서 작성과 관련된 규정이 강화되어 CMMS 수요가 증가하고 있습니다.
아시아태평양은 중국의 스마트 시티 투자와 인도의 지자체 자산 디지털화에 힘입어 2031년까지 연평균 성장률(CAGR)이 26.30%에 달하며 가장 빠르게 성장하고 있는 지역입니다. 일본의 ‘사회 5.0’ 프로그램에서는 2024년에 2만 3,000동의 공공 건축물이 국가 IoT 백본과 상호 연결되었습니다. 한국은 스마트 빌딩으로의 개보수에 7,800억 원(5억 9,000만 달러)을 배정했습니다. 호주의 2024년 ‘국가 건축 기준법’ 개정에 따라 에너지 모델링이 의무화되었으며, 시드니와 멜버른에서는 SaaS형 에너지 관리 서비스 계약 건수가 증가하고 있습니다.
중동 수요는 메가 프로젝트에 집중되어 있습니다. 사우디아라비아의 NEOM에서는 종단간 자산 모니터링을 위해 IBM TRIRIGA와 Siemens Desigo CC를 통합했습니다. 두바이 시 당국의 2025년 규정에 따라 20층을 초과하는 고층 빌딩에 디지털 트윈 도입이 의무화되어, IWMS의 지속적인 도입이 보장되고 있습니다. 아프리카는 아직 발전 단계에 있지만, 나이지리아가 국가 건축 기준을 개정함에 따라 성장세가 가속화되고 있습니다. 남미의 성장세는 브라질이 주도하고 있으며, 상파울루시의 2024년 성과법에 따라 IWMS의 보급이 가속화되었습니다. 칠레에서는 친환경 건물에 대한 인센티브가 도입된 반면, 아르헨티나에서는 거시경제적 역풍으로 인해 지출이 억제되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHSAccording to Mordor Intelligence, the facility management software market size is expected to increase from USD 2.65 billion in 2025 to USD 2.98 billion in 2026 and reach USD 4.95 billion by 2031, growing at a CAGR of 10.68% over 2026-2031.
This report is Segmented by Software Type (CAFM, IWMS, and CMMS), Deployment Model (Cloud, On-Premise, and Hybrid), End User (Commercial, Institutional, Public Infrastructure, Industrial, and More), Functionality (Asset Management, Maintenance Management, Space Management, and Energy Management), and Geography. Market Forecasts are Provided in Terms of Value (USD).
Global Facility Management Software Market Trends and Insights
Growing Adoption of Cloud-Based SaaS Platforms
Subscription economics convert capital expenditure into operating expenses, broadening access for mid-market buyers while shortening deployment cycles from 18 months to roughly six months. ServiceNow's workplace suite secured 1,200 enterprise customers in 2025, citing pricing flexibility as the top factor. Multi-tenant architectures enable vendors to continuously push AI updates, a benefit that on-premises systems lack. Such agility strengthens vendor lock-in and raises switching costs, underpinning sustained double-digit expansion.
Integration of IoT Sensors for Predictive Maintenance
Sensor proliferation enables a shift from reactive to predictive maintenance, resulting in up to 40% lower downtime. Fracttal's roll-out of 50,000 vibration sensors across Latin American plants detected failures 72 hours in advance and saved USD 12 million in 2024. Edge computing and 5G connectivity enable sub-second alerts, while partnerships, such as SAP's 2025 tie-up with Siemens' MindSphere, integrate telemetry with asset histories for optimized spare-part planning.
Legacy System Integration Complexities
Proprietary protocols inflate project costs by 40-60%, with Siemens Desigo CC controllers requiring custom middleware for third-party IWMS integration. Honeywell's 2024 launch of 47 pre-built connectors reduced some friction, yet 38% of projects still exceeded budgets. Healthcare campuses illustrate the challenge: a 12-building migration to Johnson Controls OpenBlue lasted 14 months due to pneumatic legacy controls.
Other drivers and restraints analyzed in the detailed report include:
- Rising Focus on Sustainability and Energy Efficiency
- Proliferation of Hybrid-Work Models Driving Space-Optimization Tools
- High Up-Front Implementation and Training Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Integrated workplace management systems represented the fastest-growing segment, with a 16.80% CAGR through 2031. However, computer-aided facility management retained 41.40% of the facilities management software market share in 2025. Large enterprises favor IWMS for consolidated lease, capital project, and energy analytics, as evidenced by deployments of IBM TRIRIGA and Oracle Primavera Unifier. Computerized maintenance management systems appeal to asset-intensive verticals, with mobile-first vendors such as UpKeep and MaintainX posting 89% adoption within 60 days. The facilities management software market size for IWMS is forecast to expand rapidly as CFOs strive to replace three or more point solutions by 2027, while CAFM remains entrenched in sectors prioritizing rapid roll-out and lower complexity.
IWMS complexity demands longer roll-out horizons, often six to 12 months, while CMMS achieves faster time to value technician-centric workflows. Planon's integration of CMMS within its IWMS architecture during 2024 blurred segment lines. Archibus introduced digital-twin visualization in 2025 to narrow capability gaps, although its CAFM roots still underpin its value proposition. Market bifurcation persists: Fortune 500 landlords consolidate around IWMS, mid-market industrial players lean toward CMMS simplicity, and commercial real-estate groups balance CAFM familiarity with selective IWMS upgrades.
Cloud solutions accounted for 72.12% of the revenue in 2025 and are progressing at an 11.30% CAGR through 2031, reflecting subscription affordability, continuous AI updates, and lower IT overhead. The facilities management software market size for cloud deployments surged as Oracle migrated Primavera to Oracle Cloud Infrastructure, with 78% of new clients choosing SaaS in 2024. On-premises deployments persist in defense and regulated sectors where data sovereignty matters, but R&D outlays favor cloud enhancements. Hybrid deployments bridge the security and analytics needs; SAP S/4HANA for Real Estate enables hospitals to keep sensitive room assignments on-site while processing occupancy insights in Azure.
Multi-tenant economics allow pure-play SaaS vendors to undercut legacy pricing by 40-50%. ServiceChannel handled 14 million work orders in 2024, proving scalability benefits. ISO 27001 certification has become a standard, with Eptura and Planon both achieving compliance in 2024 to alleviate enterprise security concerns. Over time, cloud adoption is expected to compress margins for on-premises support while stimulating ecosystem partnerships centered on AI, digital twins, and IoT telemetry.
Complete Report Scope:
- By Software Type
- Computer-Aided Facility Management (CAFM)
- Integrated Workplace Management Systems (IWMS)
- Computerized Maintenance Management Systems (CMMS)
- By Deployment Model
- Cloud
- On-Premise
- Hybrid
- By End User
- Commercial
- Institutional
- Public Infrastructure
- Industrial
- Other End User Segments
- By Functionality
- Asset Management
- Maintenance Management
- Space Management
- Energy Management
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 37.46% of the revenue in 2025, driven by stringent performance ordinances in cities such as New York and San Francisco that require energy benchmarking. The U.S. General Services Administration's 2024 mandate for digital building oversight opened a USD 340 million procurement avenue. Canada trails by roughly two years, but British Columbia's 2024 code update accelerated adoption in Vancouver. Mexico's nearshoring boom spurred a 28% growth in CMMS in 2024, as manufacturers prioritized uptime.
Europe's revised 2024 EPBD compels near-zero energy in new buildings, funneling EUR 500 million (USD 565 million) in German grants toward IWMS and energy platforms. France and the Nordics mirror Germany's incentives, while the United Kingdom's 2025 Building Safety Act tightens maintenance documentation rules, boosting CMMS demand.
The Asia-Pacific region is the fastest-growing region, with a 26.30% CAGR through 2031, driven by China's smart-city investments and India's digitization of municipal assets. Japan's Society 5.0 program interconnected 23,000 public buildings with national IoT backbones in 2024. South Korea allocated KRW 780 billion (USD 590 million) for smart-building retrofits. Australia's 2024 National Construction Code revisions have enforced energy modeling, leading to increased SaaS energy-management subscriptions in Sydney and Melbourne.
Middle East demand centers on mega-projects: Saudi Arabia's NEOM integrated IBM TRIRIGA and Siemens Desigo CC for end-to-end asset oversight. Dubai Municipality's 2025 rule mandates the adoption of digital twins in towers exceeding 20 floors, ensuring sustained IWMS procurement. Africa is nascent, but it gains traction as Nigeria updates its national building code. South America's momentum rests in Brazil, where Sao Paulo's 2024 performance law accelerated IWMS penetration; Chile follows with green-building incentives, while Argentina's macroeconomic headwinds dampen spending.
- IBM Corporation
- Oracle Corporation
- SAP SE
- SIERRA ODC Private Limited
- Trimble Inc.
- Broadcom Inc.
- Accruent LLC (Fortive)
- Planon Software
- Eptura
- UpKeep Technologies
- FTMaintenance (FasTrak)
- Brightly (Siemens)
- Infor (Hexagon)
- Limble CMMS
- MaintainX Inc.
- FMX (Facilities Management eXpress)
- eMaint (Fluke Corporation)
- Dude Solutions
- iOFFICE + SpaceIQ
- Archibus
- ServiceChannel
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Adoption of Cloud-Based SaaS Platforms
- 4.2.2 Integration of IoT Sensors for Predictive Maintenance
- 4.2.3 Rising Focus on Sustainability and Energy Efficiency
- 4.2.4 Proliferation of Hybrid-Work Models Driving Space-Optimization Tools
- 4.2.5 Smart-City Mandates in Emerging Economies
- 4.2.6 Increasing Use of Digital Twins for Asset Lifecycle Management
- 4.3 Market Restraints
- 4.3.1 Legacy System Integration Complexities
- 4.3.2 High Up-Front Implementation and Training Costs
- 4.3.3 Data-Privacy and Cyber-Security Concerns
- 4.3.4 Shortage of FM-Specific Data-Analytics Talent
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Software Type
- 5.1.1 Computer-Aided Facility Management (CAFM)
- 5.1.2 Integrated Workplace Management Systems (IWMS)
- 5.1.3 Computerized Maintenance Management Systems (CMMS)
- 5.2 By Deployment Model
- 5.2.1 Cloud
- 5.2.2 On-Premise
- 5.2.3 Hybrid
- 5.3 By End User
- 5.3.1 Commercial
- 5.3.2 Institutional
- 5.3.3 Public Infrastructure
- 5.3.4 Industrial
- 5.3.5 Other End User Segments
- 5.4 By Functionality
- 5.4.1 Asset Management
- 5.4.2 Maintenance Management
- 5.4.3 Space Management
- 5.4.4 Energy Management
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East
- 5.5.4.1 Saudi Arabia
- 5.5.4.2 United Arab Emirates
- 5.5.4.3 Turkey
- 5.5.4.4 Rest of Middle East
- 5.5.5 Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Nigeria
- 5.5.5.3 Rest of Africa
- 5.5.6 South America
- 5.5.6.1 Brazil
- 5.5.6.2 Argentina
- 5.5.6.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 IBM Corporation
- 6.4.2 Oracle Corporation
- 6.4.3 SAP SE
- 6.4.4 SIERRA ODC Private Limited
- 6.4.5 Trimble Inc.
- 6.4.6 Broadcom Inc.
- 6.4.7 Accruent LLC (Fortive)
- 6.4.8 Planon Software
- 6.4.9 Eptura
- 6.4.10 UpKeep Technologies
- 6.4.11 FTMaintenance (FasTrak)
- 6.4.12 Brightly (Siemens)
- 6.4.13 Infor (Hexagon)
- 6.4.14 Limble CMMS
- 6.4.15 MaintainX Inc.
- 6.4.16 FMX (Facilities Management eXpress)
- 6.4.17 eMaint (Fluke Corporation)
- 6.4.18 Dude Solutions
- 6.4.19 iOFFICE + SpaceIQ
- 6.4.20 Archibus
- 6.4.21 ServiceChannel
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment