|
시장보고서
상품코드
2124802
독일의 시설 관리 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Germany Facility Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
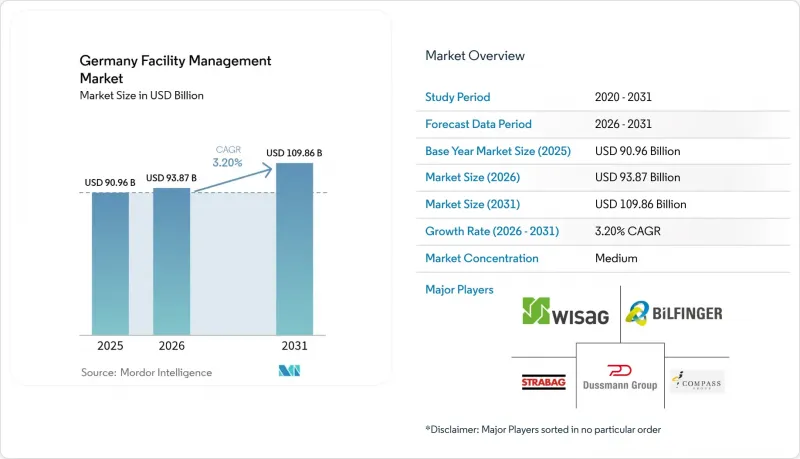
에 의하면, 독일의 시설 관리 시장 규모는 2025년에 909억 6,000만 달러로 평가되었고, 2026년 938억 7,000만 달러에서 2031년까지 1,098억 6,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 3.20%를 기록할 전망입니다.
본 보고서는 서비스 유형(하드 서비스 및 소프트 서비스), 제공 형태(사내 제공 및 외부 위탁), 최종 사용자 산업(상업, 호스피탈리티, 공공·인프라, 의료, 산업·공정, 기타 최종 사용자 산업)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
독일의 시설 관리 시장 동향 및 인사이트
엄격한 에너지 효율 규제
'Gebaudeenergiegesetz(건축물 에너지법)'에 따르면, 2024년 이후 신설되는 난방 시스템의 경우 열의 최소 65%를 재생에너지 원에서 확보해야 할 의무가 부과되어, 이에 따라 사업자는 보일러, 칠러 및 배관망의 교체를 강요받고 있습니다. 12kW를 초과하는 HVAC 장치는 인증된 전문가의 정기적인 에너지 검사를 통과해야 하며, 기한을 넘길 경우 소유주에게 벌금이 부과됩니다. 또한, ‘에너지 효율법’에 따른 보충 규정에 따라 기업은 소비량의 90%를 포괄하는 에너지 관리 시스템을 도입하고 감축 로드맵을 공표해야 합니다. 이러한 의무로 인해 모니터링 센서, 분석 대시보드, 그리고 에너지 절감 효과를 보장하는 성과 계약 서비스에 대한 수요가 증가하고 있습니다. 감사, 리트로커미셔닝 및 자금 조달 옵션을 패키지로 제공할 수 있는 서비스 제공업체는 독일의 시설 관리 시장에서 경쟁 우위를 확보하게 됩니다.
ESG 규정 준수 열기
‘기업 지속가능성 보고 지침’에 따라 비재무 보고서를 작성하는 독일 기업의 수는 3배로 증가하여 2026년까지 약 15,000개사에 달할 전망입니다. 건물은 국내 CO2 배출량의 약 30%를 차지하고 있어, 시설 운영은 영향이 큰 중점 분야가 되고 있습니다. DGNB의 ‘이중 중요성(double materiality)’ 관점에 따라, 기업은 자사의 활동이 사람과 지구에 어떤 영향을 미치는지, 또한 지속가능성 리스크가 수익에 어떤 영향을 미치는지를 공개해야 할 의무가 있습니다. 이에 대응하여 각 서비스 제공업체들은 현재 이산화탄소 배출량 기준치, 재생에너지 조달 계획, 폐기물 감축 KPI를 서비스 수준 계약(SLA)에 반영하고 있습니다. ISS가 그룹 ESG 책임자를 임명한 것과 같은 주목할 만한 인사 이동은 이러한 실적이 입찰 평가나 프로젝트 수주에 영향을 미치고 있음을 여실히 보여주고 있습니다. 이러한 움직임에 따라 독일의 시설 관리 시장은 검증된 배출량 감축과 연계된 성과 연계형 가격 책정 방식으로 나아가고 있습니다.
높은 초기 도입 비용
에너지 순수 플러스를 달성하는 개보수 공사, 첨단 센서, 부지 내 재생에너지 설비에는 경기 침체기에 예산을 압박할 수 있는 설비 투자가 필요한 경우가 적지 않습니다. 부동산 부문에서는 2023년 거래액이 52% 감소한 317억 유로(369억 4,000만 달러)를 기록하며, 대규모 개보수를 위한 대출 환경이 어려워지고 있습니다. 소유주들 사이에서는 GEG가 의무화한 보일러 교체로 인해 임대료가 상승하여 임차인의 반발을 초래하고, 프로젝트 승인이 지연될까 우려하고 있습니다. 2025년 건설 지출은 3.5% 감소할 것으로 예측되므로, 단계적 도입, 리스 모델, 공공 보조금이 필수적인 자금 조달 수단이 될 것입니다. 이러한 지원이 없다면 일부 운영 사업자는 기술 투자를 미루거나 규모를 축소할 가능성이 있어, 단기적으로는 독일의 시설 관리 시장의 성장세가 둔화될 우려가 있습니다.
부문 분석
하드 서비스는 2025년 매출의 56.62%를 차지했습니다. 이는 HVAC(공조·환기·급배수)의 리트로커미셔닝이나 전기 안전 검사 등 규제 준수 업무에는 고도의 엔지니어링 전문 지식이 요구되기 때문입니다. 기계, 전기, 배관 각 팀은 GEG 기준치를 충족하기 위해 열화상 조사 실시, 온수 순환 회로의 밸런스 조정, 빌딩 자동화 로직 튜닝을 수행하고 있습니다. 자산 관리 컨설팅 회사는 전체 부동산의 60%가 건축된 지 30년이 넘은 노후화된 부동산 재고에 대해 수명 주기 계획을 수립하고 있습니다. 독일의 시설 관리 시장에서 하드 서비스의 규모가 법적으로 강제력 있는 성능 목표에 엄격하게 묶여 있는 가운데, 각 공급업체들은 문제 감지를 신속하게 하고 보증 청구를 추적하기 위한 센서 탑재 툴킷 및 클라우드 분석에 대한 투자를 진행하고 있습니다.
연평균 성장률(CAGR) 5.29%로 예측되는 ‘소프트 서비스’는 이용자의 웰빙을 중시하는 고용주의 태도를 반영하고 있습니다. 청소 기준이 고도화됨에 따라 영업 시간 외 청소에 UV-C 살균 로봇이 도입되는 한편, 호스피탈리티 수준의 프런트 직원 팀은 플렉스 데스크 관리 앱을 통해 하이브리드 근무 환경을 조성하고 있습니다. 경비원들은 안전 위반 사항과 일상적인 사건을 구분하는 AI 탑재 영상 분석 시스템을 점점 더 많이 도입하고 있습니다. 소덱소(Sodexo)사의 로봇 주방 활용 사례는 영양 균형을 해치지 않으면서 의료시설용 케이터링 처리 능력을 자동화를 통해 향상시키는 방법을 보여줍니다. 기술을 융합한 소프트 서비스에 대한 수요가 증가함에 따라, 가치 창출이 법적으로 의무화된 규정 준수 기준보다 웰니스 지표에 더 크게 좌우되는 상황임에도 불구하고, 2031년까지 독일의 시설 관리 시장에서 해당 기업의 점유율이 꾸준히 상승할 것으로 예측됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.14According to Mordor Intelligence, the Germany facility management market size was valued at USD 90.96 billion in 2025 and estimated to grow from USD 93.87 billion in 2026 to reach USD 109.86 billion by 2031, at a CAGR of 3.20% during the forecast period (2026-2031).
This report is Segmented by Service Type (Hard Services, and Soft Services), Offering Type (In-House, and Outsourced), End-User Industry (Commercial, Hospitality, Institutional and Public Infrastructure, Healthcare, Industrial and Process, and Other End-User Industries). The Market Forecasts are Provided in Terms of Value (USD).
Germany Facility Management Market Trends and Insights
Stringent Energy Efficiency Regulations
The Gebaudeenergiegesetz requires new heating systems installed from 2024 to derive at least 65% of heat from renewable sources, pushing operators to upgrade boilers, chillers, and distribution networks. HVAC units exceeding 12 kW must pass periodic energy inspections by certified experts, and owners face fines when deadlines lapse.Complementary rules under the Energy Efficiency Act oblige enterprises to deploy energy-management systems covering 90% of consumption and to publish reduction roadmaps. These mandates elevate demand for monitoring sensors, analytics dashboards, and performance contracting services that guarantee savings. Service providers able to bundle auditing, retro-commissioning, and financing options gain a competitive advantage in the Germany facility management market.
ESG Compliance Momentum
The Corporate Sustainable Reporting Directive will triple the number of German entities producing non-financial statements, reaching nearly 15,000 by 2026. Buildings contribute around 30% of national CO2 emissions, making facility operations a high-impact target. DGNB's "double materiality" lens obliges firms to disclose how their activities affect people and planet and how sustainability risks affect revenues. In response, providers now embed CO2 baselines, renewable sourcing plans, and waste-reduction KPIs into service-level agreements. High-profile appointments, such as ISS naming a Group Head of ESG, underline how credentials drive bid evaluation and project awards. This alignment is nudging the Germany facility management market toward outcome-based pricing tied to verified emissions cuts.
High Initial Implementation Costs
Energy-positive retrofits, advanced sensors, and on-site renewables often require capital outlays that stretch budgets during a downturn. The property sector saw deal volumes fall 52% to EUR 31.7 billion (USD 36.94 billion) in 2023, tightening credit for large upgrades. Owners worry that GEG-mandated boiler replacements might raise rents, provoking tenant resistance and delaying project approvals. Construction spending is projected to contract by 3.5% in 2025, so phased roll-outs, leasing models, and public grants become essential financing levers. Without these supports, some operators may defer or scale back technology investments, muting growth potential for the Germany facility management market in the near term.
Other drivers and restraints analyzed in the detailed report include:
- Digital Transformation and Smart Buildings
- Workforce Automation Momentum
- Cybersecurity and Data Privacy Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hard Services contributed 56.62% of 2025 revenue because regulatory compliance tasks such as HVAC retro-commissioning and electrical safety inspections demand deep engineering know-how. Mechanical, electrical, and plumbing teams schedule thermographic surveys, balance hydronic circuits, and tune building-automation logic to align with GEG thresholds. Asset-management consultancies overlay life-cycle planning on an aging real-estate stock where 60% of properties exceed 30 years. As the Germany facility management market size for Hard Services tightens around legally enforceable performance targets, suppliers invest in sensor-equipped toolkits and cloud analytics that speed issue detection and track warranty claims.
Soft Services, forecast at a 5.29% CAGR, mirror employers' focus on occupant well-being. Heightened cleaning standards integrate UV-C disinfection robots for after-hours sweeps, while hospitality-grade front-of-house teams curate hybrid-work experiences through flex-desk management apps. Security guards increasingly deploy AI-enabled video analytics that distinguish safety breaches from routine events. Sodexo's robotic kitchen use case shows how automation raises throughput in healthcare catering without compromising nutrition. The growing appetite for tech-infused Soft Services suggests that their Germany facility management market share will rise steadily through 2031, even though value creation remains tethered to wellness metrics more than mandated compliance thresholds.
Complete Report Scope:
- By Service Type
- Hard Services
- Asset Management
- MEP and HVAC Services
- Fire Systems and Safety
- Other Hard FM Services
- Soft Services
- Office Support and Security
- Cleaning Services
- Catering Services
- Other Soft FM Services
- Hard Services
- By Offering Type
- In-house
- Outsourced
- Single FM
- Bundled FM
- Integrated FM
- By End-user Industry
- Commercial (IT and Telecom, Retail and Warehousing)
- Hospitality (Hotels, Eateries, Restaurants)
- Institutional and Public Infrastructure (Govt, Education, Transport)
- Retail and Warehousing
- Healthcare (Public and Private Facilities)
- Industrial and Process (Manufacturing, Energy, Mining)
- Other End-user Industries (Multi-housing, Entertainment, Sports and Leisure)
List of Companies Covered in this Report:
- Strabag SE
- Bilfinger SE
- Dussmann Group
- Compass Group PLC
- Wisag Facility Service Holding GmbH
- Vinci SA
- Aramark
- ISS Facilities Services Inc.
- Sodexo
- Apleona GmbH
- Weidemann Gruppe GmbH
- Coor Group
- Ray Facility Management
- Gegenbauer Services GmbH
- SPIE Deutschland & Zentraleuropa
- Kluh Service Management GmbH
- Piepenbrock Dienstleistungen GmbH & Co. KG
- Sasse Group
- Hectas Facility Services
- Johnson Controls (Germany)
- Caverion Deutschland GmbH
- Engie Deutschland GmbH
- Siemens Smart Infrastructure
- CBRE GWS Germany
- Serco Limited (Germany)
- Mitie Deutschland
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.1.1 Current Occupancy Rates in Key Commercial Real Estate Segments
- 4.1.2 Profitability Benchmarks of Major FM Providers
- 4.1.3 Workforce Indicators - Labour Participation and Skill Availability
- 4.1.4 Facility Management Market Share (%) by Service Type
- 4.1.5 Facility Management Market Share (%) by Hard FM Services
- 4.1.6 Facility Management Market Share (%) by Soft FM Services
- 4.1.7 Urbanisation and Population Growth in Top Metros (Berlin, Munich, Hamburg, Cologne, Frankfurt)
- 4.1.8 Sector Investment Priorities in Germany's National Infrastructure Pipeline
- 4.1.9 Regulatory Drivers Specific to Labour and Safety Standards
- 4.2 Drivers
- 4.2.1 Stringent Energy Efficiency Regulations
- 4.2.2 ESG Compliance Momentum
- 4.2.3 Digital Transformation and Smart Buildings
- 4.2.4 Workforce Automation Momentum
- 4.3 Restraints
- 4.3.1 High Initial Implementation Costs
- 4.3.2 Cybersecurity and Data Privacy Concerns
- 4.4 Value Chain Analysis
- 4.5 PESTEL Analysis
- 4.6 Regulatory and Legislative Framework for Market Entrants
- 4.7 Impact of Macroeconomic Indicators on Facility Management Demand
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Services
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment and Funding Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Service Type
- 5.1.1 Hard Services
- 5.1.1.1 Asset Management
- 5.1.1.2 MEP and HVAC Services
- 5.1.1.3 Fire Systems and Safety
- 5.1.1.4 Other Hard FM Services
- 5.1.2 Soft Services
- 5.1.2.1 Office Support and Security
- 5.1.2.2 Cleaning Services
- 5.1.2.3 Catering Services
- 5.1.2.4 Other Soft FM Services
- 5.1.1 Hard Services
- 5.2 By Offering Type
- 5.2.1 In-house
- 5.2.2 Outsourced
- 5.2.2.1 Single FM
- 5.2.2.2 Bundled FM
- 5.2.2.3 Integrated FM
- 5.3 By End-user Industry
- 5.3.1 Commercial (IT and Telecom, Retail and Warehousing)
- 5.3.2 Hospitality (Hotels, Eateries, Restaurants)
- 5.3.3 Institutional and Public Infrastructure (Govt, Education, Transport)
- 5.3.3.1 Retail and Warehousing
- 5.3.4 Healthcare (Public and Private Facilities)
- 5.3.5 Industrial and Process (Manufacturing, Energy, Mining)
- 5.3.6 Other End-user Industries (Multi-housing, Entertainment, Sports and Leisure)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Strabag SE
- 6.4.2 Bilfinger SE
- 6.4.3 Dussmann Group
- 6.4.4 Compass Group PLC
- 6.4.5 Wisag Facility Service Holding GmbH
- 6.4.6 Vinci SA
- 6.4.7 Aramark
- 6.4.8 ISS Facilities Services Inc.
- 6.4.9 Sodexo
- 6.4.10 Apleona GmbH
- 6.4.11 Weidemann Gruppe GmbH
- 6.4.12 Coor Group
- 6.4.13 Ray Facility Management
- 6.4.14 Gegenbauer Services GmbH
- 6.4.15 SPIE Deutschland & Zentraleuropa
- 6.4.16 Kluh Service Management GmbH
- 6.4.17 Piepenbrock Dienstleistungen GmbH & Co. KG
- 6.4.18 Sasse Group
- 6.4.19 Hectas Facility Services
- 6.4.20 Johnson Controls (Germany)
- 6.4.21 Caverion Deutschland GmbH
- 6.4.22 Engie Deutschland GmbH
- 6.4.23 Siemens Smart Infrastructure
- 6.4.24 CBRE GWS Germany
- 6.4.25 Serco Limited (Germany)
- 6.4.26 Mitie Deutschland
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Technology-led Integrated FM (IoT, BMS, AI-based Predictive Maintenance)
- 7.3 ESG-Compliant FM Solutions Demand
- 7.4 Future Service-Model Shifts (Outcome-Based Contracts)
- 7.5 Data-Driven Energy Optimisation and Carbon Reporting Services