|
시장보고서
상품코드
2117447
미국의 타이어 시장 : 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)United States Tire - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
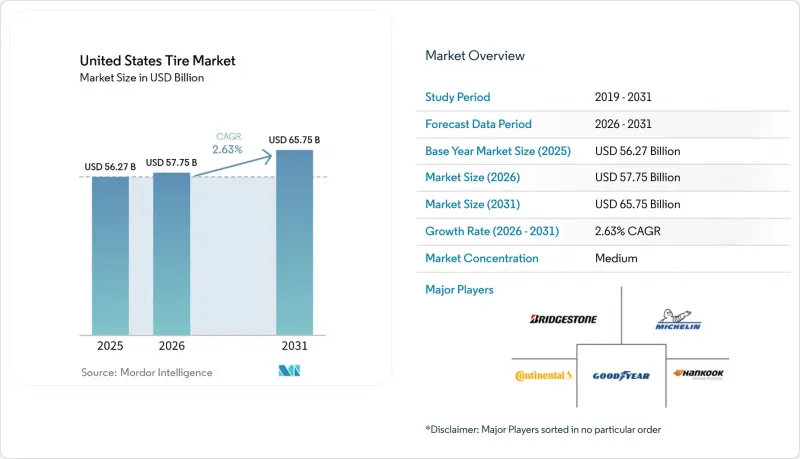
에 의하면, 미국 타이어 시장 규모는 2025년에 562억 7,000만 달러로 평가되었고 2026년에는 577억 5,000만 달러로 추정되고 있어 예측 기간(2026-2031년)에서 CAGR 2.63%로 성장을 지속하여, 2031년까지 657억 5,000만 달러에 이를 전망입니다.
본 보고서는 계절별(여름용 등), 타이어 구조별(레이디얼 타이어 등), 차종별(이륜차, 승용차 등), 용도별(온로드, 오프로드), 최종 사용자별(OEM, 애프터마켓),림 크기(15인치 미만, 15-20인치, 20인치 이상), 구동 방식(내연기관 차량 등)에 따라 분류되어 있습니다. 시장 전망은 금액(미 달러) 및 수량(단위)으로 제시되어 있습니다.
미국 타이어 시장 동향 및 인사이트
차량의 노후화와 주행 거리(VMT) 증가가 교체 수요를 끌어올리고 있습니다.
차량의 평균 사용 연수가 12.5년에 달함에 따라 국내 차량 보유 대수는 증가하고 있지만, 서스펜션의 마모가 트레드 열화를 가속화하기 때문에 타이어 교체 수요도 높아지고 있습니다. 2024년에는 주행 거리가 기하급수적으로 회복되어 팬데믹 이전 수준에 근접함에 따라 사용 빈도가 더욱 높아지고 있습니다. 연방고속도로청(FHWA)의 예측에 따르면, 미국의 총 주행 거리는 2019년부터 2050년까지 연평균 0.5-0.6% 증가할 것으로 보이며, 그중 경차는 0.4-0.5%,단축 트럭은 1.9-2.1%, 연결 트럭은 1.1-1.3%의 성장세가 예상됩니다. 이러한 차이가 중요한 이유는 상용차 부문에서 불균형한 교체 주기가 발생하기 때문입니다. 단일 차체의 배송용 밴이나 클래스 8 트랙터는 승용 세단에 비해 주행 거리가 3-5배 빠른 속도로 누적되기 때문에 타이어 수명이 단축되고, 차량 1대당 연간 구매 대수가 두 배로 늘어날 것입니다. 동시에, 미국 도로를 주행하는 소형 상용차의 평균 차령은 12년을 초과하고 있습니다. 이는 팬데믹 기간 동안공급망 혼란, 신차 가격 급등, 그리고 폐차 시기를 늦추게 한 내구성 향상으로 인해 발생한 기록적인 수치입니다.
SUV와 소형 트럭의 비중 증가가 평균 림 크기와 평균 판매 가격(ASP)을 끌어올리고 있다.
현재 미국에서 생산되는 신차의 5분의 3을 SUV와 소형 트럭이 차지하고 있으며, 이들은 보통 17-20인치 휠을 장착하고 있습니다. 반면 세단의 경우 15-16인치 휠이 표준입니다. 이러한 대형 휠은 평균 가격을 높일 뿐만 아니라, 차량당 매출 증가에도 꾸준히 기여하고 있습니다. 자동차 제조업체들이 세단 일부 차종을 단계적으로 단종해 나가는 가운데, 더 큰 휠 크기는 과거의 프리미엄 기능에서 새로운 표준으로 자리 잡았습니다. 이러한 변화로 인해 제조업체의 이익률은 크게 개선된 반면, 소비자가 부담하는 교체 비용도 상승하여 결과적으로 미국 타이어 시장에서 상당한 가치 확대를 가져오고 있습니다.
천연고무 및 합성고무의 가격 변동
천연고무의 현물 가격은 2026년 2월부터 4월에 걸쳐 1kg당 205-206 미국 센트에 달하며, 1년 만에 최고치를 기록했습니다. 이는 천연고무 생산국 협회(ANRPC)가 2026년 세계 수요를 1,560만 톤, 생산량을 1,520만 톤으로 예측하여 6년 연속 공급 부족이 예상되기 때문입니다. 동남아시아의 2월부터 5월까지 이어지는 월동기 동안의 계절적 공급 제약, 기상 이변, 잎마름병 발생, 그리고 수확량이 감소하고 있는 노후화된 농장 등이 구조적 불균형을 더욱 악화시키고 있는 반면, 선물 시장의 투기적 포지션이 가격 변동을 확대시키고 있습니다.
부문 분석
2025년, 올시즌 타이어는 미국 시장을 휩쓸며 61.28%라는 견실한 점유율을 차지했습니다. 반면, 겨울용 타이어의 판매 대수는 점유율은 작지만, 안전 의식의 고조와 소비자의 선호도가 재편되고 있는 가운데 격화되는 폭설 등을 배경으로 2.65%라는 두드러진 연평균 성장률(CAGR)을 기록하고 있습니다.
겨울용 타이어는 현재 기존의 ‘스노우 벨트’ 지역을 넘어, 예측 불가능한 기상 패턴에 시달리고 있는 온대 지역까지 그 존재감을 넓혀가고 있습니다. 2024년에 도입된 ‘쓰리 피크 마운틴 스노우플레이크(Three Peak Mountain Snowflake)’ 인증은 제품 라인업에 명확한 차별화를 가져왔습니다. 기후 변화가 시장에 계속 영향을 미치는 가운데, 올시즌 타이어 제조업체들은 제품에 눈길 주행 기능을 탑재하고 있습니다. 이러한 추세는 타이어 시장에서 계절의 경계가 점차 모호해지고 있음을 보여줍니다.
2025년 미국 타이어 시장에서 레이디얼 타이어는 89.92%라는 압도적인 점유율을 차지하고 있으며, 이는 수십 년에 걸친 전략적 최적화와 세계 시장 확대를 반영한 것입니다. 한편, 에어리스 타이어는 점유율이 1% 미만으로 소폭에 그치고 있지만, 연평균 성장률(CAGR) 2.67%로 성장세를 보이고 있으며, 펑크 저항성을 중시하는 상용 분야를 타겟으로 하고 있습니다.
미쉐린의 ‘UPTIS’나 브리지스톤의 ‘Air Free’와 같은 콘셉트는 시장 수용을 향한 길을 제시합니다. 현재의 제조 비용과 승차감의 제약으로 인해 광범위한 보급은 제한되고 있지만, 기술의 진보는 장기적으로 동등한 수준에 도달할 가능성을 시사하고 있습니다. 이러한 진전은 미국 타이어 시장 상황에 큰 변화를 가져올 가능성이 있습니다.
2025년, 승용차는 미국 타이어 시장에서 65.37%라는 압도적인 점유율을 차지했으며, 전기화와 프리미엄 사후 장착 수요 증가라는 두 가지 요인의 뒷받침을 받아 연평균 성장률(CAGR) 2.76%라는 놀라운 급성장을 이룩했습니다. 한편, 전자상거래 물류에 힘입은 상용 경트럭 부문도 성장을 이뤘으나, 그 속도는 승용차에 미치지 못했습니다.
차량의 전동화가 진행됨에 따라, 증가하는 중량과 토크에 대응하기 위해 필수적인 고성능 컴파운드로의 전환이 두드러지고 있습니다. 한편, 라이드셰어링 및 구독 서비스는 구매 우선순위를 재정의하고 있으며, 기존의 개인 소유자 선호도보다 내구성을 중시하는 경향을 보이고 있습니다. 이러한 변화하는 동향은 승용차 부문의 우위를 높일 뿐만 아니라, 미국 타이어 시장 상황을 강화하는 결과로 이어집니다.
기타 혜택:
- Excel 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모·성장률 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.03According to Mordor Intelligence, the United States tire market size was valued at USD 56.27 billion in 2025 and is estimated at USD 57.75 billion in 2026, and is projected to reach USD 65.75 billion by 2031, at a CAGR of 2.63% during the forecast period (2026-2031).
This report is Segmented by Season (Summer and More), Tire Design (Radial and More), Vehicle Type (Two-Wheeler, Passenger Cars and More), Application (On-Road and Off-Road), End User (OEM and Aftermarket), Rim Size (Below 15 Inches, 15 To 20 Inches, and Above 20 Inches), and Propulsion (Internal-Combustion Vehicles and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
United States Tire Market Trends and Insights
Aging Vehicle Fleet and Higher VMT Boost Replacement Demand
The climbing average vehicle age to 12.5 years extends the domestic parc, yet lifts tire turnover as suspension wear accelerates tread degradation. Vehicle miles traveled rebounded exponentially in 2024, matching pre-pandemic levels and compounding usage intensity. The Federal Highway Administration forecasts total United States vehicle miles traveled will grow 0.5-0.6% annually from 2019 through 2050, with light-duty vehicles advancing 0.4-0.5%, single-unit trucks 1.9-2.1%, and combination trucks 1.1-1.3%. This divergence matters because commercial segments generate disproportionate replacement cycles-a single-unit delivery van or Class 8 tractor accumulates mileage three to five times faster than a passenger sedan, compressing tire life and multiplying annual purchases per vehicle. Simultaneously, the average age of light-duty vehicles on United States roads has climbed past 12 years, a record driven by pandemic-era supply-chain disruptions, elevated new-vehicle prices, and improved durability that defers scrapping.
SUV and Light-Truck Mix Lifts Average Rim Size And ASP
Currently, three-fifths of new vehicles produced in the United States are SUVs and light trucks, which typically utilize 17 to 20-inch rims, compared to the 15 to 16-inch rims that are standard for sedans. These larger rim formats not only command higher average prices but also consistently contribute to increased revenue per unit. As automakers continue to phase out several sedan lines, the larger wheel size has shifted from being a premium feature to becoming the new standard. This transition has significantly improved manufacturer profit margins while also raising the replacement costs borne by consumers, thereby driving substantial value expansion within the United States tire market.
Natural and Synthetic-Rubber Price Volatility
Natural-rubber spot prices reached 205-206 U.S. cents per kilogram in February through April 2026, approaching one-year highs, as the Association of Natural Rubber Producing Countries projected 2026 global demand of 15.6 million tons against production of 15.2 million tons-the sixth consecutive annual deficit. Seasonal supply constraints during Southeast Asia's February-to-May wintering period, weather disruptions, leaf-blight disease outbreaks, and aging plantations with declining yields compound the structural imbalance, while speculative positioning in futures markets amplifies price swings.
Other drivers and restraints analyzed in the detailed report include:
- Corporate and Federal Fuel-Efficiency Rules Favor Low-RR Radials
- Surge of Tire E-Commerce and Mobile Installers Widens Reach
- Faster EV Tire Wear Raises Warranty and Brand-Image Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, all-season tires dominated the United States market, capturing a robust 61.28% share. Meanwhile, winter tire units, although accounting for a smaller segment, are experiencing a notable CAGR of 2.65%, driven by heightened safety awareness and increasingly severe storms reshaping consumer preferences.
Winter tires are now expanding their presence beyond the traditional snowbelt regions, reaching temperate areas that are encountering unpredictable weather patterns. The introduction of the Three Peak Mountain Snowflake certification in 2024 has distinctly differentiated product offerings. As climate variability continues to influence the market, manufacturers of all-season tires are incorporating snow-capable features into their products. This trend indicates a gradual blurring of seasonal boundaries within the tire market.
In 2025, radials held a dominant 89.92% share of the United States tire market, which reflects decades of strategic optimization and global scaling. At the same time, airless tire models, despite maintaining a modest share of less than 1%, demonstrated growth with a CAGR of 2.67%, targeting commercial applications that emphasize puncture resilience.
Michelin's UPTIS and Bridgestone's Air Free concepts provide insights into the pathway toward market acceptance. Although current manufacturing costs and ride comfort limitations are restricting widespread adoption, advancements in technology indicate the potential for achieving long-term parity. This development could lead to a significant transformation in the United States tire market landscape.
In 2025, passenger cars commanded a dominant 65.37% share of the United States tire market, experiencing a surprising surge with a 2.76% CAGR, driven by the dual forces of electrification and a heightened demand for premium retrofits. While commercial light trucks, supported by e-commerce logistics, enjoyed growth, they lagged behind in pace.
As fleets electrify, there is a pronounced shift towards high-performance compounds, essential for handling added weight and torque. Meanwhile, ride-share and subscription services are redefining purchase priorities, placing a premium on longevity over traditional individual owner preferences. These evolving dynamics not only bolster the passenger segment's dominance but also strengthen the overall United States tire market landscape.
Complete Report Scope:
- By Season
- Summer
- Winter
- All-Season
- By Tire Design
- Radial
- Bias
- Non-pneumatic/Airless
- By Vehicle Type
- Two-Wheelers
- Passenger Cars
- Light Commercial Vehicles
- Heavy Commercial Trucks and Buses
- Off-the-Road and Specialty (OTR, Agriculture, Mining, Racing)
- By Application
- On-Road
- Off-Road
- By End User
- OEM
- Aftermarket
- By Rim Size
- Below 15 inches
- 15 to 20 inches
- Above 20 inches
- By Propulsion
- Internal-Combustion Vehicles
- Battery-Electric Vehicles
- Hybrid and Fuel-Cell Vehicles
List of Companies Covered in this Report:
- Michelin SCA
- Goodyear Tire & Rubber Co.
- Bridgestone Corp.
- Continental AG
- Hankook
- Yokohama Rubber Co.
- Pirelli & C. S.p.A.
- Sumitomo (Dunlop/Falken)
- Toyo Tire Corp.
- Kumho Tire Co.
- Cooper (Goodyear)
- BFGoodrich
- Nokian Tyres
- Nexen
- Giti Tire
- Sailun Group
- Titan International
- Carlisle Companies
- MRF Tyres
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Vehicle Fleet and Higher VMT Boost Replacement Demand
- 4.2.2 SUV and Light-Truck Mix Lifts Average Rim Size And ASP
- 4.2.3 Corporate and Federal Fuel-Efficiency Rules Favor Low-RR Radials
- 4.2.4 Surge of Tire E-Commerce and Mobile Installers Widens Reach
- 4.2.5 Domestic EV-Tire Capacity (E.G., Enso) Unlocks High-Margin Niche
- 4.2.6 State-Level Recycled-Rubber Mandates Spur Sustainable Lines
- 4.3 Market Restraints
- 4.3.1 Natural and Synthetic-Rubber Price Volatility
- 4.3.2 Import Tariffs/Trade Frictions Inflate Landed Costs
- 4.3.3 Faster EV Tire Wear Raises Warranty and Brand-Image Risk
- 4.3.4 Urban Shift to Ride-Sharing and Micromobility Trims Per-Capita Demand
- 4.4 Value/Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Season
- 5.1.1 Summer
- 5.1.2 Winter
- 5.1.3 All-Season
- 5.2 By Tire Design
- 5.2.1 Radial
- 5.2.2 Bias
- 5.2.3 Non-pneumatic/Airless
- 5.3 By Vehicle Type
- 5.3.1 Two-Wheelers
- 5.3.2 Passenger Cars
- 5.3.3 Light Commercial Vehicles
- 5.3.4 Heavy Commercial Trucks and Buses
- 5.3.5 Off-the-Road and Specialty (OTR, Agriculture, Mining, Racing)
- 5.4 By Application
- 5.4.1 On-Road
- 5.4.2 Off-Road
- 5.5 By End User
- 5.5.1 OEM
- 5.5.2 Aftermarket
- 5.6 By Rim Size
- 5.6.1 Below 15 inches
- 5.6.2 15 to 20 inches
- 5.6.3 Above 20 inches
- 5.7 By Propulsion
- 5.7.1 Internal-Combustion Vehicles
- 5.7.2 Battery-Electric Vehicles
- 5.7.3 Hybrid and Fuel-Cell Vehicles
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Michelin SCA
- 6.4.2 Goodyear Tire & Rubber Co.
- 6.4.3 Bridgestone Corp.
- 6.4.4 Continental AG
- 6.4.5 Hankook
- 6.4.6 Yokohama Rubber Co.
- 6.4.7 Pirelli & C. S.p.A.
- 6.4.8 Sumitomo (Dunlop/Falken)
- 6.4.9 Toyo Tire Corp.
- 6.4.10 Kumho Tire Co.
- 6.4.11 Cooper (Goodyear)
- 6.4.12 BFGoodrich
- 6.4.13 Nokian Tyres
- 6.4.14 Nexen
- 6.4.15 Giti Tire
- 6.4.16 Sailun Group
- 6.4.17 Titan International
- 6.4.18 Carlisle Companies
- 6.4.19 MRF Tyres
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment