

|
시장보고서
상품코드
2118127
생분해성 킬레이트제 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Biodegradable Chelating Agents - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
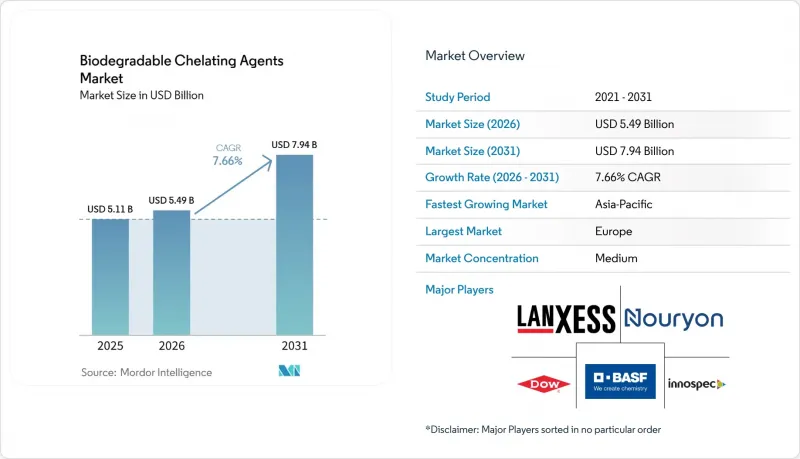
에 의하면, 생분해성 킬레이트제 시장 규모는 2025년 51억 1,000만 달러로 평가되었고, 2026년에는 54억 9,000만 달러로 추정되고, 2026-2031년 CAGR 7.66%로 성장을 지속할 전망이며, 2031년에는 79억 4,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 유형별(아미노산 킬레이트, 유기산 킬레이트 등), 제형별(액체, 분말, 과립), 최종 사용자 산업별(농업, 가정용 및 시설용 청소 등), 그리고 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 생분해성 킬레이트제 시장 동향 및 인사이트
생분해성 킬레이트제 채택을 촉진하는 엄격한 환경 규제
잔류성이 높은 화학 물질을 대상으로 하고, 생분해성에 대한 명확한 증거를 요구하는 환경 규제는 생분해성 킬레이트제 시장에 단기적으로 가장 강력한 추진력이 되고 있습니다. 제안된 EU 세제 규제안에서는 시행 후 6년 이내에 세제 캡슐의 필름, 8년 이내에 농축 유기 물질에 대해 생분해성 요건이 규정되어 있습니다. 이러한 일정에 따라 유럽의 배합 개발자들은 기존 킬레이트제 시스템을 재검토하고, 재배합 작업을 계획하며, 세정 제품에 이미 사용되고 있는 원료의 현황을 평가하기 위한 명확한 틀을 확보할 수 있습니다. 글루타민산 디아세테이트(GLDA)는 OECD 301D 시험에서 28일 이내에 60% 이상의 생분해율을 달성할 수 있어, 관련 세제 배합에 사용될 수 있음을 입증하고 있습니다. 규정 준수 요건의 변화에 따라, 조달에 관한 논의의 초점은 초기 원자재 비용에서 제품의 적합성, 문서화, 시험 기록, 그리고 고객 및 규제 당국에 대해 허용 가능한 환경 성능을 입증하는 능력으로 옮겨가고 있습니다. 이러한 변화는 생분해성 킬레이트제 시장공급업체에게도 이점이 되어, 다양한 최종 용도에 걸친 기술 데이터와 인증 증빙 자료를 제공할 수 있게 해줍니다.
가정용 및 산업용 지속 가능한 세정 제품에 대한 수요 증가
세정 용도는 생분해성 킬레이트제 시장의 주요 수요 기반이 되고 있습니다. 이는 제형 개발자들이 경수에 대한 우수한 성능, 신뢰할 수 있는 환경 실적, 실용적인 투여 특성, 그리고 확립된 제조 공정과 호환되는 성분을 찾고 있기 때문입니다. 글루탐산 디아세테이트(GLDA) 및 메틸글리신 디아세테이트(MGDA)는 기존 인산계 빌더 시스템의 대안으로, 유럽의 식기세척기용 및 세탁용 제품에 사용되고 있습니다. BASF는 2025년 4월, 가정용 및 상업 및 산업용 세척 용도를 위한 ‘Trilon G’를 출시했습니다. 이 제품의 탄소 원자 중 56%는 재생 가능 자원에서 유래합니다. 농축 액상 제품은 유효 성분 단위당 포장량 및 운송량을 줄일 수 있습니다. 이는 세정 제품의 주장을 검토하거나 공급업체의 제안을 고려할 때, 공급망의 배출량, 포장재 사용량, 유통 효율 및 제품 성능을 평가하는 소매 바이어에게 중요한 요소입니다. 친환경적이고 바이오 유래 성분에 대한 소비자의 선호도는 세정 용도의 생분해성 킬레이트제 시장에서 배합 변경의 상업적 타당성을 더욱 강화하고 있습니다.
기존 킬레이트제와 비교했을 때 높은 생산 비용 및 배합 비용
비용은 생분해성 킬레이트제 시장에 여전히 제약 요인으로 작용하고 있습니다. 특히, 환경 규제의 시행이 일관되지 않거나 고객이 원자재의 최근 가격에 중점을 둘 때 이 점이 두드러집니다. 생분해성 제품의 생산 비용은 등급이나 구매량에 따라 다르지만, 일반적으로 에틸렌디아민테트라아세트산(EDTA)의 1.5배에서 3배 정도 높습니다. 글루탐산 디아세테이트(GLDA)의 제조에는 발효 유래 L-글루탐산과 추가적인 유도체화 공정이 사용되는데, 이는 확립된 EDTA 제조 공정보다 더 엄격한 공정 관리가 필요합니다. 남아시아 및 동남아시아의 소규모 배합 제조업체들은 특정 세정 시스템에서 유효 투여량을 평가하거나, 성능 비교 시험을 실시하거나, 기존 제품 사양을 개정하기 위한 자원이 부족할 가능성이 있습니다. 기술적 인식이 제한적이기 때문에 사용 비용이 더 유리하더라도 표면적으로는 비용 면에서 불리한 상황이 지속되고 있습니다. 주요 제조업체들의 생산 능력 확충으로 인해 이러한 격차는 시간이 지남에 따라 줄어들 가능성이 있지만, 2020년대 후반까지는 큰 가격 변동이 예상되지 않습니다.
부문 분석
아미노산 킬레이트는 농업용 미량 영양소 공급 및 프리미엄 퍼스널케어 용도에 힘입어 2024년 매출의 37.82%를 차지했습니다. 그 가치는 칼슘과의 경쟁으로 인해 합성 철 킬레이트의 효능이 제한되기 쉬운 석회질 토양에서 특히 두드러집니다. 조사에 따르면, Zn-라이신 킬레이트는 처리되지 않은 대조군에 비해 수수 알곡 수확량을 39.9% 향상시키는 것으로 나타났습니다. 또한, 대두에 대한 엽면 시비 조사에서는 히스티딘 및 글루탐산 복합체를 사용한 경우, 황산염 대조군에 비해 망간 및 아연의 이동이 더 많이 관찰되었습니다. 구연산염 및 글루콘산염을 포함한 유기산 킬레이트는 두 번째로 큰 유형입니다. 이들은 식품 및 의약품 용도로 사용되고 있으며, 발효 유래 소재는 EDTA를 대체하는 저비용 대안으로 자리 잡고 있습니다.
GLDA 및 MGDA를 포함한 천연 킬레이트제는 2031년까지 연평균 성장률(CAGR) 8.52%를 나타낼 것으로 예측됩니다. 이러한 킬레이트제의 채택을 뒷받침하는 것은 광범위한 pH 범위에서 성능이 요구되는 시설용 세정제 및 식기세척기용 세제 용도입니다. GLDA는 이러한 용도에서 공정을 대폭 재설계하지 않고도 제품의 재조성을 지원할 수 있습니다. 폴리카르복실산 킬레이트는 공정 효율 향상을 통해 킬레이트제의 비용을 상쇄할 수 있기 때문에 펄프 및 제지 표백 분야에서 수요가 유지되고 있습니다. 또한, 천연 유래 제품은 COSMOS나 EU 에코라벨 인증 취득을 목표로 하는 제조업체의 요구에도 대응할 수 있습니다. BASF사의 ‘Trilon G’와 Nouryon사의 ‘Dissolvine GL’ 제품군은 이러한 용도 및 인증 취득 수요에 부응하고 있습니다.
지역별 분석
2025년 매출액 중 유럽이 35.44%를 차지했으며, 규제 주도형 배합 변경에서 여전히 주요 지역으로 자리 잡고 있습니다. 독일, 프랑스, 영국에서는 세정, 퍼스널케어, 농약, 펄프, 제지 각 분야를 통해 수요를 뒷받침하고 있습니다. REACH 규제의 지속적인 시행에 따라, 이러한 용도에서 EDTA에서 GLDA로의 전환이 촉진되고 있습니다. LANXESS는 수처리 용도를 위한 친환경 대체품으로 자사의 ‘Baypure’ 시리즈를 포지셔닝하고 있습니다. 또한, 유럽의 유통업체은 REACH 및 EU 에코라벨 요건을 준수해야 하는 고객을 대상으로 인증 취득을 지원하고 있습니다. 이탈리아와 러시아에서는 섬유 및 펄프 용도를 통해 추가적인 수요가 발생하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 8.42%로 확대될 것으로 예측되며, 가장 빠르게 성장하는 지역이 될 전망입니다. 중국과 인도는 주요 토양의 미량 영양소 결핍으로 인해 킬레이트화 비료 원료에 대한 전 세계 수요를 주도하고 있습니다. 수요는 붕소, 망간,아연, 철의 용도에 집중되어 있습니다. 양국 모두 킬레이트화 아연 및 철 원료의 사용을 지원하는 바이오포티피케이션(영양 강화) 프로그램을 시행하고 있습니다. 일본과 한국은 전자, 의약품, 퍼스널케어 분야에서 고순도이며 친환경적인 킬레이트제 수요처가 되고 있습니다. 국내 공급업체들은 국제적으로 인증된 공급망 요건을 충족하기 위해 문서화 체계를 정비하고 있습니다. 중국의 GLDA 및 MGDA 공급업체들은 2020년대 후반에 걸쳐 표준 등급 수출 제품에 대한 가격 경쟁을 심화시킬 가능성이 있습니다.
북미에서는 EPA의 ‘Safer Choice’ 프로그램과 캘리포니아주 및 워싱턴주의 주 차원 규제에 힘입어 꾸준한 속도로 전환이 진행되고 있습니다. 이러한 요건은 해당 시장에서 판매되는 세정제의 배합에 영향을 미치고 있습니다. 남미는 여전히 초기 단계에 있지만, 브라질에서는 대두, 과일, 채소에 대한 잠재적 수요가 예상됩니다. 수출 시장의 품질 요건으로 인해 고부가가치 작물을 위한 생분해성 킬레이트제 제품에 대한 관심이 높아지고 있습니다. 중동 및 아프리카에서는 수처리 회로용 생분해성 스케일 억제제에 대한 수요가 나타나고 있습니다. 물 부족과 해수 담수화에 대한 투자로 인해 사우디아라비아와 남아프리카공화국은 이 지역에서 주목할 만한 시장으로 부상하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 전망(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.01According to Mordor Intelligence, the biodegradable chelating agents market size is expected to grow from USD 5.11 billion in 2025 to USD 5.49 billion in 2026 and is forecast to reach USD 7.94 billion by 2031 at 7.66% CAGR over 2026-2031.
This report is Segmented by Type (Amino Acid Chelates, Organic Acid Chelates, and More), Formulation (Liquid, Powder and Granular), End-User Industry (Agriculture, Household and Institutional Cleaning, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Biodegradable Chelating Agents Market Trends and Insights
Stringent Environmental Regulations Promoting the Adoption of Biodegradable Chelating Agents
Environmental regulations targeting persistent chemical substances and requiring clear evidence of biodegradation provide the strongest near-term support for the biodegradable chelating agents market. The proposed EU Detergents Regulation sets biodegradability requirements for detergent-capsule films within 6 years of enactment and for concentrated organic substances within 8 years. These timelines give European formulators a clear framework for reviewing existing chelant systems, scheduling reformulation work, and assessing the status of raw materials already used in cleaning products. Glutamic acid diacetate (GLDA) can achieve more than 60% biodegradation within 28 days under OECD 301D testing, supporting its use in relevant cleaning formulations. Compliance requirements are shifting procurement discussions from initial material cost toward product eligibility, documentation, testing records, and the ability to demonstrate acceptable environmental performance to customers and regulators. This shift also benefits suppliers in the biodegradable chelating agents market by enabling them to provide technical data and certification evidence across several end uses.
Growing Demand for Sustainable Cleaning Products in Household and Industrial Applications
Cleaning applications represent a major demand base for the biodegradable chelating agents market, as formulators require strong hard-water performance, credible environmental credentials, practical dosing characteristics, and ingredients compatible with established manufacturing processes. Glutamic acid diacetic acid (GLDA) and methylglycinediacetic acid (MGDA) are used in European dishwasher and laundry products as replacements for older phosphate-based builder systems. BASF introduced Trilon G in April 2025 for home care and institutional and industrial cleaning applications, with 56% of its carbon atoms derived from renewable sources. Concentrated liquid products can reduce packaging and transport volumes per unit of active ingredient. This is relevant to retail buyers who evaluate supply chain emissions, packaging use, distribution efficiency, and product performance when reviewing cleaning product claims and supplier proposals. Consumer preference for eco-friendly and bio-based ingredients reinforces the commercial case for formulation changes in the biodegradable chelating agents market for cleaning applications.
Higher Production and Formulation Costs Compared with Conventional Chelating Agents
Cost remains a restraint for the biodegradable chelating agents market, particularly where environmental enforcement is less consistent and customers remain focused on the immediate price of raw materials. Biodegradable products typically carry a production cost premium of 1.5 to 3 times that of ethylenediaminetetraacetic acid (EDTA), depending on grade and purchase volume. Glutamic acid diacetic acid (GLDA) production uses fermentation-derived L-glutamic acid and additional derivatization steps, which require tighter process control than established EDTA routes. Small formulators in South and Southeast Asia may lack the resources to assess lower effective dosing rates in certain cleaning systems, conduct comparative performance trials, or revise existing product specifications. Limited technical awareness can sustain the apparent cost disadvantage even where the cost in use is more favorable. Capacity additions by major producers could narrow this gap over time, but substantial price changes are not expected before the late 2020s.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Use in Agriculture for Micronutrient Delivery and Crop Protection Formulations
- Rising Adoption in Personal Care, Food Processing, and Pharmaceutical Applications
- Performance Limitations Under Extreme pH, High Temperature, and High-Hardness Water Conditions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Amino acid chelates held 37.82% of revenue in 2024, supported by agricultural micronutrient delivery and premium personal care applications. Their value is particularly evident in calcareous soils, where calcium competition can limit the effectiveness of synthetic iron chelates. Research found that Zn-lysine chelates improved sorghum grain yield by 39.9% compared with untreated controls. Foliar research in soybean also found greater manganese and zinc translocation from histidine and glutamate complexes than from sulfate controls. Organic acid chelates, including citrates and gluconates, are the second-largest type. They are used in food and pharmaceutical applications, where fermentation-based materials offer lower-cost alternatives to EDTA.
Natural chelating agents, including GLDA and MGDA, are forecast to grow at an 8.52% CAGR through 2031. Their adoption is driven by institutional cleaning and automatic dishwashing applications that require performance across a broad pH range. GLDA can support reformulation without substantial process redesign in these applications. Polycarboxylic acid chelates retain demand in pulp and paper bleaching because process-efficiency gains can offset chelant costs. Natural products can also support manufacturers seeking COSMOS and EU Ecolabel certification. BASF's Trilon G and Nouryon's Dissolvine GL portfolio serve this application and certification demand.
Complete Report Scope:
- By Type
- Amino Acid Chelates
- Organic Acid Chelates
- Polycarboxylic Acid Chelates
- Natural Chelating Agents
- By Formulation
- Liquid
- Powder
- Granular
- By End-User Industry
- Agriculture
- Household and Institutional Cleaning
- Water Treatment
- Personal Care and Cosmetics
- Food and Beverage
- Pharmaceuticals
- Textile
- Pulp and Paper
- Industrial Manufacturing
- Other End-User Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Europe accounted for 35.44% of revenue in 2025 and remains the primary region for regulatory-driven reformulation. Germany, France, and the United Kingdom support demand through cleaning, personal care, agrochemical, pulp, and paper activities. Continued REACH enforcement has encouraged the shift from EDTA to GLDA in these applications. LANXESS positions its Baypure range as an environmentally compatible alternative for water treatment applications. European distributors are also providing certification support for customers working with REACH and EU Ecolabel requirements. Italy and Russia contribute additional demand through textile and pulp applications.
Asia-Pacific is projected to expand at an 8.42% CAGR through 2031, making it the fastest-growing region. China and India lead global demand for chelated fertilizer inputs due to micronutrient deficiencies in key soils. Demand is concentrated in boron, manganese, zinc, and iron applications. Both countries have biofortification programs that support the use of chelated zinc and iron inputs. Japan and South Korea represent demand pools for high-purity, eco-friendly chelates in electronics, pharmaceuticals, and personal care. Domestic suppliers are building documentation capabilities to serve internationally certified supply chains. Chinese GLDA and MGDA suppliers may intensify price competition in standard-grade export products through the late 2020s.
North America is transitioning at a measured pace, supported by the EPA Safer Choice program and state-level restrictions in California and Washington. These requirements affect cleaning formulations sold in those markets. South America remains at an earlier stage, with Brazil offering potential demand for soybeans, fruits, and vegetables. Export-market quality requirements are driving interest in biodegradable chelating agent products for higher-value crops. The Middle East and Africa present demand for biodegradable scale inhibitors in water treatment circuits. Water scarcity and desalination investment make Saudi Arabia and South Africa notable markets in this region.
- Aquapharm Chemical Limited
- AVA Chemicals
- BASF
- Cargill, Incorporated
- Dow
- Hebei Think-Do Chemicals Co., Ltd.
- Innospec
- Jungbunzlauer Suisse AG
- Kemira
- LANXESS
- Mitsubishi Chemical Corporation
- Nippon Shokubai Co., Ltd.
- Nouryon
- Shandong IRO Chelating Chemical Co., Ltd.
- Solvay
- Zschimmer & Schwarz Chemie GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent Environmental Regulations Promoting the Adoption of Biodegradable Chelating Agents
- 4.2.2 Growing Demand for Sustainable Cleaning Products in Household and Industrial Applications
- 4.2.3 Increasing Use in Agriculture for Micronutrient Delivery and Crop Protection Formulations
- 4.2.4 Rising Adoption in Personal Care, Food Processing, and Pharmaceutical Applications
- 4.2.5 Growing Consumer Preference for Eco-Friendly and Bio-Based Chemical Ingredients
- 4.3 Market Restraints
- 4.3.1 Higher Production and Formulation Costs Compared to Conventional Chelating Agents
- 4.3.2 Performance Limitations Under Extreme pH, High Temperature, and High-Hardness Water Conditions
- 4.3.3 Limited Market Awareness and Slow Adoption Across Small and Medium-Sized End Users
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Type
- 5.1.1 Amino Acid Chelates
- 5.1.2 Organic Acid Chelates
- 5.1.3 Polycarboxylic Acid Chelates
- 5.1.4 Natural Chelating Agents
- 5.2 By Formulation
- 5.2.1 Liquid
- 5.2.2 Powder
- 5.2.3 Granular
- 5.3 By End-User Industry
- 5.3.1 Agriculture
- 5.3.2 Household and Institutional Cleaning
- 5.3.3 Water Treatment
- 5.3.4 Personal Care and Cosmetics
- 5.3.5 Food and Beverage
- 5.3.6 Pharmaceuticals
- 5.3.7 Textile
- 5.3.8 Pulp and Paper
- 5.3.9 Industrial Manufacturing
- 5.3.10 Other End-User Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Aquapharm Chemical Limited
- 6.4.2 AVA Chemicals
- 6.4.3 BASF
- 6.4.4 Cargill, Incorporated
- 6.4.5 Dow
- 6.4.6 Hebei Think-Do Chemicals Co., Ltd.
- 6.4.7 Innospec
- 6.4.8 Jungbunzlauer Suisse AG
- 6.4.9 Kemira
- 6.4.10 LANXESS
- 6.4.11 Mitsubishi Chemical Corporation
- 6.4.12 Nippon Shokubai Co., Ltd.
- 6.4.13 Nouryon
- 6.4.14 Shandong IRO Chelating Chemical Co., Ltd.
- 6.4.15 Solvay
- 6.4.16 Zschimmer & Schwarz Chemie GmbH
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


