|
시장보고서
상품코드
2119103
중국의 자율주행 농업용 트랙터 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)China Autonomous Agricultural Tractor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
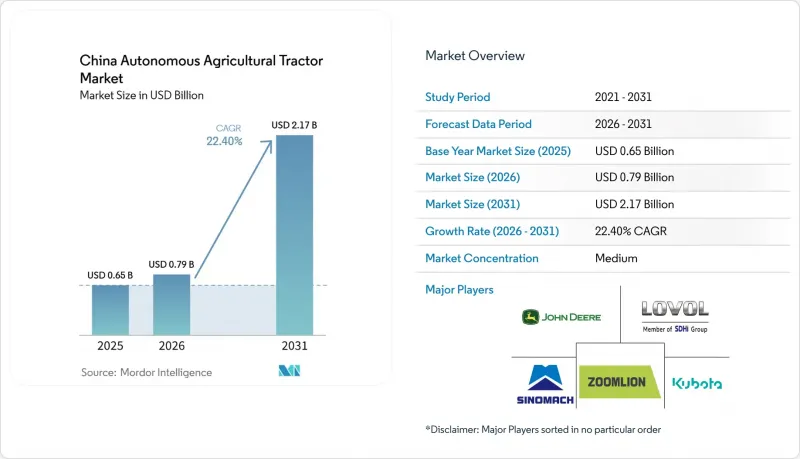
에 의하면, 중국의 자율주행 농업용 트랙터 시장은 2025년에 6억 5,000만 달러 규모로 평가되었고, 2026년에는 7억 9,000만 달러로 추정되고, 2031년까지 21억 7,000만 달러에 이를 것으로 예측됩니다.
예측 기간(2026-2031년) 동안 연평균 성장률(CAGR)은 22.4%를 나타낼 것으로 전망됩니다.
본 보고서는 마력별(30 HP 이하, 31-100 HP, 100 HP 이상), 자동화 수준별(완전 자율형 및 반자율형), 구동 방식별(디젤, 하이브리드, 배터리식 전기), 용도별(경운, 파종 등), 구성 부품별(GPS/GNSS, LiDAR 및 레이더 모듈 등), 그리고 농장 규모별(소규모, 중규모, 대규모)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
중국의 자율주행 농업용 트랙터 시장 동향 및 인사이트
정부 주도의 스마트 농업 및 북두(BeiDou) 도입
중국의 자율주행 농업용 트랙터 시장은 중국의 스마트 농업 정책 및 북두(BeiDou) 항법 기술의 도입과 밀접한 관련이 있습니다. 북두(BeiDou)를 지원하는 자율형 기기에 대한 정부의 지원과 농업 기계의 자율 주행 시스템을 규정하는 기준이 결합되어, 기기 구매자에게 조달, 인증 및 보조금 수령 자격에 관한 보다 명확한 체계가 제공되고 있습니다. 또한, 이러한 정책은 해외 위성 항법 플랫폼 전용으로 개발된 제품보다 국내 항법 인프라를 기반으로 설계된 시스템을 우대하는 것입니다. 농업농촌(MARA) 및 공업정보화부(MIIT)는 스마트 농업 장비의 현대화를 위한 보조금 정책과 우선순위를 지속적으로 수립하고 있습니다.
농업 인력 부족과 농촌 지역의 인건비 급등
중국의 자율주행 농업용 트랙터 시장은 봄철 경작 및 가을 수확기 인력 확보라는 과제에 직면해 있습니다. 인건비 급등과 계절적 인력 부족으로 인해 농가들의 노동력 절감 기술 도입 의지가 높아지고 있습니다. 특히 농업 보급 서비스가 기술 도입을 지원하고 있는 지역에서는 이러한 경향이 두드러집니다. 따라서 협동조합 경영자는 연간 인건비뿐만 아니라, 성수기의 인력 부족 위험을 완화할 수 있는 능력을 바탕으로 자율 주행 농업 기계를 평가할 수 있습니다. 이를 통해 안정적인 밭 작업을 유지하면서, 운전자가 여러 작업을 감독할 수 있는 트랙터의 가치 제안이 강화됩니다. 이러한 이점은 기계 가동률이 높고 초기 투자를 정당화할 수 있는 대규모 농장에서 가장 두드러지게 나타납니다.
소규모 농가에서의 고액 초기 비용과 불균일한 투자 수익률
완비된 자율 주행 트랙터에는 센서, 제어 장치, 내비게이션 소프트웨어, 통신용 하드웨어 등을 포함하여 막대한 초기 투자가 필요합니다. 정부의 보조금 프로그램을 통해 대상 스마트 농업 기계의 구입 비용은 경감되지만, 잔여 투자액을 소규모 경영자가 연간 사용만으로 회수하는 것은 여전히 어려운 경우가 있습니다. 또한, 대규모 농지를 위한 시스템은 불규칙한 구획에는 그다지 적합하지 않으며, 이동 및 설정에 시간이 걸리기 때문에 작업 효율이 떨어지게 됩니다. 협동조합 소유나 ‘서비스형 기계(MaaS)’ 모델은 진입 장벽을 낮출 수는 있지만, 농지 접근과 관련된 모든 과제를 해결할 수는 없습니다. 그 결과, 소규모 농가의 도입은 대규모 농장의 트랙터 군 도입에 비해 더 완만한 속도로 진행될 것으로 예측됩니다.
부문 분석
2025년, 31-100 HP 등급은 중국 자율주행 농업용 트랙터 시장 점유율의 38.9%를 차지했습니다. 이 출력 범위는 벼, 밀, 옥수수 재배에 적합하며, 국영 농장이나 확립된 협동조합에서 볼 수 있는 농지 규모에 부합합니다. 이 등급의 기존 섀시 설계에는 BeiDou RTK 사후 장착 시스템을 결합할 수 있어, 농장 경영자는 트랙터 전체를 교체하지 않고도 자동 유도 기능을 추가할 수 있습니다. 30 HP 이하의 기계는 소규모 밭이나 과수원에 적합하지만, 사후 장착 패키지의 이용 가능성이 점점 넓어지고 있음에도 불구하고 농지의 세분화로 인해 여전히 보급이 제한되고 있습니다.
100 HP를 초과하는 부문은 2026-2031년 연평균 성장률(CAGR) 23.4%로 확대될 것으로 예측됩니다. 이러한 수요는 광활한 농지를 통해 일일 작업 면적을 확대할 수 있는 헤이룽장성, 내몽골 자치구, 신장 위구르 자치구의 대규모 곡물 농장에 의해 뒷받침되고 있습니다. 2025년 9월, Zoomlion사는 광범위한 작업을 위해 설계된 1,200 HP의 하이브리드 트랙터 ‘DX7004’를 발표했습니다. 이 회사에 따르면, 이 모델은 하루에 480헥타르를 경작할 수 있어, 협동조합 구매자들에게 트랙터의 성능을 더 큰 규모의 농장 단위에 맞출 수 있는 수단을 제공합니다. 중출력 등급에서 고출력 등급으로의 조달 전환은 중국 자율 주행 농업용 트랙터 시장에서 통합 농장의 역할이 확대되고 있음을 반영합니다.
2025년, 중국의 자율주행 농업용 트랙터 시장에서 반자율형 시스템이 67.6%의 점유율을 차지했습니다. 이러한 시스템은 수동 조향 작업을 줄이면서도, 모니터링 및 밭에서의 의사 결정을 위해 운전자를 배치합니다. 이 방식은 완전 자율형 구성에 비해 보정 및 훈련 부담이 적어, 단계적으로 자동화를 도입하고 있는 협동조합에 적합합니다.
완전 자율 주행 시스템은 2026-2031년 연평균 성장률(CAGR) 22.5%를 나타낼 것으로 예측됩니다. 구매자들은 트랙터의 초기 자율 주행 수준만을 평가하는 것이 아니라, 해당 기술 아키텍처가 향후 업그레이드를 지원할 수 있는지 여부를 점점 더 중요하게 여기고 있습니다. 개방형 통합 시스템의 경우, 트랙터의 가동 기간 동안 추가 기능이 도입될 가능성이 있어 수명 주기 비용 산정에 영향을 미칠 수 있습니다. 자율 주행 시스템에 관한 국가 기준은 장비 인증을 위한 공통된 틀을 제공할 뿐만 아니라, 정부의 인센티브 프로그램 참여 자격을 뒷받침합니다. 이러한 규제 환경은 운전 지원 시스템에서 보다 고도화된 자율 주행 구성으로의 점진적인 전환을 촉진하고 있습니다. 반자율 주행 시스템이 당분간 우위를 점하고 있는 것은 숙련된 기술자나 운영자공급이 제한적인 상황과 일치합니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.03According to Mordor Intelligence, the China autonomous agricultural tractor market was valued at USD 0.65 billion in 2025 and is estimated to grow from USD 0.79 billion in 2026 and reach USD 2.17 billion by 2031, at a CAGR of 22.4% during the forecast period (2026-2031).
This report is Segmented by Horsepower (Up To 30 HP, 31-100 HP and Above 100 HP), by Automation Level (Fully Autonomous and Semi-Autonomous), by Drive Type (Diesel, Hybrid, and Battery-Electric), by Application (Tillage, Sowing, and More), by Component (GPS/GNSS, Lidar and Radar Modules, and More), and by Farm Size (Small, Medium, and Large). The Market Forecasts are Provided in Terms of Value (USD).
China Autonomous Agricultural Tractor Market Trends and Insights
Government-Led Smart Agriculture and BeiDou Deployment
The China autonomous agricultural tractor market is closely linked to the country's smart agriculture agenda and the adoption of BeiDou navigation technology. Government support for BeiDou-enabled autonomous equipment, together with standards governing automatic driving systems for agricultural machinery, provides equipment buyers with a clearer framework for procurement, certification, and subsidy eligibility. These policies also favor systems designed around domestic navigation infrastructure over products developed solely for foreign satellite-navigation platforms. The Ministry of Agriculture and Rural Affairs (MARA) and the Ministry of Industry and Information Technology (MIIT) continue to shape subsidy policies and priorities for intelligent agricultural equipment modernization.
Agricultural Labor Shortages and Rising Rural Labor Costs
The China autonomous agricultural tractor market addresses the challenge of securing workers during spring plowing and autumn harvest seasons. Rising labor costs and seasonal labor shortages are increasing farmers' willingness to adopt labor-saving technologies, particularly where agricultural extension services support technology adoption. Cooperative managers can therefore evaluate autonomous equipment based on its ability to reduce peak-season staffing risks, rather than annual wage costs alone. This strengthens the value proposition for tractors that can maintain consistent field operations while enabling operators to oversee multiple tasks. The benefits are most pronounced on larger farms, where higher equipment utilization can justify the initial investment.
High Upfront Cost and Uneven Return on Investment for Smallholders
A fully equipped autonomous tractor requires a substantial upfront investment, including sensors, control units, navigation software, and connectivity hardware. Although government subsidy programs help reduce acquisition costs for qualifying intelligent machinery, the remaining investment can still be difficult for small operators to recover through annual use. Large-field systems are also less suited to irregular plots, where travel and setup time reduce operational efficiency. Cooperative ownership and machinery as a service models can lower the entry barrier, but they do not eliminate all field-access challenges. As a result, adoption among smallholders is anticipated to progress more gradually than fleet deployment on larger farms.
Other drivers and restraints analyzed in the detailed report include:
- Precision Farming and Input Optimization Requirements
- Expansion of Large-Scale Farming and Agricultural Service Cooperatives
- Fragmented Farm Parcels and Limited Operating Economies of Scale
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The 31-100 HP class held 38.9% of the China autonomous agricultural tractor market share in 2025. This range is suited to rice, wheat, and corn operations and the field sizes found at state farms and established cooperatives. Existing chassis designs in this class can be paired with BeiDou RTK retrofit systems, giving farm operators a way to add automated guidance without replacing entire tractor fleets. Machines up to 30 HP serve small fields and orchards, but parcel fragmentation continues to limit their adoption even as retrofit packages become more widely available.
The above 100 HP segment is forecast to expand at a 23.4% CAGR between 2026 and 2031. Demand is supported by large grain farms in Heilongjiang, Inner Mongolia, and Xinjiang, where wide fields allow machines to cover more land per day. In September 2025, Zoomlion introduced the DX7004, a 1,200 HP hybrid tractor designed for large-area operations. The company stated that the model could cover 480 hectares per day, offering cooperative buyers a way to align tractor capacity with larger farm units. The shift from mid-range to higher-power procurement reflects the growing role of consolidated farms in the China autonomous agricultural tractor market.
Semi-autonomous systems held 67.6% of the China autonomous agricultural tractor market share in 2025. These systems reduce manual steering demands while retaining an operator for monitoring and field decisions. This arrangement requires less calibration and training than a fully autonomous configuration, making it suitable for cooperatives that are adding automation in stages.
Fully autonomous systems are forecast to expand at a 22.5% CAGR between 2026 and 2031. Buyers increasingly consider whether a tractor's technical architecture can support future upgrades, rather than evaluating only its initial autonomy level. Open-integration systems can alter lifetime cost calculations, as additional capabilities may be added throughout the tractor's operating life. National standards for autonomous driving systems provide a common framework for equipment certification and support eligibility for government incentive programs. This regulatory environment encourages a gradual transition from driver-assisted systems to more autonomous configurations. The near-term lead held by semi-autonomous systems is consistent with the limited availability of trained technicians and operators.
Complete Report Scope:
- By Horsepower
- Up to 30 HP
- 31-100 HP
- Above 100 HP
- By Automation Level
- Semi-Autonomous
- Fully Autonomous
- By Drive Type
- Diesel
- Hybrid
- Battery-Electric
- By Application
- Tillage
- Sowing
- Harvesting
- Orchard and Vineyard Operations
- By Component
- GPS/GNSS
- Sensors and Vision Systems
- Camera and Vision Systems
- LiDAR and Radar Modules
- Control and Navigation Software
- By Farm Size
- Small Farms (Less100 Hectares)
- Medium Farms (100-500 Hectares)
- Large Farms (More than 500 Hectares)
List of Companies Covered in this Report:
- YTO Group Corporation (China National Machinery Industry Corporation)
- Lovol Heavy Industry Co., Ltd.
- Zoomlion Heavy Industry Science and Technology Co., Ltd.
- Deere and Company
- CNH Industrial N.V.
- AGCO Corporation
- Kubota Corporation
- Yanmar Holdings Co., Ltd.
- TYM Corporation
- ISEKI & Co., Ltd.
- Shandong Wuzheng Group Co., Ltd.
- Jiangsu Yueda Intelligent Agricultural Equipment Co., Ltd. (Jiangsu Yueda Group Co., Ltd.)
- Changzhou Dongfeng Agricultural Machinery Group Co., Ltd.
- XAG Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government-led smart agriculture and BeiDou deployment
- 4.2.2 Agricultural labor shortages and rising rural labor costs
- 4.2.3 Precision farming and input optimization requirements
- 4.2.4 Expansion of large-scale farming and agricultural service cooperatives
- 4.2.5 Small-plot autonomy enabled by retrofit and shared-use models
- 4.2.6 China-specific localization of autonomous agricultural machinery
- 4.3 Market Restraints
- 4.3.1 High upfront cost and uneven return on investment for smallholders
- 4.3.2 Fragmented farm parcels and limited operating economies of scale
- 4.3.3 Data governance, cybersecurity, and cross-border technology constraints
- 4.3.4 Limited local service, calibration, and autonomous-system maintenance capacity
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Horsepower
- 5.1.1 Up to 30 HP
- 5.1.2 31-100 HP
- 5.1.3 Above 100 HP
- 5.2 By Automation Level
- 5.2.1 Semi-Autonomous
- 5.2.2 Fully Autonomous
- 5.3 By Drive Type
- 5.3.1 Diesel
- 5.3.2 Hybrid
- 5.3.3 Battery-Electric
- 5.4 By Application
- 5.4.1 Tillage
- 5.4.2 Sowing
- 5.4.3 Harvesting
- 5.4.4 Orchard and Vineyard Operations
- 5.5 By Component
- 5.5.1 GPS/GNSS
- 5.5.2 Sensors and Vision Systems
- 5.5.3 Camera and Vision Systems
- 5.5.4 LiDAR and Radar Modules
- 5.5.5 Control and Navigation Software
- 5.6 By Farm Size
- 5.6.1 Small Farms (Less100 Hectares)
- 5.6.2 Medium Farms (100-500 Hectares)
- 5.6.3 Large Farms (More than 500 Hectares)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 YTO Group Corporation (China National Machinery Industry Corporation)
- 6.4.2 Lovol Heavy Industry Co., Ltd.
- 6.4.3 Zoomlion Heavy Industry Science and Technology Co., Ltd.
- 6.4.4 Deere and Company
- 6.4.5 CNH Industrial N.V.
- 6.4.6 AGCO Corporation
- 6.4.7 Kubota Corporation
- 6.4.8 Yanmar Holdings Co., Ltd.
- 6.4.9 TYM Corporation
- 6.4.10 ISEKI & Co., Ltd.
- 6.4.11 Shandong Wuzheng Group Co., Ltd.
- 6.4.12 Jiangsu Yueda Intelligent Agricultural Equipment Co., Ltd. (Jiangsu Yueda Group Co., Ltd.)
- 6.4.13 Changzhou Dongfeng Agricultural Machinery Group Co., Ltd.
- 6.4.14 XAG Co., Ltd.