

|
시장보고서
상품코드
2119120
통신 장애 관리 소프트웨어 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Telecom Fault Management Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
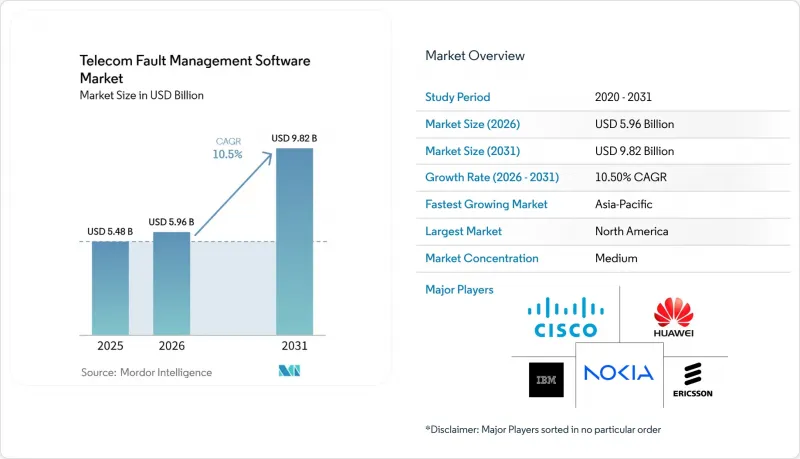
에 의하면, 통신 장애 관리 소프트웨어 시장 규모는 2025년에 54억 8,000만 달러로 평가되었습니다. 2026년 59억 6,000만 달러에서 2031년까지 98억 2,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 10.5%를 나타낼 전망입니다.
5G 독립형 네트워크, Open RAN, 클라우드 네이티브 네트워크 기능 및 멀티 벤더 아키텍처로 인해 통신 사업자가 분석해야 하는 경보의 양과 유형가 증가하고 있습니다. 본 보고서는 구성 요소별(소프트웨어 솔루션 등), 장애 관리별(알람 및 이벤트 관리 등), 네트워크 도메인별(무선 액세스 네트워크 등), 도입 형태별(On-Premise, 클라우드 기반), 기업 규모별(대기업, 중소기업), 용도별(네트워크 운영 센터 등), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 통신 장애 관리 소프트웨어 시장 동향 및 인사이트
5G 및 Open RAN에 따른 멀티 도메인의 복잡화
Open RAN에서는 기존에 한 벤더가 단일 기지국 시스템으로 제공하던 무선 유닛, 분산 유닛, 집중 유닛이 분리됩니다. 각 계층에서 서로 다른 알람 형식이 생성될 가능성이 있으므로, 기존의 OSS 도구로는 서비스 장애에 대한 공통된 관점을 형성하기 어렵습니다. 이러한 복잡성 때문에 통신 사업자들이 통신 장애 관리 소프트웨어 시장에서 멀티 도메인 플랫폼을 평가하고 있는 주된 이유입니다. 통신 사업자들이 멀티 벤더 RAN 환경 전반에서 자동화 용도를 운영하려고 함에 따라, 벤더 간 및 플랫폼 간 상호 운용성이 점점 더 중요해지고 있습니다. 캡제미니와 도이치 텔레콤은 도이치 텔레콤의 유럽 사업 전반에 걸친 O-RAN 및 레거시 RAN 환경을 위해 벤더에 구애받지 않는 서비스 관리 및 오케스트레이션 플랫폼도 개발했습니다. 장비 벤더에 관계없이 O1, E2, A1 인터페이스의 데이터를 수집할 수 있는 플랫폼은 대규모 통신 사업자의 도입을 지원하는 데 유리한 입장에 있습니다.
AI를 활용한 자율적인 네트워크 운영
AI는 파일럿 프로그램 단계에서부터 이벤트 상관 분석, 진단, 복구를 위한 운영 워크플로로 전환되고 있습니다. 도이체 텔레콤은 2025년 11월 독일에서 ‘RAN Guardian Agent’를 출시하여 주요 이벤트의 관리 시간을 수 시간에서 1분 미만으로 단축했으며, 도입 첫 달에만 100건 이상의 시정 조치를 자율적으로 실행했다고 보고했습니다. 노키아와 Google Cloud는 2026년 6월 파트너십을 확대하여 Gemini가 탑재된 6개의 에이전트를 ‘Nokia Assurance Center’에 통합했습니다. SaaS 버전은 2026년 9월에 출시될 예정입니다. 이러한 움직임으로 인해, AI를 활용한 근본 원인 분석과 자동 대응이 통신 업계의 장애 관리 소프트웨어 시장에서 공급업체 선정의 중요한 요소가 되고 있습니다. 관리형 서비스 제공업체는 더 광범위한 운영 기반에서 배울 수 있지만, 모든 활동을 온사이트에서 관리하는 통신 사업자는 운영 데이터를 재사용할 기회가 제한적입니다. 그 결과 발생하는 데이터 접근성의 차이는 경쟁 플랫폼 간에 자동화 품질이 얼마나 빠르게 향상되는지에도 영향을 미칠 수 있습니다.
레거시 시스템 통합 및 마이그레이션 비용
대형 통신 사업자는 종종 수십 년에 걸쳐 맞춤화된 OSS 통합에 의존하고 있어, 시스템 교체 프로그램은 비용이 많이 들고 기술적으로도 어려움을 수반합니다. 병렬 운영을 수반하는 마이그레이션 요건은 레거시 모듈이 폐기되기 전에 막대한 추가 비용을 발생시킬 가능성이 있습니다. 완전한 변혁 프로그램의 경우, 도입 기간이 길어지거나 운영 연속성을 신중하게 확보해야 할 수도 있습니다. 이러한 비용은 사우스바운드 인터페이스가 여러 장비 벤더에 걸쳐 SNMP, NETCONF 및 CLI를 지원해야 하는 경우 더욱 증가합니다. 그 결과, 통신 장애 관리 소프트웨어 시장에서는 레거시 시스템 통합 부담이 비교적 적은 신규 구축형 프라이빗 5G 네트워크 시장 진입 장벽이 더 낮다고 할 수 있습니다. 이는 또한 사내에서 필요한 통합 작업의 부담을 경감시켜 주는 매니지드 배포에 대한 수요를 뒷받침하는 요인이 되고 있습니다.
부문별 분석
2025년에는 소프트웨어 솔루션이 47.82%의 점유율을 차지했습니다. 이는 네트워크 도메인을 넘나들며 작동하는 분석 주도형 플랫폼에 대한 통신 사업자 수요를 반영한 것입니다. 통신 장애 관리 소프트웨어 시장에서는 네트워크 요소별로 장애를 평가하는 하드웨어 의존형 도구에서 벗어나려는 움직임이 진행되고 있습니다. 소프트웨어 계층에서는 RAN, 코어, 전송, 엣지 운영에서 발생하는 신호를 단일 워크플로우 내에서 상호 연관시킬 수 있습니다. 암호화된 트래픽으로 인해 순수한 소프트웨어 기반의 가시화가 제한되는 5G 독립형 코어 환경에서는 하드웨어 및 프로브 인프라가 여전히 중요한 역할을 수행하고 있습니다.
중소규모 통신 사업자들이 외부 운영 지원을 요구하는 가운데, 매니지드 서비스는 2031년까지 연평균 성장률(CAGR) 12%를 나타낼 것으로 예측됩니다. 또한, 통신 사업자가 현대화 프로젝트에서 통합, 구성, 마이그레이션 지원을 필요로 하는 경우, 전문 서비스 역시 여전히 필수적입니다. 매니지드 서비스를 제공함으로써 자본 요건을 줄이고, 사내 AI 운영 전문가의 필요성을 낮출 수 있습니다. 또한, 제공업체는 여러 고객 네트워크에 걸친 운영 패턴을 파악할 기회를 얻을 수 있습니다. 각 벤더는 지속적인 운영 요구를 지원하기 위해 소프트웨어 제품과 지속적인 자동화 서비스를 연계하고 있습니다.
경보 및 이벤트 관리는 경보 정규화가 다중 벤더 운영의 출발점으로 계속 남아 있기 때문에 2025년에 25.68%의 점유율을 차지했습니다. 자동화된 복구 및 폐쇄 루프 제어는 통신 사업자들이 기계에 의한 대응을 요구함에 따라 2031년까지 연평균 성장률(CAGR) 12.4%로 확대될 것으로 예측됩니다. 통신 장애 관리 소프트웨어 시장에서는 영향을 받은 서비스나 인프라 계층을 파악하기 위해 여전히 ‘장애 감지 및 식별’이 요구되고 있습니다. 그 후, ‘장애 상관 분석 및 근본 원인 분석’을 통해 사업자는 발생한 수많은 관련 알람 중에서 주요 문제를 파악할 수 있게 됩니다.
과거의 주요 성과 지표(KPI)를 기반으로 학습된 모델의 신뢰성이 높아짐에 따라, 예측형 장애 관리의 중요성이 커지고 있습니다. 인시던트, 티켓 및 워크플로우 관리는 기술적 감지와 현장 팀, 그리고 운영상의 책임을 연결합니다. 대규모 네트워크 환경에서의 근본 원인 분석에는 지식 그래프 기법이 점차 적용되고 있습니다. 이를 통해 대규모 운영 환경에서 폐쇄 루프 기능의 활용이 지원됩니다. 그러나 통신 사업자가 자동 복구를 광범위하게 확대하기 위해서는 여전히 신뢰할 수 있는 경보 의미론이 필요합니다.
지역별 분석
북미는 2025년에 34.86%의 점유율을 차지했으며, 이는 선진적인 5G 구축과 적극적인 OSS 현대화 프로그램에 힘입은 결과입니다. 이 지역의 통신 장애 관리 소프트웨어 시장 규모는 주요 통신 사업자들이 AI를 활용한 네트워크 운영에 투자하고 있음을 반영하고 있습니다. 2026년, NVIDIA는 통신 사업자의 AI 투자 주요 활용 사례로 네트워크 자동화가 고객 경험을 앞질렀다고 보고했습니다. 캐나다는 5G 구축 주기에 맞추어 진행되고 있는 반면, 멕시코의 통신 사업자들은 사내 자동화 자원이 제한적이라는 점을 보완하기 위해 관리형 장애 대응 서비스를 이용하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 11.8%를 나타낼 것으로 예측되며, 가장 빠르게 성장하는 지역이 될 전망입니다. 중국에서는 2026년 중반까지 280만 개 이상의 5G 기지국이 구축되어 대규모 경보 관리에 대한 큰 수요가 발생하고 있습니다. 대규모 5G 구축으로 인해 복잡한 네트워크 환경 전반에 걸친 장애 상관관계 분석 및 근본 원인 파악에 대한 수요가 높아지고 있습니다. 일본의 통신 사업자들도 AI를 활용한 유지보수 및 장애 원인 파악 시스템을 도입하고 있습니다. KDDI는 2026년 2월에 실시간 장애 원인 파악 AI 에이전트의 운영을 시작했으며, 소프트뱅크는 2026년 3월에 기지국 운영을 위한 멀티 에이전트 검증을 시작했습니다. 인도의 TRAI(통신규제청)가 정한 서비스 품질(QoS) 요건은 통신 사업자가 실시간 어슈어런스 및 대시보드를 도입해야 하는 규제상의 근거가 되고 있습니다.
유럽에서는 독일, 영국, 프랑스의 성숙한 운영을 바탕으로 2025년에도 여전히 큰 점유율을 유지했습니다. 도이치 텔레콤은 2025년에 에너지 효율을 고려한 자동화를 통해 5G 코어 네트워크에서 최대 65%의 에너지 절감을 실현했다고 보고했습니다. 유럽의 통신 사업자들은 유선 및 모바일 통신의 장애 대응 업무를 통합된 관리 환경으로 집약하고 있습니다. 중동에서는 5G 및 5.5G 서비스의 확대에 따라 지능형 운영 플랫폼 도입이 진행되고 있습니다. 아프리카와 남미는 여전히 도입 초기 단계에 있으며, 활동은 남아프리카공화국, 이집트, 브라질, 아르헨티나의 주요 통신 사업자에 집중되어 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.02According to Mordor Intelligence, the telecom fault management software market size was valued at USD 5.48 billion in 2025 and estimated to grow from USD 5.96 billion in 2026 to reach USD 9.82 billion by 2031, at a CAGR of 10.5% during the forecast period (2026-2031).
5G standalone networks, Open RAN, cloud-native network functions, and multi-vendor architectures are increasing the volume and variety of alarms that operators must interpret. This report is Segmented by Component (Software Solutions, and More), Fault Management (Alarm and Event Management, and More), Network Domain (Radio Access Network, and More), Deployment (On-Premises, and Cloud-Based), Enterprise Size (Large Enterprises, and SMEs), Application (Network Operations Center, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Telecom Fault Management Software Market Trends and Insights
5G and Open RAN Multi-Domain Complexity
Open RAN separates radio units, distributed units, and centralized units that one supplier previously delivered as a single base station system. Each layer can create different alarm formats, making it harder for traditional OSS tools to form a common view of a service failure. This complexity is a major reason operators are evaluating multi-domain platforms in the Telecom fault management software market. Interoperability among supplier platforms is becoming more important as operators seek to run automation applications across multi-vendor RAN environments. Capgemini and Deutsche Telekom also developed a vendor-independent service management and orchestration platform for O-RAN and legacy RAN environments across Deutsche Telekom's European operations. Platforms that can ingest O1, E2, and A1 interface data across equipment suppliers are better positioned to support large operator deployments.
AI-Enabled Autonomous Network Operations
AI is moving from pilot programs into operational workflows for event correlation, diagnosis, and recovery. Deutsche Telekom launched its RAN Guardian Agent in Germany in November 2025 and reported that it reduced major event management time from hours to less than 1 minute and autonomously initiated more than 100 remediation actions in its first month. Nokia and Google Cloud expanded their partnership in June 2026 to integrate 6 Gemini-powered agents into Nokia Assurance Center, with a SaaS release planned for September 2026. This direction makes AI-assisted root-cause analysis and automated response central to vendor selection in the Telecom fault management software market. Managed service providers can also learn from a broader operating base, while operators that retain all activity on-site have more limited opportunities to reuse operational data. The resulting difference in data access may affect how quickly automation quality improves across competing platforms.
Legacy-System Integration and Migration Cost
Large operators often rely on customized OSS integrations for decades, which makes replacement programs costly and technically difficult. Parallel-run migration requirements can add substantial cost before any legacy module is retired. Full transformation programs can require extended implementation periods and careful operational continuity. These costs increase when southbound interfaces must support SNMP, NETCONF, and CLI across multiple equipment suppliers. Consequently, the Telecom fault management software market has a clearer entry point in greenfield private 5G networks, where legacy integration debt is lower. This also supports demand for managed deployments that reduce the amount of internal integration work required.
Other drivers and restraints analyzed in the detailed report include:
- Real-Time Quality of Experience and SLA Assurance
- Cloud-Native OSS/BSS Modernization
- Multi-Cloud Security and Data-Residency Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software Solutions held 47.82% share in 2025, reflecting operator demand for analytics-driven platforms that work across network domains. The Telecom fault management software market industry is moving away from hardware-dependent tools that assess faults on a per-network-element basis. Software layers can correlate signals from RAN, core, transport, and edge operations in a single workflow. Hardware and Probe Infrastructure remain relevant in 5G standalone core environments where encrypted traffic restricts purely software-based visibility.
Managed Services is projected to grow at a 12% CAGR through 2031 as smaller operators seek external operational support. Professional Services also remains necessary when operators need integration, configuration, and migration support during modernization projects. Managed service delivery can lower capital requirements and reduce the need for in-house AI operations specialists. It also gives providers exposure to operating patterns across several customer networks. Vendors are connecting software products with ongoing automation services to support recurring operational needs.
Alarm and Event Management held 25.68% share in 2025 because alarm normalization remains the starting point for multi-vendor operations. Automated Remediation and Closed-Loop Control are projected to expand at a 12.4% CAGR through 2031 as operators seek machine-executed responses. The Telecom fault management software market still requires Fault Detection and Localization to identify the affected service or infrastructure layer. Fault Correlation and Root-Cause Analysis then helps operators distinguish a primary issue from the many related alarms it generates.
Predictive Fault Management is gaining relevance as models trained on historical key performance indicators become more reliable. Incident, Ticket, and Workflow Management links technical detection with field teams and operational accountability. Knowledge graph approaches are being applied to root cause analysis in large network environments. This supports the use of closed-loop functions at a large operating scale. However, operators still need reliable alarm semantics before they can broadly extend automated recovery.
Complete Report Scope:
- By Component
- Software Solutions
- Hardware and Probe Infrastructure
- Professional Services
- Managed Services
- By Fault Management Function
- Alarm and Event Management
- Fault Detection and Localization
- Fault Correlation and Root-Cause Analysis
- Predictive Fault Management
- Incident, Ticket, and Workflow Management
- Automated Remediation and Closed-Loop Control
- By Network Domain
- Radio Access Network
- Transport and Backhaul
- Fixed Access and Fiber
- IP and Core Network
- Cloud-Native Network Functions
- Edge and Private Networks
- By Deployment
- On-Premises
- Cloud-based
- By Enterprise Size
- Large Enterprises
- Small and Medium-Sized Enterprises
- By Application
- Network Operations Center Automation
- Service Assurance and Customer Experience
- Network Maintenance and Field Operations
- Network Security and Anomaly Response
- Enterprise and Private-Network Assurance
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America held 34.86% share in 2025, supported by advanced 5G deployments and active OSS modernization programs. The Telecom fault management software market size in the region reflects major carriers' investment in AI-driven network operations. In 2026, NVIDIA reported that network automation had overtaken customer experience as the leading AI investment use case for telecom operators. Canada follows 5G buildout cycles, while Mexican operators are using managed fault services to compensate for more limited internal automation resources.
Asia-Pacific is projected to grow at an 11.8% CAGR through 2031, making it the fastest-growing regional area. China had deployed more than 2.8 million 5G base stations by mid-2026, creating a significant need for large-scale alarm management. Large-scale 5G deployment is increasing the need for fault correlation and root-cause analysis across complex network estates. Japanese operators are also deploying AI-based maintenance and fault-cause identification systems. KDDI began operating a real-time fault-cause identification AI agent in February 2026, while SoftBank started multi-agent validation for base-station operations in March 2026. India's TRAI quality-of-service requirements add a regulatory reason for operators to adopt real-time assurance and dashboarding.
Europe maintained a substantial share in 2025 through mature operations in Germany, the United Kingdom, and France. Deutsche Telekom reported up to 65% energy savings in a 5G core network through energy-aware automation in 2025. European operators are consolidating fixed and mobile fault operations into unified management environments. The Middle East is adding intelligent operations platforms as 5G and 5.5G services expand. Africa and South America remain earlier-stage areas, with activity concentrated among major carriers in South Africa, Egypt, Brazil, and Argentina.
- International Business Machines Corporation
- Telefonaktiebolaget LM Ericsson
- Nokia Corporation
- Huawei Technologies Co., Ltd.
- Cisco Systems, Inc.
- Amdocs Limited
- Netcracker Technology Corporation
- Oracle Corporation
- NEC Corporation
- Hewlett Packard Enterprise Company
- Broadcom Inc.
- NETSCOUT Systems, Inc.
- Comarch SA
- TEOCO Corporation
- Subex Limited
- VIAVI Solutions Inc.
- Spirent Communications plc
- EXFO Inc.
- RADCOM Ltd.
- Infovista SAS
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 5G and Open RAN Multi-Domain Complexity
- 4.2.2 Real-Time Quality of Experience and SLA Assurance
- 4.2.3 Cloud-Native OSS/BSS Modernization
- 4.2.4 AI-Enabled Autonomous Network Operations
- 4.2.5 Network Energy Optimization Through Fault Intelligence
- 4.2.6 Network-Slice Revenue Protection and Assurance
- 4.3 Market Restraints
- 4.3.1 Legacy-System Integration and Migration Cost
- 4.3.2 Multi-Cloud Security and Data-Residency Complexity
- 4.3.3 Scarcity of Telco-Grade AI and Automation Talent
- 4.3.4 Inconsistent Alarm Semantics Across Disaggregated Network Domains
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software Solutions
- 5.1.2 Hardware and Probe Infrastructure
- 5.1.3 Professional Services
- 5.1.4 Managed Services
- 5.2 By Fault Management Function
- 5.2.1 Alarm and Event Management
- 5.2.2 Fault Detection and Localization
- 5.2.3 Fault Correlation and Root-Cause Analysis
- 5.2.4 Predictive Fault Management
- 5.2.5 Incident, Ticket, and Workflow Management
- 5.2.6 Automated Remediation and Closed-Loop Control
- 5.3 By Network Domain
- 5.3.1 Radio Access Network
- 5.3.2 Transport and Backhaul
- 5.3.3 Fixed Access and Fiber
- 5.3.4 IP and Core Network
- 5.3.5 Cloud-Native Network Functions
- 5.3.6 Edge and Private Networks
- 5.4 By Deployment
- 5.4.1 On-Premises
- 5.4.2 Cloud-based
- 5.5 By Enterprise Size
- 5.5.1 Large Enterprises
- 5.5.2 Small and Medium-Sized Enterprises
- 5.6 By Application
- 5.6.1 Network Operations Center Automation
- 5.6.2 Service Assurance and Customer Experience
- 5.6.3 Network Maintenance and Field Operations
- 5.6.4 Network Security and Anomaly Response
- 5.6.5 Enterprise and Private-Network Assurance
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Spain
- 5.7.3.6 Russia
- 5.7.3.7 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Australia
- 5.7.4.6 Rest of Asia-Pacific
- 5.7.5 Middle East
- 5.7.5.1 Saudi Arabia
- 5.7.5.2 United Arab Emirates
- 5.7.5.3 Turkey
- 5.7.5.4 Rest of Middle East
- 5.7.6 Africa
- 5.7.6.1 South Africa
- 5.7.6.2 Egypt
- 5.7.6.3 Rest of Africa
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 International Business Machines Corporation
- 6.4.2 Telefonaktiebolaget LM Ericsson
- 6.4.3 Nokia Corporation
- 6.4.4 Huawei Technologies Co., Ltd.
- 6.4.5 Cisco Systems, Inc.
- 6.4.6 Amdocs Limited
- 6.4.7 Netcracker Technology Corporation
- 6.4.8 Oracle Corporation
- 6.4.9 NEC Corporation
- 6.4.10 Hewlett Packard Enterprise Company
- 6.4.11 Broadcom Inc.
- 6.4.12 NETSCOUT Systems, Inc.
- 6.4.13 Comarch SA
- 6.4.14 TEOCO Corporation
- 6.4.15 Subex Limited
- 6.4.16 VIAVI Solutions Inc.
- 6.4.17 Spirent Communications plc
- 6.4.18 EXFO Inc.
- 6.4.19 RADCOM Ltd.
- 6.4.20 Infovista SAS
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


