|
시장보고서
상품코드
2119648
북미의 시설 관리 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)North America Facility Management - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
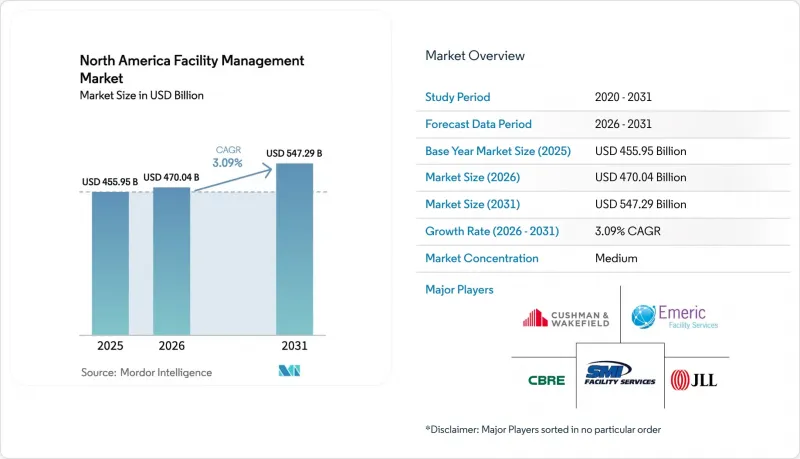
에 의하면, 북미의 시설 관리 시장 규모는 2025년에 4,559억 5,000만 달러로 평가되었고 2026년 4,700억 4,000만 달러에서 성장하여 2031년까지 5,472억 9,000만 달러에 이를 것으로 추정되고 있습니다.
예측 기간(2026-2031년) 동안의 연평균 성장률(CAGR)은 3.09%가 될 것으로 전망됩니다.
본 보고서는 서비스 유형(하드 서비스 및 소프트 서비스), 제공 형태(사내 제공 및 외부 위탁), 최종 사용자 산업(상업, 호스피탈리티, 공공·인프라, 의료, 산업·공정, 기타 최종 사용자 산업), 지역(미국, 캐나다, 멕시코)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
북미 시설 관리 시장 동향 및 인사이트
인프라 개발 확대
이 지역 전체에 걸친 연방, 주 및 지방 정부의 규제로 인해 건물 성능 기준이 높아졌으며, 자산 소유주들은 노후화된 공조(HVAC), 생명 안전 및 전기 시스템의 개조를 서둘러야 하는 상황에 처해 있습니다. 미국 연방조달청(GSA)의 2024년 P100 기준은 연방 정부 소유 부동산의 지속가능성과 회복력에 관한 기준을 강화하고 있으며, 민간 포트폴리오의 모델이 되고 있습니다. 멕시코에서는 니어쇼어링에 따른 산업 확장에 대응하는 움직임이 정치적 예산 제약을 상쇄하면서, 고사양 물류 및 조립 공간에 대한 수요를 뒷받침하고 있습니다. 캐나다에서는 기후 목표 달성을 목적으로 한 통일된 건축 기준에 따라 에너지 효율 향상을 위한 개보수 공사가 확대되고 있습니다. 그 결과, MEP(기계·전기·배관) 분야에 깊은 전문 지식을 갖춘 하드 서비스 계약업체들은 안정적이고 지속적인 수익원을 확보하고 있으며, 한편 기술 기반 모니터링 플랫폼은 북미 시설 관리 시장에서 규정 준수를 강화하고 자산의 수명 주기를 연장하고 있습니다.
빌딩 관리 분야의 아웃소싱 확대
기업 이사회에서는 FM을 단순한 비용 센터가 아닌 전략적 수단으로 자리매김하려는 경향이 강해지고 있습니다. ABM 인더스트리즈는 고객이 공급업체의 난립을 억제하고 단일 창구를 통한 책임 체계를 보장하는 통합형 서비스를 우선시한 결과, 2024년에 10억 달러를 넘는 신규 계약을 수주했습니다. 하드웨어와 소프트웨어를 결합한 계약은 규모의 경제성을 향상시키며, 대부분의 경우 안전성, 가동률, 에너지 목표와 연계된 성과 기반 KPI가 포함되어 있습니다. 의료 분야에서는 Medxcel과 같은 벤더 중립적 전략을 통해 사내 자원과 외부 위탁 비용을 최적화함으로써 3년 동안 1억 400만 달러의 비용 절감을 실현했습니다. 그 결과, 북미 시설 관리 시장에서 아웃소싱 비중이 확대되고 있으며, 투명한 성과 보고와 디지털 툴셋을 입증할 수 있는 공급업체들이 수년에 걸친 다중 거점 계약을 수주하고 있습니다.
디바이스 및 네트워크 취약점과 관련된 보안 우려
BMS(빌딩 관리 시스템) 및 IoT 엔드포인트에 대한 사이버 공격으로 인해 인명 안전, HVAC(공조·환기·난방), 그리고 접근 제어의 각 계층이 잠재적인 방해 행위에 노출되어 있으며, 시설 관리자의 27%가 지난 1년 동안 사고를 보고했습니다. 핵심 인프라 분야의 사이버 보험료는 급등하고 있어, 대규모 도입을 더욱 지연시키고 있습니다. 기밀 데이터나 미션 크리티컬 시스템을 보유한 의료시설 및 정부 기관 캠퍼스에서는 종단 간암호화,제로 트러스트 프레임워크, 연중무휴 24시간 위협 모니터링이 요구되고 있으며, 이로 인해 소규모 FM 제공업체의 진입 장벽이 높아지고, 북미 시설 관리 시장 전반에서 영업 주기가 장기화되고 있습니다.
부문 분석
CAGR은 2025년 북미 시설 관리 시장의 58.72%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 3.09%로 시장 전체의 확장과 발맞추어 성장하고 있습니다. 이 분야는 엄격한 MEP(기계·전기·배관) 유지 관리, 화재 안전 기준 준수, 구조 자산 보전을 통해 업무의 연속성을 뒷받침하고 있습니다. 건물 시스템의 노후화가 광범위하게 진행되고 있으며, 에너지 및 생명 안전에 관한 규제가 갱신됨에 따라 개보수 프로그램, 상태 기반 모니터링, 자산 수명 주기 계획에 대한 예측 가능한 수요가 발생하고 있습니다.
소프트 서비스는 규모는 작지만 웰니스, 보안, 컨시어지 서비스에 대한 기대에 힘입어 연평균 성장률(CAGR) 4.08%라는 빠른 속도로 성장하고 있습니다. 실내 공기질(IAQ) 관련 규정의 강화와 건강·안전 관련 인증 취득이 프리미엄 청소 패키지에 대한 수요를 촉진하고 있습니다. 사무실 지원 및 프런트 업무 분야에서는 스마트 사물함 및 방문객 관리 기술의 도입이 진행되면서 업무 범위가 확대되고 있습니다. 이러한 추세에 따라 통합형 공급업체는 하드 서비스의 정기 수익을 확보하는 동시에 소프트 서비스의 혁신적인 서비스를 교차 판매할 수 있게 되어, 결과적으로 북미 시설 관리 시장에서 지갑 점유율을 확대할 수 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.03According to Mordor Intelligence, the North America facility management market size was valued at USD 455.95 billion in 2025 and estimated to grow from USD 470.04 billion in 2026 to reach USD 547.29 billion by 2031, at a CAGR of 3.09% during the forecast period (2026-2031).
This report is Segmented by Service Type (Hard Services, and Soft Services), Offering Type (In-House, and Outsourced), End-User Industry (Commercial, Hospitality, Institutional and Public Infrastructure, Healthcare, Industrial and Process, and Other End-User Industries), and Geography (United States, Canada, and Mexico). The Market Forecasts are Provided in Terms of Value (USD).
North America Facility Management Market Trends and Insights
Increasing Infrastructure Development
Federal, state, and provincial mandates across the region elevate building performance thresholds, pushing asset owners to retrofit outdated HVAC, life-safety, and electrical systems. The U.S. General Services Administration's 2024 P100 standards strengthen sustainability and resiliency criteria for federal properties, setting a template for private portfolios. Mexico's push to accommodate nearshoring-driven industrial expansion offsets political budget constraints yet sustains demand for high-spec logistics and assembly space. In Canada, harmonized construction codes aimed at meeting climate targets are amplifying energy-efficiency retrofits. Hard-service contractors with deep MEP expertise are consequently seeing stable recurring revenue streams, while technology-enabled monitoring platforms reinforce compliance and extend asset life cycles within the North America facility management market.
Rising Outsourcing in Building Management
Corporate boards increasingly frame FM as a strategic lever rather than a commodity cost center. ABM Industries secured more than USD 1 billion in new contracts during 2024 as clients prioritized integrated offerings that limit vendor sprawl and guarantee single-point accountability. Bundled hard-plus-soft contracts improve economies of scale and often embed outcome-based KPIs tied to safety, uptime, and energy targets. For healthcare, vendor-neutral strategies such as Medxcel's generated USD 104 million savings over three years by fine-tuning in-house resources and third-party spend. As a result, the outsourced slice of the North America facility management market is widening, with providers that can demonstrate transparent performance reporting and digital toolsets attracting multi-year, multi-site deals.
Security Concerns Over Device and Network Vulnerabilities
Cyberattacks on BMS and IoT endpoints expose life-safety, HVAC, and access-control layers to potential sabotage, with 27% of facility managers reporting incidents over the past year. Insurance premiums for cyber coverage in critical infrastructure have spiked, further delaying large-scale rollouts. Healthcare and government campuses, sitting on sensitive data and mission-critical systems, demand end-to-end encryption, zero-trust frameworks, and 24/7 threat monitoring, raising barriers for smaller FM providers and elongating sales cycles across the North America facility management market.
Other drivers and restraints analyzed in the detailed report include:
- Heightened Safety and Security Needs
- Technological Advancements in Facility Management
- High Costs of Advanced Tech and Skilled Labor
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hard services account for 58.72% of the North America facility management market in 2025 and progress in lock-step with overall expansion at a 3.09% CAGR to 2031. This branch anchors operational continuity through disciplined MEP upkeep, fire-safety compliance, and structural asset preservation. Widespread building-system obsolescence and code updates around energy and life-safety create predictable demand for retrofit programs, condition-based monitoring, and asset-lifecycle planning.
Soft services, although smaller, rise faster at a 4.08% CAGR driven by wellness, security, and concierge expectations. Elevated indoor-air-quality protocols and health-security certifications fuel premium cleaning packages. Office support and front-of-house roles increasingly integrate smart-locker and visitor-management technologies, broadening scope. This divergence positions integrated suppliers to cross-sell soft-service innovations while defending recurring hard-service annuities, thereby enhancing wallet share inside the North America facility management market.
Complete Report Scope:
- By Service Type
- Hard Services
- Asset Management
- MEP and HVAC Services
- Fire Systems and Safety
- Other Hard FM Services
- Soft Services
- Office Support and Security
- Cleaning Services
- Catering Services
- Other Soft FM Services
- Hard Services
- By Offering Type
- In-house
- Outsourced
- Single FM
- Bundled FM
- Integrated FM
- By End-user Industry
- Commercial (IT and Telecom, Retail and Warehouses)
- Hospitality (Hotels, Eateries, Large-scale Restaurants)
- Institutional and Public Infrastructure (Govt, Education, Transportation)
- Healthcare (Public and Private Facilities)
- Industrial and Process (Manufacturing, Energy, Mining)
- Other End-user Industries (Multi-housing, Entertainment, Sports and Leisure)
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- ABM Industries Inc.
- ISS A/S
- Sodexo Inc.
- Aramark
- CBRE Group Inc.
- EMCOR Group Inc.
- GDI Integrated Facility Services
- JLL (Jones Lang LaSalle IP, Inc.)
- Cushman and Wakefield PLC
- Compass Group PLC
- Kellermeyer Bergensons Services, LLC
- Guardian Service Industries Inc.
- SMS Assist, LLC
- AHI Facility Services Inc.
- Emeric Facility Services LLC
- SMI Facility Services
- Shine Facility Services
- Brookfield Global Integrated Solutions
- Honeywell Building Technologies (FM Division)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.1.1 Current Occupancy Rates in North American Commercial Real Estate
- 4.1.2 Profitability Benchmarks of Major FM Providers
- 4.1.3 Workforce Indicators - Skilled and Unskilled Labor Participation
- 4.1.4 Facility Management Market Share (%) by Service Type
- 4.1.5 Facility Management Market Share (%) by Hard Services
- 4.1.6 Facility Management Market Share (%) by Soft Services
- 4.1.7 Urbanization and Population Growth in Top Metro Areas
- 4.1.8 Sector Investment Priorities in United States, Canada, and Mexico Infrastructure Pipeline
- 4.1.9 Regulatory Drivers Specific to Labour and Safety Standards
- 4.2 Market Driver
- 4.2.1 Increasing Infrastructure Development
- 4.2.2 Rising Outsourcing in Building Management
- 4.2.3 Heightened Safety and Security Needs
- 4.2.4 Technological Advancements in Facility Management
- 4.2.5 Sustainability & ESG Compliance Pressures on Building Operations
- 4.2.6 Hybrid-Work Models Driving Demand for Flexible FM Solutions
- 4.3 Market Restraint
- 4.3.1 Security concerns over device and network vulnerabilities
- 4.3.2 High costs of advanced tech and skilled labor
- 4.3.3 Fragmented State-Level Labor Regulations Increasing Compliance Burden
- 4.3.4 Limited Digital Maturity among Small & Mid-Sized FM Providers
- 4.4 Value Chain Analysis
- 4.5 PESTEL Analysis
- 4.6 Regulatory and Legislative Framework for Market Entrants
- 4.7 Impact of Macroeconomic Indicators on FM Demand
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Services
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Investment and Funding Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Service Type
- 5.1.1 Hard Services
- 5.1.1.1 Asset Management
- 5.1.1.2 MEP and HVAC Services
- 5.1.1.3 Fire Systems and Safety
- 5.1.1.4 Other Hard FM Services
- 5.1.2 Soft Services
- 5.1.2.1 Office Support and Security
- 5.1.2.2 Cleaning Services
- 5.1.2.3 Catering Services
- 5.1.2.4 Other Soft FM Services
- 5.1.1 Hard Services
- 5.2 By Offering Type
- 5.2.1 In-house
- 5.2.2 Outsourced
- 5.2.2.1 Single FM
- 5.2.2.2 Bundled FM
- 5.2.2.3 Integrated FM
- 5.3 By End-user Industry
- 5.3.1 Commercial (IT and Telecom, Retail and Warehouses)
- 5.3.2 Hospitality (Hotels, Eateries, Large-scale Restaurants)
- 5.3.3 Institutional and Public Infrastructure (Govt, Education, Transportation)
- 5.3.4 Healthcare (Public and Private Facilities)
- 5.3.5 Industrial and Process (Manufacturing, Energy, Mining)
- 5.3.6 Other End-user Industries (Multi-housing, Entertainment, Sports and Leisure)
- 5.4 By Country
- 5.4.1 United States
- 5.4.2 Canada
- 5.4.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Partnerships
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 ABM Industries Inc.
- 6.4.2 ISS A/S
- 6.4.3 Sodexo Inc.
- 6.4.4 Aramark
- 6.4.5 CBRE Group Inc.
- 6.4.6 EMCOR Group Inc.
- 6.4.7 GDI Integrated Facility Services
- 6.4.8 JLL (Jones Lang LaSalle IP, Inc.)
- 6.4.9 Cushman and Wakefield PLC
- 6.4.10 Compass Group PLC
- 6.4.11 Kellermeyer Bergensons Services, LLC
- 6.4.12 Guardian Service Industries Inc.
- 6.4.13 SMS Assist, LLC
- 6.4.14 AHI Facility Services Inc.
- 6.4.15 Emeric Facility Services LLC
- 6.4.16 SMI Facility Services
- 6.4.17 Shine Facility Services
- 6.4.18 Brookfield Global Integrated Solutions
- 6.4.19 Honeywell Building Technologies (FM Division)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Technology-led Integrated FM (IoT, BMS, AI-based Predictive Maintenance)
- 7.3 ESG-Compliant FM Solutions Demand
- 7.4 Future Service-Model Shifts (Outcome-Based Contracts)