

|
시장보고서
상품코드
2119908
구조화 배선 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Structured Cabling - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
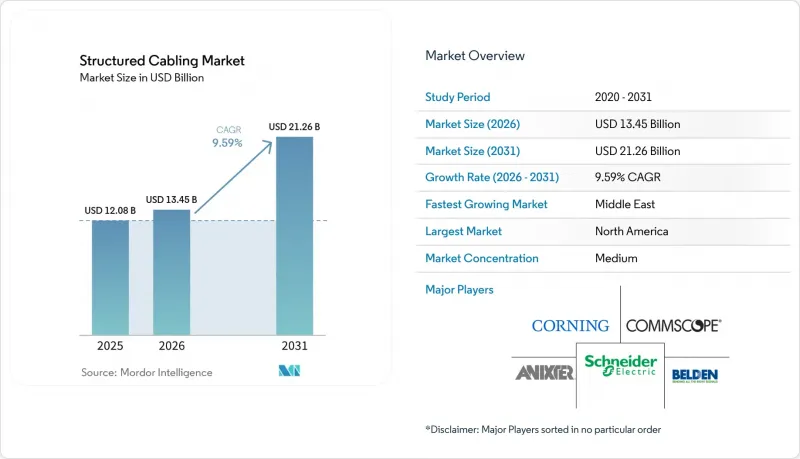
에 의하면, 구조화 배선 시장 규모는 2025년에 120억 8,000만 달러, 2026년에 134억 5,000만 달러, 2031년까지 212억 6,000만 달러에 이를 것으로 예측되며, 2026년부터 2031년까지 CAGR 9.59%로 성장할 전망입니다.
본 보고서는 제공 내용(하드웨어, 서비스, 소프트웨어), 케이블 유형(구리선, 광섬유), 케이블 규격(Cat 5e, Cat 6, Cat 6A, Cat 7/7A, Cat 8), 용도(LAN, 데이터센터,FTTx, 산업 자동화), 최종 사용자(IT 및 통신, 클라우드·코로케이션, 은행, 금융서비스 및 보험(BFSI), 의료, 정부, 제조, 교육), 지역별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 단위로 표시되어 있습니다.
세계 구조화 배선 시장 동향 및 인사이트
하이퍼스케일 및 엣지 데이터센터 구축 가속화
인도의 용량은 2026년 약 1.8 GW에서 2030년까지 최대 4.5GW로 증가할 것으로 예측되며, 뭄바이에서만 설치 부하가 2 GW에 육박할 것으로 전망됩니다. Tier 2 및 Tier 3 도시의 엣지 시설에서는 프로젝트 수가 급증하고 있으며, 짧은 도입 기간 내에 완공하기 위해 사전 종단 처리된 트렁크 케이블이 필요합니다. 80-200 kW의 랙 밀도 및 어그리게이션 계층을 우회하는 AI 트래픽으로 인해, 고밀도 광섬유 본수, 다중 코어 푸시온 커넥터, 그리고 액체 냉각에 대응하는 케이블 트레이에 대한 수요가 증가하고 있습니다. 각 하이퍼스케일러 기업들은 현재 확정적인 지연 시간 예산과 광 손실 마진을 지정하고 있으며, 이를 충족할 수 있는 것은 초저손실 광섬유뿐입니다. 인도의 ‘디지털 개인 데이터 보호법’ 준수 및 ‘국가 데이터센터 정책’ 초안에 따른 인센티브로 인해 인증 시스템의 도입이 가속화되고 있습니다.
PoE 및 원격 전원 공급 요구 사항의 급증
IEEE 802.3bt는 트위스트 페어 케이블을 통해 최대 90W의 전력을 공급하여, 단일 케이블로 액세스 포인트, 카메라, 센서의 데이터 통신과 전원 공급을 동시에 가능하게 합니다. 와트수가 증가하면 도체의 온도가 상승하기 때문에 설치 업체는 TIA 및 ISO/IEC의 열 제한을 충족하기 위해 더 굵은 게이지의 구리선을 사용하거나 배선 길이를 줄여야 합니다. PoE 지원 광 네트워크 장치를 갖춘 패시브 광 LAN은 전력 공급을 중앙 집중화하고, 위험한 산업 구역에서 발생할 수 있는 스파크 위험을 줄여줍니다. ETSI의 산업용 PON 사양 또한 확장된 온도 등급의 채택을 의무화하고 있어 비용은 증가하지만, 도입 시나리오는 확대되고 있습니다. 스마트 빌딩 운영에서는 가동 중지 시간을 줄이고 시설의 에너지 규정을 준수하기 위해 PoE 예산 관리 소프트웨어가 점점 더 중요해지고 있습니다.
엔터프라이즈 WLAN 및 5G 고정 무선 액세스 도입 확대
Wi-Fi 7은 6GHz 대역에서 멀티 기가비트급 속도를 실현하고 있으며, 이에 따라 사무실에서는 각 책상으로의 수평 방향 구리선 연결을 폐지하는 움직임이 진행되고 있습니다. 사설 미드밴드 5G는 셀당 약 15,000 ft²의 범위 내에서 창고와 병원을 커버하여 이동성 제약을 완화하고 있습니다. 통합형 스몰 셀 설계를 통해 프론트홀 지연이 완화되고 기존 LAN 배선을 재사용할 수 있는 한편, PoE 백홀의 밀도가 높아집니다. 이러한 상충 관계로 인해 구리선 케이블 수요는 감소하는 반면, 대용량 광섬유 업링크 및 PoE 예산 관리 소프트웨어에 대한 수요는 증가합니다. 지역별 차이는 뚜렷합니다. 유럽의 역사적인 석조 건물에서는 유선 배선이 유지되는 반면, 미국의 기술 캠퍼스에서는 무선 우선 경향이 나타납니다.
부문 분석
2025년, 구조화 배선 시장의 57.48%를 하드웨어가 차지했으며, 그 원동력은 광섬유 트렁크, 커넥터 및 고밀도 랙이었습니다. 그 뒤를 이어 서비스 부문이 차지했는데, 이는 설치 업체들이 사전 종단 어셈블리를 활용하여 캠퍼스 업그레이드를 가속화하고 있기 때문입니다. 소프트웨어 분야의 구조화 배선 시장 규모는 여전히 작지만, 2031년까지의 연평균 성장률(CAGR)은 10.04%로 다른 모든 제품 분야를 상회하고 있으며, 이는 디지털 문서화 및 PoE 예산 수립 도구에 대한 수요 증가를 반영합니다. 하이퍼스케일러 기업들은 평균 복구 시간(MTTR)을 단축하기 위해 물리 계층의 원격 측정 데이터를 DCIM 제품군에 통합하고 있는 반면, 의료 및 금융 분야의 기업들은 자동화된 규정 준수 보고서를 중시하고 있습니다.
소프트웨어 예측 유지보수 알고리즘은 머신 러닝 모델을 활용하여 미세한 굽힘이나 커넥터의 오염을 경고하여 AI 클러스터의 가동 시간을 확보합니다. 새로운 라이선스 모델에서는 클라우드 대시보드와 커넥터 보증이 세트로 제공되며, 수익은 정기적인 구독 모델로 전환되고 있습니다. 한편, 서비스 수익은 일괄 설치에서 리모델링 컨설팅 및 이동·추가·변경(MAC) 관리 서비스로 중심을 옮기고 있습니다. 대형 통합업체들은 광섬유 간선과 함께 유지보수 계약을 교차 판매하여 고객으로부터의 매출 점유율을 확대되고 있습니다. 하드웨어, 서비스, 소프트웨어의 통합에 실패한 벤더는 구매자들이 ‘싱글 페인 오브 글라스(Single Pane of Glass)’형 플랫폼을 요구하는 가운데, 이익률 압박에 직면할 위험이 있습니다.
광섬유는 2025년에 64.12%의 점유율을 차지하고 연평균 성장률(CAGR) 10.34%로 확대될 전망이며, 구조화 배선 시장의 중추로서의 입지를 공고히 하고 있습니다. 장거리 회선에서는 싱글 모드가 주류를 이루는 반면, 500m 미만의 단거리 링크에서는 멀티 모드가 주류를 이룹니다. 액티브 광케이블과 리니어 옵틱스를 통해 비트당 비용이 절감됨에 따라 지출은 더욱 광섬유 쪽으로 이동하고 있습니다.
구리선은 비용을 중시하는 개보수 공사나, 차폐 트위스트 페어가 전자기 간섭을 줄여주는 열악한 산업 환경에서 여전히 중요한 역할을 하고 있습니다. 30m를 초과하는 카테고리 8 케이블은 일부 랙 상단(Top-of-Rack) 링크에서 광케이블보다 여전히 저렴하여, 광케이블에 의한 완전한 대체를 늦추고 있습니다. 지속가능성 관련 정책에 따라 구리선과 광섬유 모두에서 저연기·무할로겐 피복재의 채택이 진행되고 있어, 재료비가 소폭 상승하고 있습니다. 광·전기 하이브리드 케이블은 단일 피복 내에서 광섬유의 대역폭과 PoE 전력을 제공하며, 스마트 빌딩 개조 공사의 설치 시간을 단축할 수 있어 주목받고 있습니다.
지역별 분석
2025년, 아시아태평양은 구조화 배선 시장의 30.59%를 차지했으며, 인도의 데이터센터 급속한 증설과 중국의 AI 파크가 시장을 견인했습니다. 코치나 비샤카파트남과 같은 인도의 2급 도시에서는 모듈식 엣지 시설이 도입되고 있으며, 여기에는 사전 커넥터가 연결된 트렁크 케이블이 적합합니다. 일본의 산업 자동화 및 한국의 전자 산업 클러스터가 공장용 케이블 수요 증가를 뒷받침하는 한편, 아세안(ASEAN) 지역의 FTTH(Fiber-to-the-Home) 확장이 실외용 케이블 수요를 견인하고 있습니다.
북미는 하이퍼스케일러들이 버지니아주, 오리건주, 텍사스주에 집중되어 있어, 성숙해 가면서도 여전히 활기찬 시장을 유지하고 있습니다. 스마트 빌딩으로의 개조를 통해 기존 사무실에 PoE 지원 링크가 추가되는 한편, 코로케이션 케이지에서는 단거리 연결에 Cat 8이 채택되고 있습니다. 연방 정부의 지속가능성 목표에 따라 정부 소유 건물에서 LSZH(저연기·무할로겐) 케이블의 채택이 촉진되고 있으며, 사양 수립 담당자들은 인증된 공급업체를 선택하고 있습니다.
유럽의 성장은 저연·무할로겐(LSZH) 규제, 에너지 효율 향상을 위한 개보수, 그리고 독일과 프랑스의 인더스트리 4.0 업그레이드에 기인합니다. 역사적 건축물의 존재로 인해 새로운 덕트 경로를 확보하기 어려운 상황인 만큼, 마이크로 케이블과 에어블로우 광섬유가 주목받고 있습니다. 중동은 시장 규모는 작지만, 사우디아라비아의 NEOM과 UAE의 국가 AI 센터가 테라비트급 패브릭과 기가와트급 전력 공급을 필요로 하고 있어 10.56%라는 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다.
라틴아메리카와 아프리카는 수입 의존도가 높고 경제 변동성이 커서 출발이 늦었지만, 브라질의 클라우드 인프라 구축과 나이지리아의 핀테크 붐으로 인해 특정 분야에서 수요가 집중되고 있습니다. 정치적 안정성과 저렴한 전력 가격은 하이퍼스케일러의 입지 선정에 있어 점점 더 중요한 요소가 되고 있으며, 새로운 용량은 기존의 유럽 및 미국 허브에서 아시아와 중동으로 재분배되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.03According to Mordor Intelligence, the structured cabling market size is projected to be USD 12.08 billion in 2025, USD 13.45 billion in 2026, and reach USD 21.26 billion by 2031, growing at a CAGR of 9.59% from 2026 to 2031.
This report is Segmented by Offering (Hardware, Services, and Software), Cable Type (Copper, and Fiber), Cable Category Standard (Cat 5e, Cat 6, Cat 6A, Cat 7/7A, and Cat 8), Application (LAN, Data Center, Fttx, and Industrial Automation), End-User (IT and Telecom, Cloud and Colocation, BFSI, Healthcare, Government, Manufacturing, and Education), and Geography. Market Forecasts are in Value (USD).
Global Structured Cabling Market Trends and Insights
Accelerating Hyperscale and Edge Data Center Build-Outs
India's capacity is forecast to climb from roughly 1.8 GW in 2026 to up to 4.5 GW by 2030, with Mumbai alone approaching 2 GW of installed load. Edge facilities in Tier 2 and Tier 3 cities multiply project counts and require pre-terminated trunks to hit short deployment windows. Rack densities of 80-200 kW and AI traffic that bypass aggregation layers drive dense fiber counts, multi-fiber push-on connectors, and liquid-cooling-friendly cable trays. Hyperscalers now specify deterministic latency budgets and optical-loss margins that only ultra-low-loss fiber can meet. Compliance with India's Digital Personal Data Protection Act and incentives under the draft National Data Center Policy accelerate certified-system adoption.
Surge in PoE and Remote Powering Requirements
IEEE 802.3bt delivers up to 90 W over twisted pair, enabling a single cable to support data and power for access points, cameras, and sensors. Higher wattage raises conductor temperature, pushing installers toward larger-gauge copper or shorter run lengths to meet TIA and ISO/IEC thermal limits. Passive optical LAN with PoE-capable optical network units centralizes power and mitigates spark risk in hazardous industrial zones. ETSI's industrial PON spec also mandates extended temperature classes, adding cost but widening deployment scenarios. Smart-building plays increasingly treat PoE budgeting software as critical to reduce downtime and comply with facility energy codes.
Rising Adoption of Enterprise WLAN and 5G Fixed Wireless Access
Wi-Fi 7 delivers multi-gigabit speeds in the 6 GHz band, prompting offices to drop horizontal copper links at every desk. Private mid-band 5G covers warehouses and hospitals with roughly 15,000 ft2 per cell, easing mobility constraints. Integrated small-cell designs relax fronthaul latency, allowing reuse of existing LAN wiring, yet they increase PoE backhaul density. The trade-off slows copper volumes but lifts demand for high-capacity fiber uplinks and PoE budgeting software. Regional variance is strong: Europe's historic stone buildings retain wired runs, while U.S. tech campuses lean wireless-first.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Retrofits for Smart Buildings and Campuses
- Adoption of 400 G / 800 G Active Optical Cables in AI Clusters
- Supply-Chain Volatility in Copper and Optical Fiber
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware held 57.48% of structured cabling market share in 2025, driven by fiber trunks, connectors, and high-density racks. Services followed, as installers accelerate campus upgrades using pre-terminated assemblies. The structured cabling market size for software remains small but its 10.04% CAGR through 2031 outpaces all other offerings, reflecting growing demand for digital documentation and PoE budgeting tools. Hyperscalers integrate physical-layer telemetry into DCIM suites to trim mean-time-to-repair, while healthcare and finance entities value automated compliance reports.
Software's predictive-maintenance algorithms leverage machine-learning models to warn of micro-bends and connector contamination, protecting uptime in AI clusters. New license models bundle cloud dashboards with connector warranties, shifting revenue toward recurring subscriptions. Meanwhile, services revenue pivots from bulk installation toward retrofit consulting and moves-adds-changes managed services. Larger integrators cross-sell maintenance contracts alongside fiber trunks, deepening wallet share. Vendors that fail to unify hardware, services, and software risk margin squeeze as buyers seek single-pane-of-glass platforms.
Fiber captured 64.12% share in 2025 and is poised to expand at a 10.34% CAGR, reinforcing its status as backbone of the structured cabling market. Single-mode dominates long runs, while multi-mode holds short-reach links below 500 m. Active optical cables and linear optics compress cost per bit, further tilting spend toward fiber.
Copper retains relevance in cost-sensitive retrofits and in harsh industrial environments where shielded twisted-pair mitigates electromagnetic interference. Category 8 over 30 m remains cheaper than optics for some top-of-rack links, delaying full fiber displacement. Sustainability policies push both copper and fiber to adopt low-smoke zero-halogen jackets, marginally inflating material costs. Hybrid optical-electrical cables gain mindshare because they deliver fiber bandwidth plus PoE power in a single sheath, cutting pull time in smart-building retrofits.
Complete Report Scope:
- By Offering
- Hardware
- Cabling (Copper, Fiber)
- Connectivity (Connectors, Patch-Panels, Jacks, Cords)
- Racks, Cabinets and Cable Management
- Services
- Design and Consulting
- Installation and Integration
- Maintenance and Support
- Software
- Hardware
- By Cable Type
- Copper
- Copper Cable
- Copper Connectivity
- Fiber
- Single-Mode Cable
- Multi-Mode Cable
- Fiber Connectivity
- Copper
- By Cable Category Standard
- Cat 5e
- Cat 6
- Cat 6A
- Cat 7/7A
- Cat 8
- By Application
- LAN
- Data Center
- FTTx, Campus Backbone
- Industrial Automation Networks
- By End-User Industry
- IT and Telecom Service Providers
- Cloud and Colocation Data Centers
- BFSI and Enterprise Offices
- Healthcare Facilities
- Government and Defense
- Manufacturing and Industrial
- Education
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Nordics
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia
- New Zealand
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia Pacific accounted for 30.59% of structured cabling market share in 2025, energized by India's rapid data-center additions and China's AI parks. Tier-2 Indian cities such as Kochi and Visakhapatnam invite modular edge facilities that favor pre-connectorized trunks. Japanese industrial automation and South Korean electronics clusters sustain factory cabling uptick, while ASEAN fiber-to-the-home rollouts drive outdoor cable demand.
North America remains a mature yet dynamic pocket as hyperscalers cluster in Virginia, Oregon, and Texas. Smart-building retrofits add PoE-rich links in legacy offices, whereas colocation cages adopt Cat 8 for short reach. Federal sustainability targets encourage LSZH adoption in government properties, pushing specifiers toward certified suppliers.
Europe's growth stems from low-smoke zero-halogen mandates, energy-efficiency retrofits, and Industry 4.0 upgrades in Germany and France. Historic structures complicate new duct routes, making micro-cables and air-blown fiber attractive. The Middle East, though smaller in base, posts the highest 10.56% CAGR as Saudi Arabia's NEOM and UAE sovereign AI centers demand terabit fabrics and gigawatt power envelopes.
Latin America and Africa lag because of import dependency and economic volatility, yet Brazil's cloud build-outs and Nigeria's fintech boom create focused demand pockets. Political stability and low electricity pricing increasingly dictate hyperscaler site selection, redistributing new capacity away from legacy Western hubs toward Asia and the Middle East.
- CommScope Holding Company Inc.
- Corning Incorporated
- Belden Inc.
- Legrand SA
- Nexans SA
- Panduit Corp.
- Prysmian Group
- Schneider Electric SE
- The Siemon Company
- TE Connectivity Ltd.
- Furukawa Electric Co. Ltd.
- Hubbell Incorporated
- Rosenberger Hochfrequenztechnik GmbH & Co. KG
- Datwyler Cabling Solutions AG
- LS Cable & System Ltd.
- Reichle & De-Massari AG (R&M)
- Superior Essex Inc.
- Anixter International Inc. (WESCO International)
- AFL (AFL Global)
- Black Box Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Hyperscale and Edge Data Center Build-Outs
- 4.2.2 Surge in PoE and Remote Powering Requirements
- 4.2.3 Increasing Retrofits for Smart Buildings and Campuses
- 4.2.4 Adoption of 400G/800G Active Optical Cables in AI Clusters
- 4.2.5 Sustainability Mandates Driving Low-Smoke Zero-Halogen Cabling
- 4.2.6 Converged OT/IT Cabling for Industry 4.0 Time-Sensitive Networking
- 4.3 Market Restraints
- 4.3.1 Rising Adoption of Enterprise WLAN and 5G Fixed Wireless Access
- 4.3.2 Supply-Chain Volatility in Copper and Optical Fiber
- 4.3.3 Emerging Silicon Photonics Eliminating High-Speed Copper Runs
- 4.3.4 Increasing Use of Modular Plug-Terminated Links Reducing Patch-Panel Demand
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Key Use Cases and Case Studies
- 4.10 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Offering
- 5.1.1 Hardware
- 5.1.1.1 Cabling (Copper, Fiber)
- 5.1.1.2 Connectivity (Connectors, Patch-Panels, Jacks, Cords)
- 5.1.1.3 Racks, Cabinets and Cable Management
- 5.1.2 Services
- 5.1.2.1 Design and Consulting
- 5.1.2.2 Installation and Integration
- 5.1.2.3 Maintenance and Support
- 5.1.3 Software
- 5.1.1 Hardware
- 5.2 By Cable Type
- 5.2.1 Copper
- 5.2.1.1 Copper Cable
- 5.2.1.2 Copper Connectivity
- 5.2.2 Fiber
- 5.2.2.1 Single-Mode Cable
- 5.2.2.2 Multi-Mode Cable
- 5.2.2.3 Fiber Connectivity
- 5.2.1 Copper
- 5.3 By Cable Category Standard
- 5.3.1 Cat 5e
- 5.3.2 Cat 6
- 5.3.3 Cat 6A
- 5.3.4 Cat 7/7A
- 5.3.5 Cat 8
- 5.4 By Application
- 5.4.1 LAN
- 5.4.2 Data Center
- 5.4.3 FTTx, Campus Backbone
- 5.4.4 Industrial Automation Networks
- 5.5 By End-User Industry
- 5.5.1 IT and Telecom Service Providers
- 5.5.2 Cloud and Colocation Data Centers
- 5.5.3 BFSI and Enterprise Offices
- 5.5.4 Healthcare Facilities
- 5.5.5 Government and Defense
- 5.5.6 Manufacturing and Industrial
- 5.5.7 Education
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Nordics
- 5.6.3.7 Russia
- 5.6.3.8 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 ASEAN
- 5.6.4.6 Australia
- 5.6.4.7 New Zealand
- 5.6.4.8 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Egypt
- 5.6.5.2.3 Nigeria
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 CommScope Holding Company Inc.
- 6.4.2 Corning Incorporated
- 6.4.3 Belden Inc.
- 6.4.4 Legrand SA
- 6.4.5 Nexans SA
- 6.4.6 Panduit Corp.
- 6.4.7 Prysmian Group
- 6.4.8 Schneider Electric SE
- 6.4.9 The Siemon Company
- 6.4.10 TE Connectivity Ltd.
- 6.4.11 Furukawa Electric Co. Ltd.
- 6.4.12 Hubbell Incorporated
- 6.4.13 Rosenberger Hochfrequenztechnik GmbH & Co. KG
- 6.4.14 Datwyler Cabling Solutions AG
- 6.4.15 LS Cable & System Ltd.
- 6.4.16 Reichle & De-Massari AG (R&M)
- 6.4.17 Superior Essex Inc.
- 6.4.18 Anixter International Inc. (WESCO International)
- 6.4.19 AFL (AFL Global)
- 6.4.20 Black Box Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


