|
시장보고서
상품코드
2120516
유럽의 의약품 포장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Pharmaceutical Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
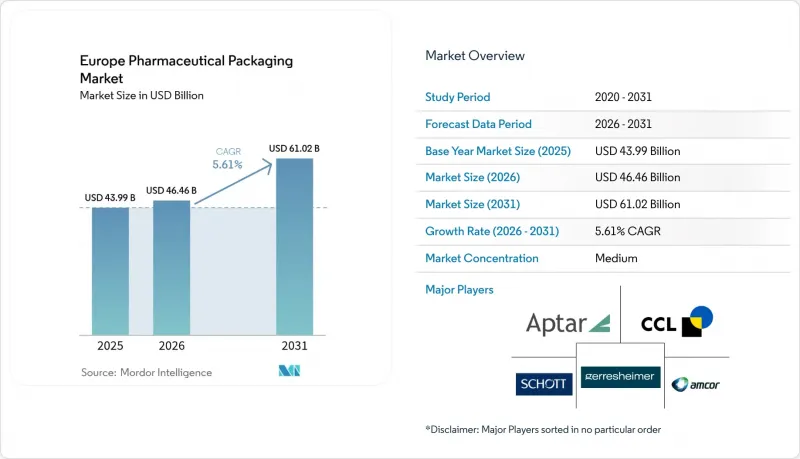
에 의하면, 유럽의 의약품 포장 시장 규모는 2025년에 439억 9,000만 달러로 평가되었습니다. 2026년 464억 6,000만 달러에서 2031년까지 610억 2,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 5.61%를 나타낼 전망입니다.
본 보고서는 소재 유형(플라스틱, 유리, 금속/박 등), 포장 유형(1차 포장, 2차 포장, 3차 포장), 기술(기존, 무균·멸균 등), 최종 사용자(제약 제조업체, 전문·생명공학 기업, 병원 및 진료소 등), 그리고 국가별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽의 의약품 포장 시장 동향 및 인사이트
바이오의약품 및 주사제 요법의 성장
2024년 유럽의약품청(EMA)이 승인한 신규 분자 실체(NME) 중 바이오의약품이 30% 이상을 차지했으며, 추출물이 적고 치수 공차가 엄격한 비경구 투여용 용기에 대한 수요가 증가하고 있습니다. SCHOTT Pharma는 2024 회계연도 매출로 20억 9,500만 유로(23억 달러)를 보고했으며, 그중 78%는 Type I 붕규산 바이알 및 고리형 올레핀 폴리머 카트리지와 같은 의약품 용기 솔루션에서 비롯된 것이었습니다. 웨스트 파마슈티컬 서비스(West Pharmaceutical Services)는 2024년 9월까지의 9개월 동안 NovaPure 스토퍼 및 다이쿄 크리스탈 제니스(Daikyo Crystal Zenith) 제조 주사기 등 독자적인 부품으로 19억 8,000만 달러의 매출을 기록했습니다. 스테바나트 그룹은 EZ-fill 바이알 및 Nexa 자동 주사기 플랫폼의 호조에 힘입어 2024년 상반기 매출을 전년 동기 대비 11.6% 증가시켰습니다. 2024년 9월 게레스하이머, 스테바나트, SCHOTT Pharma 3사 간에 체결된 제휴를 통해, 충전 준비 완료 제품의 사양이 통일될 전망이며, 특히 수탁 제조의 성장이 가장 두드러진 폴란드와 이탈리아에서 바이오시밀러의 적격성 평가 기간이 단축될 가능성이 있습니다.
EU의 엄격한 일련번호 규제가
‘위조 의약품 지침’에 따라 유럽연합(EU) 내에서 유통되는 모든 처방약 포장에 고유 식별자와 위조 방지 장치의 부착이 의무화되어 있으며, 이에 따라 2026년까지 일련번호 라벨, 2차원 바코드,NFC 탑재 카톤을 위한 12억 유로 규모의 애프터마켓이 창출될 전망입니다. 슈라이너 메디팜(Schlainer Medifarm)은 진위 확인 및 환자 참여 사례에 대응하기 위해 NFC 라벨 제품 라인업을 확충했습니다. CCL 인더스트리즈는 2024년 1-9개월 동안 51억 캐나다 달러(37억 5,000만 달러)의 매출을 기록했습니다. 의료 및 특수 라벨 분야는 통합 및 업그레이드의 혜택을 받고 있습니다. 영국은 브렉시트 이후에도 EU의 일련번호 규정을 반영하고 있으며, 라벨 가공업체들에게 범유럽 공급망에 대응하는 상호 운용 가능한 솔루션을 제공할 것을 의무화하고 있습니다.
의약품 등급 원자재 가격 변동
2024년, 유럽의 에너지 비용이 급등함에 따라 붕규산 유리 튜브 및 환상 올레핀 공중합체 수지의 가격이 18-22% 상승했습니다. 연속식 유리 용광로는 1,500°C의 운전 온도가 필요하기 때문에 생산자들은 지정학적 충격의 영향을 받기 쉬운 천연가스에 의존할 수밖에 없습니다. 웨스트 파마슈티컬 서비스는 현재 다이쿄 크리스탈 제니스의 부품을 현물 가격 변동으로부터 보호하기 위해, 다년간의 수지 공급 계약을 체결하여 공급을 확보하고 있습니다. 원자재 비용의 급등으로 인해 고리형 올레핀 폴리머 및 폴리에틸렌 테레프탈레이트 글리콜을 이용한 대체 소재 연구가 가속화되고 있지만, 이러한 대체 소재의 경우 EMA의 승인을 받기 전에 광범위한 안정성 데이터를 수집해야 합니다.
부문별 분석
2025년, 유럽의 의약품 포장 시장에서 플라스틱은 52.03%의 점유율을 차지하며 주도적인 위치를 차지했고, 폴리에틸렌 테레프탈레이트(PET) 병과 폴리프로필렌 블리스터 필름이 이를 주도했습니다. 유리는 유형 I 붕규산 바이알 및 카트리지 덕분에 금액 기준으로 여전히 2위를 유지하고 있으며, 이 부문은 2023년부터 2027년에 걸쳐 게레스하이머,쇼트 파마, SGD 파마가 진행하는 15억 유로(16억 5,000만 달러) 규모의 용광로 설비 투자를 통해 강화되고 있습니다. 바이오폴리머 및 복합 소재는 차단성을 저해하지 않으면서 PPWR의 재활용 함량 요건을 충족하려는 브랜드 소유주들에 힘입어 연평균 성장률(CAGR) 6.86%를 나타낼 것으로 예측됩니다. 암콜(Amcor)과 노라트(Norat)는 ISO 15378 공정 검증 기준을 충족하면서, 비접촉층에 사용 가능한 폴리젖산 및 폴리하이드록시알카노에이트 수지의 인증을 추진하고 있습니다.
규제상의 장벽으로 인해 1차 용기에 바이오 폴리머의 채택은 지연되고 있지만, 대규모 컨버터는 검증 비용을 상각할 수 있기 때문에 공급업체 시장에는 양극화가 발생하고 있습니다. 2028년 이후 PPWR의 시행이 엄격해짐에 따라 경구용 고형 제형용 플라스틱의 성장은 둔화되는 반면, 유리 및 고리형 올레핀 폴리머는 고부가가치 바이오의약품 분야에서 프리미엄 위치를 계속 유지할 것입니다.
1차 포장 형태는 2025년에 유럽의 의약품 포장 시장 규모의 62.10%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 6.58%로 확대될 것으로 전망됩니다. 정제용 병은 여전히 가장 큰 하위 부문이지만, 주사제 및 흡입제의 점유율이 확대됨에 따라 그 성장세는 둔화되고 있습니다. 프리필 주사기 및 카트리지는 West Pharmaceutical Services사의 19억 8,000만 달러에 달하는 독자적인 부품 매출의 기반을 이루고 있으며, 약물 전달 시스템에 내재된 이익률의 레버리지를 부각시키고 있습니다. 바이알 및 앰플의 경우, 헝가리와 세르비아에 새로운 생산 능력이 도입되었음에도 불구하고 간헐적인 공급 제약에 직면해 있습니다.
지출의 30-35%를 차지하는 2차 포장은 시리얼화 및 NFC 도입에 따라 성장하고 있으며, CCL 인더스트리즈의 헬스케어용 라벨 매출 증가가 이를 입증하고 있습니다. 3차 포장인 골판지 포장은 만성 질환 치료제의 전자상거래 유통에 힘입어 나머지 부분을 차지하고 있습니다. 이러한 근본적인 변화로 인해, 규제상의 진입 장벽과 기술적 복잡성이 여전히 가장 높은 1차 포장에 가치 창출이 집중되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the Europe pharmaceutical packaging market size was valued at USD 43.99 billion in 2025 and estimated to grow from USD 46.46 billion in 2026 to reach USD 61.02 billion by 2031, at a CAGR of 5.61% during the forecast period (2026-2031).
This report is Segmented by Material Type (Plastic, Glass, Metal/Foil, and More), Packaging Type (Primary Packaging, Secondary Packaging, Tertiary Packaging), Technology (Conventional, Aseptic and Sterile, and More), End User (Pharmaceutical Manufacturers, Specialty/Biotech Firms, Hospitals and Clinics, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe Pharmaceutical Packaging Market Trends and Insights
Growth of Biologics and Injectable Therapies
Biologics accounted for more than 30% of new molecular entities approved by the European Medicines Agency in 2024, elevating demand for parenteral containers with low extractables and tight dimensional tolerances. SCHOTT Pharma reported EUR 2.095 billion (USD 2.30 billion) in fiscal 2024 revenue, 78% of which came from drug containment solutions, including Type I borosilicate vials and cyclic olefin polymer cartridges. West Pharmaceutical Services derived USD 1.98 billion from proprietary components, including NovaPure stoppers and Daikyo Crystal Zenith syringes in the nine months to September 2024. Stevanato Group grew its first-half 2024 revenue 11.6% year over year, driven by EZ-fill vials and the Nexa autoinjector platform. A September 2024 alliance among Gerresheimer, Stevanato, and SCHOTT Pharma is expected to harmonize ready-to-fill specifications, potentially reducing qualification timelines for biosimilars, particularly in Poland and Italy, where contract manufacturing growth is strongest.
Stringent EU Serialization Mandates
The Falsified Medicines Directive requires every prescription pack distributed in the European Union to carry a unique identifier and a tamper-evident device, generating a EUR 1.2 billion aftermarket for serialized labels, 2D barcodes, and NFC-equipped cartons through 2026. Schreiner MediPharm has expanded its NFC label portfolio to support authentication and patient engagement use cases. CCL Industries reported CAD 5.1 billion (USD 3.75 billion) revenue for the first nine months of 2024, with healthcare and specialty labels benefiting from aggregation upgrades. The United Kingdom has mirrored EU serialization rules post-Brexit, compelling label converters to deliver interoperable solutions for pan-European supply chains.
Volatility in Pharmaceutical-Grade Raw Material Prices
Borosilicate glass tubing and cyclic olefin copolymer resins climbed 18-22% in 2024 as European energy costs surged. Continuous glass furnaces require an operating temperature of 1,500 °C, anchoring producers to natural-gas inputs that remain vulnerable to geopolitical shocks. West Pharmaceutical Services now secures its supply with multi-year resin contracts to protect Daikyo Crystal Zenith components from spot-price fluctuations. Elevated input costs have accelerated material-substitution studies involving cyclic olefin polymer and polyethylene terephthalate glycol; however, these alternatives require extensive stability data before EMA approval.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of NFC-Enabled Smart Labels for Anti-Counterfeiting
- Expansion of Temperature-Controlled Mail-Order Pharmacies
- Capacity Bottlenecks for Pharma-Grade Molded Glass Vials
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics dominated the Europe pharmaceutical packaging market with a 52.03% share in 2025, led by polyethylene terephthalate bottles and polypropylene blister films. Glass remained second in value, owing to Type I borosilicate vials and cartridges, a segment fortified by EUR 1.5 billion (USD 1.65 billion) in furnace investments from Gerresheimer, Schott Pharma, and SGD Pharma between 2023 and 2027. Biopolymers and composite materials are projected to grow at a 6.86% CAGR, driven by brand owners seeking to meet PPWR recycled-content requirements without compromising barrier properties. Amcor and Nolato are qualifying polylactic and polyhydroxyalkanoate resins for non-contact layers that still meet the ISO 15378 process validation thresholds.
Regulatory hurdles slow the uptake of biopolymers in primary containers, yet converters with scale can amortize validation costs, creating a two-tier supplier landscape. As PPWR enforcement tightens after 2028, growth in plastics for oral-solid dosage formats will moderate, while Glass and cyclic olefin polymers will retain their premium status in high-value biologics.
Primary formats are expected to account for 62.10% of the Europe pharmaceutical packaging market size in 2025 and are projected to rise at a 6.58% CAGR through 2031. Bottles for tablets remain the largest sub-segment, but their growth lags as injectables and inhalables gain share. Pre-fillable syringes and cartridges underpin West Pharmaceutical Services' USD 1.98 billion proprietary-components revenue, highlighting the margin leverage embedded in drug-delivery systems. Vials and ampules face intermittent supply constraints despite the introduction of new capacity in Hungary and Serbia.
Secondary packaging, which accounts for 30-35% of spending, grows in tandem with serialization and NFC adoption, as evidenced by CCL Industries' healthcare-label revenue uptick. Tertiary corrugated packs hold the balance, aided by e-commerce distribution for chronic-disease therapies. The underlying shift concentrates value creation in primary packs where regulatory moats and technical complexity remain highest.
Complete Report Scope:
- By Material Type
- Plastic
- Glass
- Paper and Paperboard
- Metal/Foil
- Biopolymers and Composite Materials
- By Packaging Type
- Primary Packaging
- Bottles
- Blister Packs
- Pre-fillable Syringes
- Vials and Ampoules
- IV Containers
- Inhalers
- Other Primary Packagings
- Secondary Packaging
- Folding Cartons
- Labels and Inserts
- Bags and Pouches
- Trays
- Other Secondary Packagings
- Tertiary Packaging
- Corrugated Shippers
- Pallets
- Other Tertiary Packagings
- Primary Packaging
- By Technology
- Conventional
- Aseptic and Sterile
- Smart and Connected (NFC/RFID)
- Anti-counterfeit / Serialisation
- Sustainable / Recyclable Solutions
- Child-Resistant and Tamper-Evident Solutions
- By End User
- Pharmaceutical Manufacturers
- Specialty/Biotech Firms
- Contract Manufacturing and Packaging Organizations
- Hospitals and Clinics
- By Country
- United Kingdom
- Germany
- France
- Spain
- Italy
- Poland
- Rest of Europe
List of Companies Covered in this Report:
- Amcor Plc
- Gerresheimer AG
- Schott AG
- AptarGroup Inc.
- CCL Industries Inc.
- Stevanato Group S.p.A.
- West Pharmaceutical Services Inc.
- SGD Pharma SAS
- Nolato AB
- Ardagh Group S.A.
- Bormioli Pharma S.p.A.
- Nipro Corporation
- Origin Pharma Packaging Ltd.
- Gaplast GmbH
- DWK Life Sciences GmbH
- IntraPac International LLC
- Vetter Pharma-Fertigung GmbH and Co. KG
- Romaco Group GmbH
- APG Europe B.V.
- Piramal Pharma Solutions
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth of Biologics and Injectable Therapies
- 4.2.2 Stringent EU Serialization Mandates
- 4.2.3 Rising Demand for Patient-Friendly Drug Delivery Formats
- 4.2.4 Adoption of NFC-Enabled Smart Labels for Anti-Counterfeiting
- 4.2.5 Expansion of Temperature-Controlled Mail-Order Pharmacies
- 4.2.6 Recycled Medical-Grade Plastics Mandate Under EU PPWR
- 4.3 Market Restraints
- 4.3.1 Volatility in Pharmaceutical-Grade Raw Material Prices
- 4.3.2 Increasing Sustainability Compliance Costs
- 4.3.3 Capacity Bottlenecks for Pharma-Grade Molded Glass Vials
- 4.3.4 Extended CE-Mark Review Timelines for Combination Products
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Packaging Demand Analysis by Dosage Form (Qualitative Assessment)
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Plastic
- 5.1.2 Glass
- 5.1.3 Paper and Paperboard
- 5.1.4 Metal/Foil
- 5.1.5 Biopolymers and Composite Materials
- 5.2 By Packaging Type
- 5.2.1 Primary Packaging
- 5.2.1.1 Bottles
- 5.2.1.2 Blister Packs
- 5.2.1.3 Pre-fillable Syringes
- 5.2.1.4 Vials and Ampoules
- 5.2.1.5 IV Containers
- 5.2.1.6 Inhalers
- 5.2.1.7 Other Primary Packagings
- 5.2.2 Secondary Packaging
- 5.2.2.1 Folding Cartons
- 5.2.2.2 Labels and Inserts
- 5.2.2.3 Bags and Pouches
- 5.2.2.4 Trays
- 5.2.2.5 Other Secondary Packagings
- 5.2.3 Tertiary Packaging
- 5.2.3.1 Corrugated Shippers
- 5.2.3.2 Pallets
- 5.2.3.3 Other Tertiary Packagings
- 5.2.1 Primary Packaging
- 5.3 By Technology
- 5.3.1 Conventional
- 5.3.2 Aseptic and Sterile
- 5.3.3 Smart and Connected (NFC/RFID)
- 5.3.4 Anti-counterfeit / Serialisation
- 5.3.5 Sustainable / Recyclable Solutions
- 5.3.6 Child-Resistant and Tamper-Evident Solutions
- 5.4 By End User
- 5.4.1 Pharmaceutical Manufacturers
- 5.4.2 Specialty/Biotech Firms
- 5.4.3 Contract Manufacturing and Packaging Organizations
- 5.4.4 Hospitals and Clinics
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Spain
- 5.5.5 Italy
- 5.5.6 Poland
- 5.5.7 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor Plc
- 6.4.2 Gerresheimer AG
- 6.4.3 Schott AG
- 6.4.4 AptarGroup Inc.
- 6.4.5 CCL Industries Inc.
- 6.4.6 Stevanato Group S.p.A.
- 6.4.7 West Pharmaceutical Services Inc.
- 6.4.8 SGD Pharma SAS
- 6.4.9 Nolato AB
- 6.4.10 Ardagh Group S.A.
- 6.4.11 Bormioli Pharma S.p.A.
- 6.4.12 Nipro Corporation
- 6.4.13 Origin Pharma Packaging Ltd.
- 6.4.14 Gaplast GmbH
- 6.4.15 DWK Life Sciences GmbH
- 6.4.16 IntraPac International LLC
- 6.4.17 Vetter Pharma-Fertigung GmbH and Co. KG
- 6.4.18 Romaco Group GmbH
- 6.4.19 APG Europe B.V.
- 6.4.20 Piramal Pharma Solutions
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment