

|
시장보고서
상품코드
2120544
인도의 농약 산업 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)India Agrochemicals Industry - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
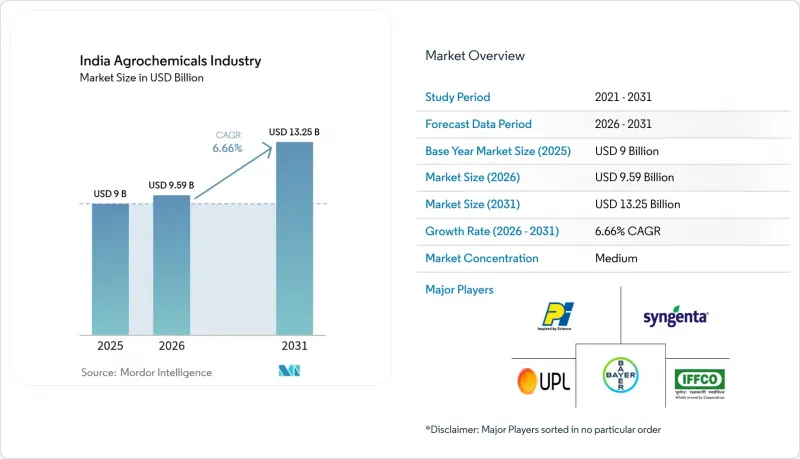
에 의하면, 2026년 인도의 농약 산업 시장 규모는 95억 9,000만 달러로 추정되고 2025년 90억 달러에서 확대해, 2031년에는 132억 5,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 동안의 연평균 성장률(CAGR)은 6.66%가 될 것으로 전망됩니다.
본 보고서는 제품 유형별(비료, 농약, 보조제, 식물 생장 조절제) 및 용도별(곡류 및 곡물, 콩류·유지종자, 과일 및 채소, 상업용 작물)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
인도의 농약 산업의 동향 및 인사이트
정부의 보조금 제도 재검토에 따른 바이오 자재 도입 촉진
새로운 보조금 체계에서는 비료의 무분별한 소비를 억제한 주에 대해 포상금을 지급하는 한편, 퇴비, 바이오 비료, 나노 영양소 액제에 대한 예산 지원을 촉진하고 있습니다. 2025년도 연방 예산에는 농업 예산이 편성되었으며, ‘총리 댄-다냐 크리시 요자나(Prime Minister Dhan-Dhanya Krishi Yojana)’가 시작되었습니다. 이를 통해 인증된 바이오 제품으로 전환한 농업 종사자에게 보상을 제공하는 공식적인 체계가 구축되었습니다. 또한, ‘PM-PRANAM’ 등의 병행 프로그램에서는 화학 비료 감축 목표 달성도에 따라 지원금이 지급되는 체계로 운영되며, 행정 당국이 연수 프로그램 및 현장 시연을 신속하게 실시하도록 독려하고 있습니다.
디지털화된 농업 금융·전자상거래 네트워크를 통한 라스트 마일 도달 범위 확대
정부 자금을 통한 디지털 인프라 구축으로 토지 대장, 토양 건강 카드, 키산 신용카드의 신용 한도가 통합된 농업 종사자 등록부가 마련되었습니다. 이를 통해 농업 자재 기업들은 단 몇 분 만에 신용 프로파일을 확인하고, 앱 기반 플랫폼을 통해 주문을 발주할 수 있게 되었습니다. 예를 들어, 2024년에는 인도 농업 종사자 비료 협동조합(IFFCO)의 ‘e-Bazar’가 전 회계 연도에 20만 건 이상의 온라인 거래를 처리하고 2만 7,000개의 우편번호 지역으로 배송을 진행했습니다. 이는 대량 농자재 유통에서 과거에는 상상조차 할 수 없었던 규모입니다. 인도의 농약 산업 시장에서 이러한 디지털 기반은 특히 제품 구색의 폭이 오랫동안 제약 요인이었던 2급 지역에서 고품질 제제 수요 증가로 이어지고 있습니다.
중국에 대한 원료 의존으로 인한 비용 변동 심화
인도의 공장은 비스무트, 텔루르, 흑연 등 산업용 중간체의 대부분을 중국 공급업체로부터 수입하고 있어, 지정학적 긴장이 고조될 경우 현지 제제 제조업체가 가격 변동이나 출하 지연의 영향을 받기 쉽습니다. 국내 생산자들은 더 많은 안전 재고를 확보할 수밖에 없으며, 전 세계 운임이 급등할 경우 운전 자금이 묶여 이익률이 압박을 받게 됩니다. 정부 태스크포스는 인도가 100% 수입에 의존하고 있는 10가지 유형의 중요 광물을 특정하고, 대체 공급원 확보를 가속화하기 위한 우대 조치 패키지를 마련 중입니다.
부문별 분석
비료는 인도의 농약 산업 시장 규모의 54.60%를 차지하며, 쌀, 밀, 사탕수수 생산 시스템에서 식량 안보 정책의 기반으로 계속 자리 잡고 있습니다. 인산이암모늄과 요소가 물량의 대부분을 차지하고 있지만, 보조금 개혁의 진전에 따라 농업 종사자들은 지하수 오염을 최소화하는 미량 영양소 혼합물이나 나노 액체 비료로 전환해야 하는 상황에 직면해 있습니다.
농약은 초기 규모는 작지만, 퇴비 사용에 대한 인센티브, 잔류물 관련 수출 기준, 유기농 인증 면적 확대에 힘입어 2031년까지 연평균 성장률(CAGR) 10.12%로 거의 비슷한 수준의 매출 증가가 예상됩니다. 미생물 컨소시엄 및 해조류 유래 생장 촉진제의 인기가 높아짐에 따라, 기존 주요 비료 제조업체들도 바이오 사업 부문을 출범시키는 움직임을 보이고 있습니다. 유통 기한 연장, 콜드체인에 의존하지 않는 포장, 농업 종사자에 대한 계몽 활동을 확립한 제조업체는 선구자로서 고객 충성도를 확보할 수 있을 것으로 전망됩니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, India agrochemicals market size in 2026 is estimated at USD 9.59 billion, growing from 2025 value of USD 9 billion with 2031 projections showing USD 13.25 billion, growing at 6.66% CAGR over 2026-2031.
This report is Segmented by Product Type (Fertilizers, Pesticides, Adjuvants, Plant Growth Regulators), Application (Cereals and Grains, Pulses and Oilseeds, Fruits and Vegetables, Commercial Crops). The Market Forecasts are Provided in Terms of Value (USD).
India Agrochemicals Industry Trends and Insights
Government Subsidy Rationalization Spurring Bio-inputs Adoption
New subsidy frameworks reward states for curbing blanket fertilizer consumption and channel budgetary support toward compost, biofertilizers, and nano-nutrient liquids. The 2025 Union Budget set aside for agriculture and launched the Prime Minister Dhan-Dhanya Krishi Yojana, creating a formal mechanism to reimburse farmers who switch to certified biologicals . Parallel programs such as PM-PRANAM link disbursements to chemical reduction targets, encouraging administrators to fast-track training modules and field demonstrations.
Digitized Agri-credit and E-commerce Networks Widening Last-mile Reach
Government-funded digital infrastructure now integrates land records, soil health cards, and Kisan Credit Card limits into a unified farmer registry, allowing input companies to vet credit profiles in minutes and dispatch orders through app-based platforms. In 2024, Indian Farmers Fertiliser Cooperative Limited (IFFCO) e-Bazar, for instance, fulfilled more than 200,000 online transactions in the past fiscal year and delivered to 27,000 pin codes, a scale previously unimaginable for bulk inputs. For the India agrochemicals market, these digital rails translate into higher off-take of premium formulations, especially in tier-II districts where assortment depth had long been a constraint.
Disruptive Raw-material Dependence on China Raising Cost Volatility
Indian plants import a bulk of technical intermediates such as bismuth, tellurium, and graphite from Chinese suppliers, leaving local formulators exposed to price swings and shipping delays during geopolitical flashpoints. Domestic producers must carry higher safety stocks, locking working capital and eroding margins when global freight rates spike. Government task forces have identified 10 critical minerals where India is 100% import-dependent and are drafting incentive packages to fast-track alternative sources.
Other drivers and restraints analyzed in the detailed report include:
- Drone-based Precision Spraying Unlocking Smallholder Demand
- Off-patent Molecule Wave Expanding Export Pipeline
- Accelerating State-level Bans on High-toxicity Actives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fertilizers captured 54.60% of the India agrochemicals market size, and continue to anchor food security policies for rice, wheat, and sugarcane systems. Di-ammonium phosphate and urea dominate volumes, yet escalating subsidy reforms are nudging growers toward micronutrient blends and nano-liquids that minimize groundwater contamination.
Pesticides, though starting from a smaller base, are projected to add nearly incremental sales by 2031 at a 10.12% CAGR, underpinned by compost incentives, residue-linked export standards, and expanding organic certification acreage. The rising popularity of microbial consortia and seaweed-based stimulants is encouraging conventional fertilizer majors to launch dedicated bio-divisions. Producers that master shelf-life extension, cold-chain independent packaging, and farmer education stand to capture early mover loyalty.
Complete Report Scope:
- By Product Type
- Fertilizers
- Nitrogenous
- Phosphatic
- Potassic
- Other Fertilizers
- Pesticides
- Herbicides
- Insecticides
- Fungicides
- Other Pesticides
- Adjuvants
- Plant Growth Regulators
- Fertilizers
- By Application
- Cereals and Grains
- Pulses and Oilseeds
- Fruits and Vegetables
- Commercial Crops
List of Companies Covered in this Report:
- Bayer AG
- BASF SE
- Syngenta India Private Limited
- UPL Ltd.
- Corteva Agriscience
- PI Industries Limited
- IFFCO
- Coromandel International Ltd.
- Chambal Fertilisers and Chemicals Limited
- Rallis India Limited
- Deepak Fertilisers and Petrochemicals Corporation Limited (DFPCL)
- Crystal Crop Protection Ltd.
- Sumitomo Chemical India ltd.
- Dhanuka Agritech Ltd.
- Indofil Industries Limited (Modi Enterprises)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government subsidy rationalisation spurring bio-inputs adoption
- 4.2.2 Digitised agri-credit and e-commerce platforms expanding chemical reach
- 4.2.3 Drone-based precision spraying unlocking untapped smallholder demand
- 4.2.4 Off-patent molecule wave enlarges export pipeline
- 4.2.5 Climate-linked pest outbreaks increasing pesticide intensity
- 4.2.6 Government schemes boosting domestic manufacturing capacity
- 4.3 Market Restraints
- 4.3.1 Disruptive raw-material dependence on China raising cost volatility
- 4.3.2 Accelerating state-level bans on high-toxicity actives
- 4.3.3 Growing counterfeit channel eroding branded volumes
- 4.3.4 Intensifying resistance to legacy insecticides
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Consumers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Fertilizers
- 5.1.1.1 Nitrogenous
- 5.1.1.2 Phosphatic
- 5.1.1.3 Potassic
- 5.1.1.4 Other Fertilizers
- 5.1.2 Pesticides
- 5.1.2.1 Herbicides
- 5.1.2.2 Insecticides
- 5.1.2.3 Fungicides
- 5.1.2.4 Other Pesticides
- 5.1.3 Adjuvants
- 5.1.4 Plant Growth Regulators
- 5.1.1 Fertilizers
- 5.2 By Application
- 5.2.1 Cereals and Grains
- 5.2.2 Pulses and Oilseeds
- 5.2.3 Fruits and Vegetables
- 5.2.4 Commercial Crops
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Bayer AG
- 6.4.2 BASF SE
- 6.4.3 Syngenta India Private Limited
- 6.4.4 UPL Ltd.
- 6.4.5 Corteva Agriscience
- 6.4.6 PI Industries Limited
- 6.4.7 IFFCO
- 6.4.8 Coromandel International Ltd.
- 6.4.9 Chambal Fertilisers and Chemicals Limited
- 6.4.10 Rallis India Limited
- 6.4.11 Deepak Fertilisers and Petrochemicals Corporation Limited (DFPCL)
- 6.4.12 Crystal Crop Protection Ltd.
- 6.4.13 Sumitomo Chemical India ltd.
- 6.4.14 Dhanuka Agritech Ltd.
- 6.4.15 Indofil Industries Limited (Modi Enterprises)


