

|
시장보고서
상품코드
2120575
세제 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Detergents - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
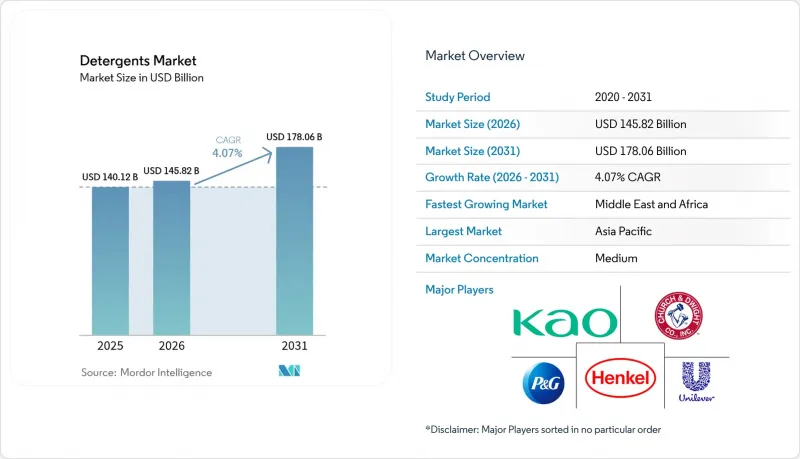
에 의하면, 세제 시장 규모는 2025년에 1,401억 2,000만 달러로 평가되었습니다. 2026년 1,458억 2,000만 달러에서 2031년까지 1,780억 6,000만 달러에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 4.07%를 나타낼 전망입니다.
본 보고서는 유형별(음이온성 세제, 양이온성 세제, 비이온성 세제, 양이온성(양성) 세제), 용도별(세탁, 가정용 세정제, 식기 세제, 연료 첨가제, 생물학적 시약, 기타),지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 세제 시장 동향 및 인사이트
신흥국에서의 세탁기 보급률 상승
인도의 자동 세탁기 보유율은 2020년 14%에서 2024년에는 28%로 증가했습니다. 이에 따라 1인당 세제 사용량이 증가하고 있습니다. 이는 드럼식 세탁 시 손세탁에 비해 30%-40% 더 많은 세제가 필요하기 때문입니다. 250ml 소용량 액상 팩이나 10회분 소포장은 진입 가격을 낮게 유지하면서도 이익률을 40% 이상으로 유지하는 데 도움이 되고 있습니다. 인도네시아와 베트남에서도 유사한 보급 곡선이 나타나고 있으며, 가전제품 보조금 및 할부 제도의 혜택을 받고 있습니다. 현재 배합 개발자들은 30분·20°C 세탁 주기에 최적화된 효소를 지정하고 있으며, BASF의 프로테아제 ‘Lavergy’는 에너지 소비량을 35% 줄이면서도 동등한 얼룩 제거 효과를 발휘하고 있습니다.
세제 시장의 전자상거래·D2C 채널 급성장
2024년, 소비자 대상 직접 구독 서비스 매출은 42억 달러에 달하고, 전년 대비 38% 성장을 기록했습니다. 이는 브랜드가 소매업체의 25%-35%에 달하는 마진을 피했기 때문입니다. 낮은 고객 확보 비용(가입자 1인당 18달러)과 3번째 배송 후 해지율이 15% 이하인 점이 수익성의 기반이 되고 있습니다. 북미에서는 온라인 판매 비중이 32%, 중국에서는 41%에 달했습니다. 이는 당일 배송과 성분 투명성을 강조하는 인플루언서 마케팅이 견인한 결과입니다. 농축형 포드나 스트립은 동등한 액체 세제에 비해 무게가 70% 가벼워, 라스트 마일 배송 비용을 0.12달러 절감하는 동시에 포장 폐기물을 60% 줄입니다.
세계 및 지역 차원의 엄격한 화학물질 규제
2023년 10월, 유럽화학물질청(ECHA)은 REACH 부속서 XVII에 따라 미세 플라스틱을 규제하고, 씻어내는 유형의 세제에서 의도적인 사용을 4년에서 12년의 이행 기간을 두고 금지했습니다. 2024년 4월, 미국 환경보호청(EPA)은 PFAS 규제를 확대하여 제조업체에 계면활성제 및 가공 조제제에 10억분의 1(ppb)을 초과하는 퍼플루오로알킬 물질과 폴리플루오로알킬 물질이 포함되어 있지 않음을 증명할 것을 의무화했습니다. 이로 인해 산업용 및 상업용 세정 제품에서 기존 불소계 계면활성제의 사용이 사실상 금지되었습니다. 이러한 규제는 신속한 배합 변경을 위한 연구개발 예산이 부족한 소규모 지역 브랜드에 불균형적인 영향을 미치는 반면, 다국적 기업은 연간 50만 톤을 초과하는 전 세계 생산량에 걸쳐 규정 준수 비용을 분산시킬 수 있습니다.
부문별 분석
2025년, 음이온성 계면활성제는 세제 시장 점유율의 45.84%를 차지했습니다. 이는 남아시아와 아프리카의 분말 및 액체 주력 제품을 뒷받침하는 저비용의 선형 알킬벤젠설포네이트에 기인한 것입니다. 신속한 최종 생분해성이 인정받는 비이온성 알코올 에톡실레이트와 알킬폴리글루코사이드 시장은 28일 이내에 호기성 분해를 의무화하는 EU 규제의 뒷받침을 받아 연평균 성장률(CAGR) 4.95%를 나타낼 것으로 예측됩니다. 헨켈(Henkel)은 2024년 ‘Persil Sensitive’의 배합을 재검토하여, LAS의 40%를 옥수수 전분 유래 알킬폴리글루코사이드로 대체했습니다. 이를 통해 제품의 성능을 유지하면서 수생 독성을 35% 저감하는 데 성공했습니다.
양이온성 4급 암모늄 계면활성제는 양전하를 띠고 있어 음이온계 계면활성제와의 배합이 제한되기 때문에 연화제 이외의 부문에서는 여전히 틈새 시장으로 남아 있습니다. EPA의 4급 암모늄 계면활성제에 대한 엄격한 심사를 받아, 더 빠르게 생분해되는 에스테르계 4급 암모늄 계면활성제 대체품에 대한 파일럿 테스트가 진행되고 있습니다. 2024년 물량의 6%를 차지하는 양성이온성 코카미도프로파일베타인은 중동 및 북아프리카의 경수 시장에서 거품을 안정화시키며, 폭넓은 pH 안정성 덕분에 미네랄 킬레이트제를 사용하지 않는 냉수용 포드에 적합합니다.
지역별 분석
아시아태평양은 2025년 전 세계 물량의 44.10%를 차지했습니다. 이는 인도와 인도네시아의 세탁기 보유 대수가 두 배로 증가한 점, 중국의 견조한 전자상거래 성장, 효소가 풍부한 액체 세제의 프리미엄화 추세가 주도한 결과입니다. ‘블루 문’이나 ‘리비’와 같은 현지 유력 기업들은 온라인을 통한 직접적인 고객 참여와 수요에 맞춘 향 제공을 통해 중국 액체 세제 부문에서 38%의 점유율을 차지하고 있습니다. 인도 시장은 세탁기를 처음 사용하는 소비자를 대상으로 한 합리적인 가격의 250ml 팩에 힘입어 2024년에 7.2% 성장했습니다. 성숙한 시장인 일본과 한국에서는 얼룩 제거 속도를 30% 가속화하는 바이오 유래 이세티온산계 계면활성제에 주력하고 있습니다.
중동 및 아프리카는 도시화로 인해 1인당 소비량이 3kg을 넘어섰으며, 연평균 성장률(CAGR) 4.78%로 가장 빠른 성장이 예상됩니다. 사우디아라비아의 ‘비전 2030’에 따른 인프라 확충 추진으로 세탁기 보급률은 65%를 향해 가고 있으며, 이는 경수에 대응하는 포드 유형 수요를 뒷받침하고 있습니다. 남아프리카 시장은 2024년에 수량 기준으로 5.8% 증가했습니다. 이는 간헐적인 전력 공급 상황에서 필수적인 저온 세탁 사이클에서도 뛰어난 성능을 발휘하는 효소가 함유된 분말 세제가 주도한 결과입니다. 사하라 이남 아프리카의 농촌 지역에서는 소포장 분말 세제가 주류를 이루고 있지만, 라고스나 나이로비에서는 프론트 로드식 세탁기의 보급이 확대됨에 따라 액체 세제에 대한 수요가 증가하고 있습니다.
유럽과 북미에서는 성장 속도가 둔화되고 있지만, 지속가능성 관련 혁신을 주도하고 있습니다. 독일에서는 2024년 세제 매출 중 친환경 라벨이 부착된 제품의 비중이 42%에 달했습니다. 미국에서는 포드나 스트립이 세탁량의 32%를 차지하고 있으며, 캐나다와 영국의 식료품점에 설치된 리필 스테이션을 통해 포장재가 40% 감소했습니다. 남미는 2024년에 4.2%의 성장을 기록했습니다. 분말 세제는 여전히 68%의 점유율을 차지하고 있지만, 브라질과 아르헨티나의 도시 지역에서는 세탁기 보유율이 55%를 넘어서면서 액체 세제의 점유율이 증가하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the detergents market size was valued at USD 140.12 billion in 2025 and estimated to grow from USD 145.82 billion in 2026 to reach USD 178.06 billion by 2031, at a CAGR of 4.07% during the forecast period (2026-2031).
This report is Segmented by Type (Anionic, Cationic, Non-Ionic, and Zwitterionic), Application (Laundry, Household Cleaning, Dishwashing, Fuel Additives, Biological Reagents, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). Market Forecasts are Provided in Terms of Value (USD).
Global Detergents Market Trends and Insights
Rising Washing-Machine Penetration in Emerging Economies
Automatic washer ownership in India increased from 14% in 2020 to 28% in 2024, resulting in a rise in per-capita detergent usage, as drum cycles require 30%-40% more product than hand-washing. Smaller 250ml liquid packs and 10-wash sachets help keep entry prices low while sustaining margins above 40%. Similar adoption curves in Indonesia and Vietnam benefit from appliance subsidies and installment-payment schemes. Formulators now specify enzymes optimized for 30-minute, 20°C cycles, with BASF's Lavergy protease delivering equivalent stain removal at 35% lower energy consumption.
Boom in E-Commerce and D2C Channels for Detergents
Direct-to-consumer subscriptions generated USD 4.2 billion in 2024, representing a 38% year-over-year growth as brands bypass retailers' 25%-35% markup. Lower acquisition costs (USD 18 per subscriber) and churn below 15% after the third delivery underpin profitability. Online sales reached 32% in North America and 41% in China, driven by same-day logistics and influencer marketing that emphasize ingredient transparency. Concentrated pods and strips, 70% lighter than equivalent liquids, shave USD 0.12 from last-mile freight while reducing packaging waste by 60%.
Stringent Global and Regional Chemical Regulations
In October 2023, the European Chemicals Agency, under REACH Annex XVII, restricted microplastics, banning their intentional use in rinse-off detergents with transition periods of 4 to 12 years. In April 2024, the US Environmental Protection Agency expanded PFAS restrictions, requiring manufacturers to certify that surfactants and processing aids contain no per- and polyfluoroalkyl substances above 1 part per billion, effectively banning legacy fluorosurfactants in industrial and institutional cleaning products. These regulations disproportionately affect smaller regional brands, which lack the R&D budgets for rapid reformulation, while multinationals spread compliance costs over global volumes exceeding 500,000 metric tons annually.
Other drivers and restraints analyzed in the detailed report include:
- Consumer Shift to Eco-Friendly and Biodegradable Formulations
- Cold-Water Enzyme Breakthroughs Cut Energy Use
- Raw-Material Price Volatility (Surfactants, Enzymes)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Anionic surfactants held 45.84% of the Detergents market share in 2025, supported by low-cost linear alkylbenzene sulfonates that anchor powder and liquid staples in South Asia and Africa. Non-ionic alcohol ethoxylates and alkyl polyglucosides, prized for rapid ultimate biodegradation, are forecast to grow at a 4.95% CAGR, lifted by EU rules requiring aerobic breakdown within 28 days. Henkel reformulated Persil Sensitive in 2024 by substituting 40% of LAS with corn-starch-derived alkyl polyglucosides, thereby lowering aquatic toxicity by 35% while retaining the product's performance.
Cationic quaternary ammonium surfactants remain niche outside fabric softeners because their positive charge limits co-formulation with anionics. EPA scrutiny of quats is prompting pilots of faster-biodegrading ester-quat alternatives. Zwitterionic cocamidopropyl betaine, 6% of 2024 volume, stabilizes foam in hard-water markets across the Middle East and North Africa, and its broad pH stability suits cold-water pods that avoid mineral chelators.
Complete Report Scope:
- By Type
- Anionic Detergents
- Cationic Detergents
- Non-ionic Detergents
- Zwitterionic (Amphoteric) Detergents
- By Application
- Laundry Cleaning Products
- Household Cleaning Products
- Dishwashing Products
- Fuel Additives
- Biological Reagents
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Russia
- Spain
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
The Asia-Pacific region accounted for 44.10% of the global 2025 volume, driven by a doubling of washing-machine ownership in India and Indonesia, robust e-commerce in China, and a shift toward premiumization of enzyme-rich liquids. Local champions such as Blue Moon and Liby hold a 38% share of China's liquid category through direct online engagement and tailored fragrances. India's market expanded by 7.2% in 2024, driven by affordable 250 ml packs targeting first-time machine users. Mature Japan and South Korea focus on bio-based isethionate surfactants that accelerate soil release by 30%.
The Middle East & Africa are forecast to deliver the fastest growth, with a 4.78% CAGR, as urbanization lifts per-capita consumption above 3 kg. Saudi Arabia's Vision 2030 infrastructure push raises washer penetration toward 65%, spurring demand for hard-water-tolerant pods. South Africa's market increased by 5.8% in volume in 2024, driven by enzyme-fortified powders that perform well in cold cycles, a necessity amid intermittent electricity supply. Sachet-priced powders dominate rural Sub-Saharan Africa, but liquid formats are gaining traction in Lagos and Nairobi as front-load adoption increases.
Europe and North America register slower growth but lead sustainability innovation. Germany's eco-labeled segment reached 42% of 2024 detergent sales. US pods and strips command 32% of laundry volume, and refill stations in Canadian and UK grocers reduce packaging by 40%. South America grew by 4.2% in 2024; powders still hold a 68% share, but liquids are rising in urban Brazil and Argentina, alongside washer ownership above 55%.
- Blue Moon Group
- Church & Dwight Co., Inc.
- Guangzhou Liby Group Co. Ltd
- Henkel AG & Co. KGaA
- Johnson & Johnson Private Limited
- Kao Corporation
- Lion Corporation
- Nice Group
- Procter & Gamble
- Reckitt Benckiser Group plc
- RSPL Group
- SC Johnson
- Seventh Generation Inc.
- Unilever
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising washing-machine penetration in emerging economies
- 4.2.2 Boom in e-commerce and D2C channels for detergents
- 4.2.3 Consumer shift to eco-friendly/biodegradable formulations
- 4.2.4 Cold-water enzyme breakthroughs cut energy use
- 4.2.5 Carbon-tax driven demand for ultra-concentrates
- 4.3 Market Restraints
- 4.3.1 Stringent global and regional chemical regulations
- 4.3.2 Raw-material price volatility (surfactants, enzymes)
- 4.3.3 Micro-plastic filtration mandates raise reformulation costs
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size & Growth Forecasts (Volume)
- 5.1 By Type
- 5.1.1 Anionic Detergents
- 5.1.2 Cationic Detergents
- 5.1.3 Non-ionic Detergents
- 5.1.4 Zwitterionic (Amphoteric) Detergents
- 5.2 By Application
- 5.2.1 Laundry Cleaning Products
- 5.2.2 Household Cleaning Products
- 5.2.3 Dishwashing Products
- 5.2.4 Fuel Additives
- 5.2.5 Biological Reagents
- 5.2.6 Other Applications
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 Italy
- 5.3.3.4 France
- 5.3.3.5 Russia
- 5.3.3.6 Spain
- 5.3.3.7 NORDIC Countries
- 5.3.3.8 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Blue Moon Group
- 6.4.2 Church & Dwight Co., Inc.
- 6.4.3 Guangzhou Liby Group Co. Ltd
- 6.4.4 Henkel AG & Co. KGaA
- 6.4.5 Johnson & Johnson Private Limited
- 6.4.6 Kao Corporation
- 6.4.7 Lion Corporation
- 6.4.8 Nice Group
- 6.4.9 Procter & Gamble
- 6.4.10 Reckitt Benckiser Group plc
- 6.4.11 RSPL Group
- 6.4.12 SC Johnson
- 6.4.13 Seventh Generation Inc.
- 6.4.14 Unilever
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


