

|
시장보고서
상품코드
2121209
금속 캔 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Metal Cans - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
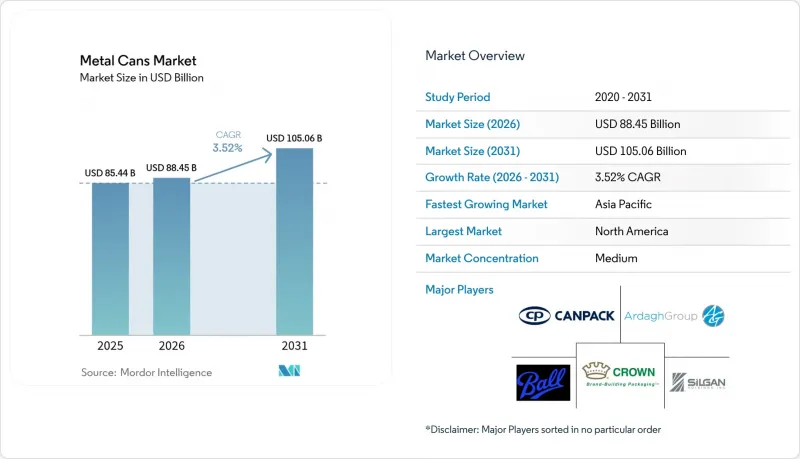
에 의하면, 2026년 세계의 금속 캔 시장 규모는 884억 5,000만 달러로 추정되고, 2025년 854억 4,000만 달러에서 확대해, 2031년에는 1,050억 6,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 3.52%로 성장할 것으로 전망됩니다.
본 보고서는 소재 유형별(알루미늄, 강철), 캔 구조별(2피스, 3피스 등), 용량 및 크기별(250ml 이하, 250-500ml 등), 제조 공정별(인발·평탄화, 인발·재인발 등), 최종 사용자 산업별(식품, 음료, 퍼스널케어 및 화장품, 기타), 지역별(북미, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 금속 캔 시장 동향 및 인사이트
알루미늄 가격 변동이 경량화 도입을 가속화
각 제조업체는 예측 불가능한 알루미늄 가격 변동에 대응하여, 이익률을 희생하기보다는 재료 사용량을 줄이는 방식으로 대처하고 있습니다. 2024년에 상용화된 ‘ReAl Gen 2’는 상단 하중 강도를 유지하면서 캔의 두께를 최대 15% 줄여, 원자재 가격 변동을 직접 상쇄합니다. 또한 경량화된 캔은 물류 시 배출량을 줄여, 기업의 넷제로 달성을 위한 로드맵과도 부합합니다. 고급 브랜드는 그 미관과 지속가능성이 더 높은 매장 가격을 정당화하는 요소이므로, 기술 도입에 따른 추가 비용을 적극적으로 흡수하고 있습니다. 특허 동향을 살펴보면, 설계자들이 강도 대 중량 비율을 높이고 고속 충격 압출을 가능하게 하는 미세 합금 배합의 미세 조정을 진행하고 있음을 알 수 있습니다. 생산 라인의 전환이 진행됨에 따라, 금속 캔 시장은 재료 집약도의 저하와 경제적 회복력 강화라는 선순환을 누리고 있습니다.
전 세계 DRS 프로그램이 리필·보증금 순환을 확대
의무화된 보증금 반환 제도(DRS)는 음료 용기의 순환을 완성하여, 무한히 재활용 가능한 알루미늄에 체계적인 우위를 가져다주고 있습니다. 2024년부터 시행되고 있는 유럽의 개정 ‘포장 및 포장 폐기물 규정’은 알루미늄이 쉽게 달성할 수 있는 소재별 야심찬 목표를 설정하고 있습니다. 싱가포르와 독일에서는 회수율이 90%를 초과하고 있으며, 안정적인 2차 원료를 공급함으로써 제조업체를 변동성이 심한 버진 원료 공급 위험으로부터 보호하고 있습니다. 이러한 순환을 통해 수명 주기 배출량이 감소하고, 생산자의 규정 준수 비용도 절감됩니다. 그 결과, 브랜드 소유주들은 새로운 음료 하위 부문에서 캔으로의 전환을 촉진하고 있습니다. 인프라가 성숙해짐에 따라, DRS의 경제성은 PET나 연포장재와 비교하여 금속 캔 시장의 매력을 더욱 높이고 있습니다.
신흥 시장에서 PET 및 연포장의 비용 우위
소득 수준이 여전히 낮은 지역에서는 PET 병이나 파우치가 배송 비용 기준으로 캔보다 15-25% 저렴하기 때문에 인도, 브라질 및 동남아시아 일부 지역에서 금속 캔의 보급이 주춤하고 있습니다. 현지에서의 PET 수지 생산과 경량 물류 덕분에 매장 판매 가격은 낮게 유지되고 있습니다. 그러나 2024년에 시행될 인도의 새로운 EPR(생산자 책임 회수 제도) 규정에 따라 사용 후 제품의 처리 책임이 금전적으로 부과됨에 따라 플라스틱의 가격 우위가 점차 사라지고 있으며, 소매업체들은 고급 지향 서브 브랜드를 위해 알루미늄 용기 도입을 시도하고 있습니다.
부문 분석
알루미늄은 2025년에 금속 캔 시장에서 70.56%라는 압도적인 점유율을 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 4.35%를 기록할 전망입니다. 이러한 우위는 1차 제련에 비해 에너지 소비량을 95% 절감할 수 있는 폐쇄형 재활용 시스템에 의해 뒷받침되며, 이를 통해 브랜드 소유자의 스코프 3 배출량이 감소하고 있습니다. 음료, 퍼스널케어, 의약품 각 분야에서 마케팅 담당자들은 알루미늄의 인쇄 적합성과 내식성을 활용하여 프리미엄 SKU의 차별화를 꾀하고 있습니다. 동시에 탈탄소화 압력이 높아지는 가운데, 탄소세 부담 증가에 직면한 철강 제조업체에 비해 알루미늄의 경쟁력이 높아지고 있습니다.
철강은 무게 증가라는 단점보다 물리적 견고성이 우선시되는 분야-주로 통조림 육류 및 가열 조리 식품-에서 여전히 필수적인 소재입니다. 그러나 지속적인 탈탄소화 비용이 장기적인 가격 경쟁력을 약화시키고 있습니다. 생산자들은 두께를 얇게 만들기 위해 양철에 크롬을 합금화하여 대응하고 있지만, 대체 위험은 여전히 남아 있습니다. 투자자들에게 있어 금속 캔 시장은 명확한 소재의 양극화를 반영하고 있습니다. 즉, 성장을 주도하는 알루미늄과 안정성을 담당하는 철강입니다.
2피스 캔은 연간 수십억 개의 음료 캔을 생산하는 효율적인 인발·프레스 라인 덕분에 2025년에도 54.06%의 점유율을 유지했습니다. 이 형태는 무게, 비용, 적재 강도를 균형 있게 갖추고 있어 금속 캔 시장 규모의 기반으로서 그 역할을 두드러지게 하고 있습니다. 혁신 측면에서는 이음매 없는 형태와 첨단 밸브를 추구하는 퍼스널케어 브랜드 수요에 힘입어, 모노블록식 에어로졸 캔의 설계가 연평균 성장률(CAGR) 4.78%로 확대되고 있습니다.
충격 압출 성형된 모노블록 캔은 리필 가능한 카트리지 시스템과 초경량 쉘을 가능하게 하여, 데오도란트 및 헤어 미스트 분야에서 친환경 프리미엄 가격대의 개척을 가능하게 하고 있습니다. 3피스 용접 캔은 시장에서의 존재감이 점차 약해지고 있지만, 무게보다 맞춤형 직경 및 목 모양이 중시되는 대용량 푸드서비스 및 전문 제품 분야에서 틈새 수요를 유지하고 있습니다. 전반적으로 구조의 다양성 덕분에 컨버터는 다양한 제품의 점도, 충전 압력 및 보관 기간 요건을 충족할 수 있게 되었습니다.
지역별 분석
2025년, 북미는 매출 점유율 39.72%로 전 세계 금속 캔 시장을 주도했습니다. 성숙한 청량음료 소비, 매우 효율적인 문 앞 수거, 그리고 생산자 책임 회수(EPR) 법이 안정적인 캔 수요를 뒷받침하고 있습니다. 지역별 알루미늄 재활용률은 75% 전후로 유지되고 있어, 공급 안정성을 확보하는 동시에 신금속에 대한 의존도를 낮추고 있습니다. 미국 및 멕시코의 신규 생산 능력 확장 계획으로 2억 달러가 넘는 투자가 최근 발표된 것은 점진적이긴 하지만 꾸준한 성장에 대한 장기적인 신뢰를 보여줍니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 5.88%를 나타낼 것으로 예측되며, 이는 세계에서 가장 빠른 성장세입니다. 도시로의 인구 이동, 중산층 소득 증가, 그리고 RTD(즉석 음용) 제품의 혁신적인 기술 급증으로 인해 캔 취급량은 계속 확대되고 있습니다. 일본의 보증금 제도에 따라 2024년에는 알루미늄 캔의 93%가 회수되어, 주변 국가들에게 순환 경제의 벤치마크가 되고 있습니다. 중국이 수입 의존에서 지역 수출 거점으로 전환한 것은 자국 내 생산으로의 전략적 전환과 세계 공급망에 대한 영향력 확대를 보여줍니다.
유럽에서는 기회와 복잡성이 공존하고 있습니다. 엄격한 BPA 규제로 인해 비용이 많이 드는 내부 코팅재 변경이 불가피하지만, 한편으로는 동일한 규제가 캔의 지속가능성을 향상시키고 철제에서 알루미늄로의 전환을 가속화하고 있습니다. ‘그린 딜(Green Deal)’의 순환형 경제 목표에 따라 재활용 프리미엄이 상승하고 있으며, 단기적으로는 규정 준수 부담이 있겠지만 궁극적으로는 금속 캔 시장을 지탱하는 요인이 될 것입니다. 남미, 중동 및 아프리카는 수요의 개척지이지만, 인프라 부족과 가격 민감성으로 인해 보급이 더딘 상황입니다. 그러나 EPR(생산자 책임) 체계의 단계적 정비와 디지털화를 통해 예측 기간 동안 캔 보급률이 향상될 가능성이 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the global metal cans market size in 2026 is estimated at USD 88.45 billion, growing from 2025 value of USD 85.44 billion with 2031 projections showing USD 105.06 billion, growing at 3.52% CAGR over 2026-2031.
This report is Segmented by Material Type (Aluminium, and Steel), Can Structure (Two-Piece, Three-Piece, and More), Capacity/Size (<=250ml, 250-500ml, and More), Manufacturing Process (Drawn and Ironed, Drawn and Redrawn, and More), End-User Industry (Food, Beverage, Personal Care and Cosmetics, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Metal Cans Market Trends and Insights
Aluminum Price Volatility Accelerates Lightweighting Adoption
Manufacturers are answering unpredictable aluminum costs by cutting material use instead of sacrificing margins. ReAl Gen 2, commercialized in 2024, reduces can wall thickness up to 15% while preserving top-load strength, directly offsetting commodity swings. Lighter cans also ease logistics emissions, aligning with corporate net-zero roadmaps. Premium brands willingly absorb the incremental technology cost because the aesthetic and sustainability credentials support higher shelf prices. Patent activity shows designers fine-tuning micro-alloy recipes that raise strength-to-weight ratios and enable high-speed impact extrusion. As more lines convert, the metal cans market enjoys a reinforcing cycle of lower material intensity and enhanced economic resilience.
Global DRS Programs Expanding Refill-Deposit Loops
Mandatory deposit-return systems are closing the loop on beverage containers and systematically advantaging infinitely recyclable aluminum. Europe's updated Packaging and Packaging Waste Regulation, in force since 2024, sets aggressive material-specific targets that aluminum readily meets. Singapore and Germany post return rates above 90%, providing reliable secondary feedstock that shields manufacturers from volatile virgin supply. These loops shrink lifecycle emissions and reduce producer compliance fees, which in turn encourage brand owners to pivot toward cans in new beverage sub-segments. As infrastructure matures, DRS economics further elevate the attractiveness of the metal cans market relative to PET and flexibles.
PET and Flexibles Cost Advantage in Emerging Markets
Where incomes stay modest, PET bottles and pouches undercut cans by 15-25% on a delivered-cost basis, slowing metal penetration in India, Brazil, and parts of Southeast Asia. PET's local resin output and lightweight logistics keep shelf prices low. Yet new Indian EPR rules effective 2024 have started to erode plastics' price edge by monetizing end-of-life liabilities, encouraging retailers to trial aluminum formats for aspirational sub-brands.
Other drivers and restraints analyzed in the detailed report include:
- Growth in RTD Beverage Launches
- Food-Waste Reduction Initiatives Driving Shelf-Stable Formats
- EU BPA-Migration Limits on Epoxy Liners
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Aluminum captured a commanding 70.56% metal cans market share in 2025 and is on course for a 4.35% CAGR through 2031. That dominance rests on closed-loop recycling systems that require 95% less energy than primary smelting, lowering scope 3 emissions for brand owners. Across beverages, personal care, and pharmaceuticals, marketers leverage aluminum's printable surface and corrosion resistance to differentiate premium SKUs. In parallel, decarbonization pressures elevate aluminum versus steel, whose mills face rising carbon fees.
Steel remains essential where physical robustness overrides weight penalties-chiefly in canned meats and heat-processed meals. Yet continuing decarbonization costs are eroding its long-term price competitiveness. Producers respond by alloying tinplate with chromium to trim gauge, but substitution risk persists. For investors, the metal cans market reflects a clear material bifurcation: aluminum for growth, steel for stability.
Two-piece cans preserved 54.06% share in 2025 thanks to efficient drawn-and-ironed lines that churn out billions of beverage units annually. These formats balance weight, cost, and stacking strength, underscoring their role as the backbone of the metal cans market size. On the innovation front, monobloc aerosol designs are expanding at a 4.78% CAGR, helped by personal-care brands seeking seamless shapes and advanced valves.
Impact-extruded monoblocs enable refillable cartridge systems and ultralight shells, unlocking eco-premium price points in deodorants and hair mists. Three-piece welded cans, while aging, sustain niche demand in large-volume foodservice and specialty products where customized diameters or necked ends matter more than weight. Overall, structural variety equips converters to serve diverse product viscosities, filling pressures, and shelf-life requirements.
Complete Report Scope:
- By Material Type
- Aluminium
- Steel
- By Can Structure
- Two-Piece
- Three-Piece
- Monobloc Aerosol
- By Capacity / Size
- <=250 ml
- 250-500 ml
- 500-1,000 ml
- >1,000 ml
- By Manufacturing Process
- Drawn and Ironed (D&I)
- Drawn and Redrawn (DRD)
- Impact Extrusion
- By End-User Industry
- Food
- Beverage
- Personal Care and Cosmetics
- Pharmaceuticals
- Paints and Industrial Chemicals
- Automotive Fluids and Lubricants
- Other End-User Industry
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Vietnam
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America led the global metal cans market with 39.72% revenue share in 2025. Mature soft-drink consumption, highly efficient curbside collection, and EPR statutes underpin stable can demand. Regional aluminum recycling rates hover near 75%, ensuring supply security while muting virgin-metal exposure. Recent announcements exceeding USD 200 million for new capacity in the United States and Mexico signal long-term confidence in steady, if incremental, growth.
Asia-Pacific is projected to log a 5.88% CAGR to 2031, the fastest worldwide. Urban migration, rising middle-class incomes, and surging RTD innovations keep can volumes expanding. Japan's deposit-scheme framework recovered 93% of aluminum cans in 2024, setting a circular-economy benchmark for neighbors. China's move from import dependence to regional export hub illustrates the strategic shift toward indigenous manufacturing and broader influence over global supply networks.
Europe balances opportunity and complexity. Stringent BPA rules force costly liner shifts, yet the same regulations elevate cans' sustainability credentials and accelerate steel-to-aluminum substitution. The Green Deal's circularity targets amplify recycling premiums, ultimately supporting the metal cans market despite short-term compliance drag. South America and the Middle East and Africa represent frontier demand where infrastructure gaps and price sensitivity slow adoption, but gradual EPR frameworks and digitization could lift can penetration over the forecast horizon.
- Ball Corporation
- Crown Holdings Inc.
- Ardagh Group S.A.
- Silgan Holdings Inc.
- CAN-PACK S.A.
- Toyo Seikan Group Holdings Ltd.
- CPMC Holdings Ltd.
- Showa Denko K.K.
- Mauser Packaging Solutions LLC
- DS Containers Inc.
- CCL Container Inc.
- Independent Can Company
- Hindustan Tin Works Ltd.
- Saudi Arabian Packaging Industry Co. (SAPIN)
- Kian Joo Can Factory Berhad
- Colep Packaging S.A.
- Can-One Berhad
- Greif Metal Packaging Division
- Massilly Holding SAS
- Universal Can Corp.
- Pacific Can China Holdings Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Industry Value Chain Analysis
- 4.3 Porter's Five Forces Analysis
- 4.3.1 Bargaining Power of Suppliers
- 4.3.2 Bargaining Power of Buyers/Consumers
- 4.3.3 Threat of New Entrants
- 4.3.4 Threat of Substitute Products
- 4.3.5 Intensity of Competitive Rivalry
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Market Drivers
- 4.5.1 Aluminum price volatility accelerates lightweighting adoption
- 4.5.2 Global DRS programs expanding refill-deposit loops
- 4.5.3 Growth in RTD beverage launches
- 4.5.4 Food-waste reduction initiatives driving shelf-stable formats
- 4.5.5 Craft aerosol packaging for personal-care "at-home spa" trend†
- 4.5.6 Smart-printing (QR/NFC) enabling supply-chain traceability
- 4.6 Market Restraints
- 4.6.1 PET and flexibles cost advantage in emerging markets
- 4.6.2 EU BPA-migration limits on epoxy liners
- 4.6.3 Steel mill decarbonisation costs inflating input prices†
- 4.6.4 E-commerce shift to "ship-in-own-container" formats
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Material Type
- 5.1.1 Aluminium
- 5.1.2 Steel
- 5.2 By Can Structure
- 5.2.1 Two-Piece
- 5.2.2 Three-Piece
- 5.2.3 Monobloc Aerosol
- 5.3 By Capacity / Size
- 5.3.1 <=250 ml
- 5.3.2 250-500 ml
- 5.3.3 500-1,000 ml
- 5.3.4 >1,000 ml
- 5.4 By Manufacturing Process
- 5.4.1 Drawn and Ironed (D&I)
- 5.4.2 Drawn and Redrawn (DRD)
- 5.4.3 Impact Extrusion
- 5.5 By End-User Industry
- 5.5.1 Food
- 5.5.2 Beverage
- 5.5.3 Personal Care and Cosmetics
- 5.5.4 Pharmaceuticals
- 5.5.5 Paints and Industrial Chemicals
- 5.5.6 Automotive Fluids and Lubricants
- 5.5.7 Other End-User Industry
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Spain
- 5.6.3.5 Italy
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 Australia
- 5.6.4.5 South Korea
- 5.6.4.6 Vietnam
- 5.6.4.7 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Egypt
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Ball Corporation
- 6.4.2 Crown Holdings Inc.
- 6.4.3 Ardagh Group S.A.
- 6.4.4 Silgan Holdings Inc.
- 6.4.5 CAN-PACK S.A.
- 6.4.6 Toyo Seikan Group Holdings Ltd.
- 6.4.7 CPMC Holdings Ltd.
- 6.4.8 Showa Denko K.K.
- 6.4.9 Mauser Packaging Solutions LLC
- 6.4.10 DS Containers Inc.
- 6.4.11 CCL Container Inc.
- 6.4.12 Independent Can Company
- 6.4.13 Hindustan Tin Works Ltd.
- 6.4.14 Saudi Arabian Packaging Industry Co. (SAPIN)
- 6.4.15 Kian Joo Can Factory Berhad
- 6.4.16 Colep Packaging S.A.
- 6.4.17 Can-One Berhad
- 6.4.18 Greif Metal Packaging Division
- 6.4.19 Massilly Holding SAS
- 6.4.20 Universal Can Corp.
- 6.4.21 Pacific Can China Holdings Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


