

|
시장보고서
상품코드
2125488
베트남의 금속 캔 포장 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Vietnam Metal Can Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
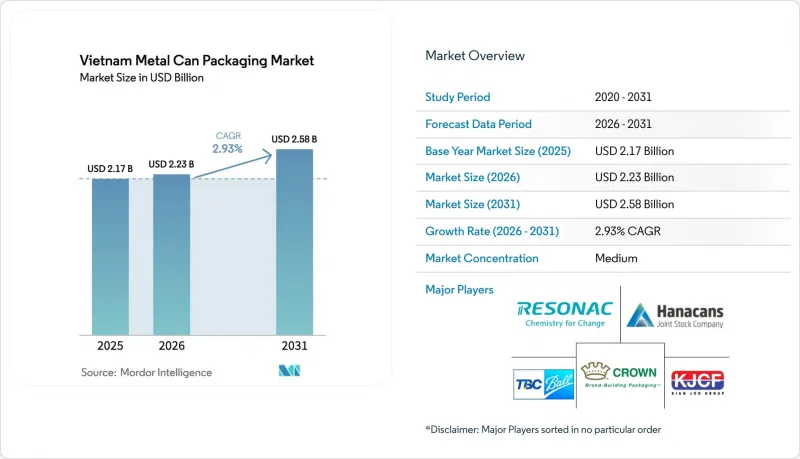
에 의하면, 베트남의 금속 캔 포장 시장 규모는 2025년에 21억 7,000만 달러로 평가되었고, 2026년 22억 3,000만 달러에서 2031년까지 25억 8,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 2.93%를 나타낼 전망입니다.
본 보고서는 소재 유형별(알루미늄, 강철), 캔 구조별(2피스, 3피스, 모노블록식 에어로졸), 용량 및 크기별(250mL 이하, 250-500mL, 500-1,000mL, 1,000mL 초과), 제조 공정별(드로우 앤 아이언(D&I), 드로우 앤 리드로우(DRD), 임팩트 압출 성형), 최종 사용자 산업별(식품, 음료, 기타)로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
베트남의 금속 캔 포장 시장 동향 및 인사이트
편의점 식음료 수요 증가
급속한 도시화로 인해 식료품 구매 경향이 변화하면서 1인분 소분 포장에 대한 수요가 증가하고 있습니다. 식품 가공 부문은 2024년에 7.4% 성장하여 793억 달러에 달했으며, 청량음료 소비량은 46억 5,800만 리터로 전년 대비 4.8% 증가를 기록했습니다. Vinamilk 등 국내 주요 기업들은 2024년 2분기에 11조 8,500억 베트남 동(4억 7,800만 달러)의 매출을 기록하며, 상온 보관이 가능하고 분량이 정량화된 포장에 대한 수요가 다시 한번 입증되었습니다. 250-500mL 용량대가 이미 주류를 이루고 있지만, 전자상거래와 외출 시 생활 방식의 확산으로 인해 250mL 이하 캔이 가장 높은 연평균 성장률(CAGR)을 기록하고 있습니다. 프리미엄 즉석 음용형 에너지 드링크와 알코올이 함유된 셀처는 용도의 폭을 더욱 넓히며, 베트남 금속 캔 포장 시장의 수량 성장을 뒷받침하고 있습니다.
높은 재활용률과 지속가능성을 위한 노력
베트남의 ‘생산자 책임 확대(EPR)’ 법에 따르면, 2024년 1월부터 알루미늄 재활용률을 최소 22%로 유지해야 합니다. 하이네켄 베트남은 2024년 시범 사업을 통해 850톤의 사용 후 캔을 처리했으며, 크라운 홀딩스는 2030년까지 음료 캔 회수율 92%를 목표로 하고 있습니다. 이러한 노력은 원자재 비용 절감, 재생 알루미늄 원료 확보, 브랜드 신뢰도 향상으로 이어지며, 베트남의 금속 캔 포장 시장에 연질 플라스틱 포장 경쟁사 대비 명확한 지속가능성 우위를 제공합니다.
연질 플라스틱 및 종이 용기와의 경쟁 심화
종이 기반 ‘테트라 리카토’는 캔에 비해 배출량을 85% 줄일 수 있다고 주장하며, 2024년 말 도베코 손라(Doveco Sonla)사에서 국내 생산을 시작했습니다. SCG의 스타프린트 베트남(Starprint Vietnam)사 2,730만 달러 인수로 경량 종이 솔루션의 확산이 가속화되고 있습니다. 약 4,000개의 플라스틱 기업이 생산 능력의 39%를 포장재에 할당하고 있어 가격 측면의 압박이 강해지고 있습니다. 전자상거래(EC)에서는 경량화가 중요하지만, 캔은 여전히 탄산 유지력, 개봉 감지 기능, 고급스러움 면에서 뛰어나며, 베트남 금속 캔 포장 시장의 핵심 수요를 계속해서 지탱하고 있습니다.
부문 분석
2025년, 알루미늄은 베트남 금속 캔 포장 시장 점유율의 70.02%를 차지했으며, 같은 해 시행된 22% 재활용 할당제로 인해 그 우위가 확고해졌습니다. 의약품 및 퍼스널케어 브랜드가 고순도 차단성을 중시하고 있기 때문에 알루미늄 제형에 대한 베트남 금속 캔 포장 시장 규모는 2031년까지 연평균 성장률(CAGR) 4.21%로 확대될 것으로 예측됩니다. 람동성에서 보크사이트를 알루미늄으로 정제하는 규모를 확대하기 위한 국내 계획은 향후 공급 안정성을 확보하는 동시에 운송에 따른 배출량을 줄일 것으로 기대됩니다.
강철은 특히 1,000mL를 초과하는 대용량 식품 캔 분야에서 강성과 비용 면에서의 우위가 두드러지는 부문으로 여전히 확고한 입지를 유지하고 있습니다. 호아팟사의 자체 생산 열연강판(HRC)은 납품 가격 인하에 기여하고 있지만, 강철의 무거운 무게가 장거리 물류의 걸림돌이 되고 있습니다. 각 브랜드 소유 기업들이 탄소 중립을 공약하는 가운데, 알루미늄의 입증된 폐쇄형 재활용성은 계속해서 강철 수요를 빼앗고 있으며, 베트남 금속 캔 포장 시장의 성장 궤도를 더욱 공고히 하고 있습니다.
2피스 캔은 고속 드로우 앤 아이언(D&I) 라인과 사진 품질의 인쇄 기술 덕분에 2025년 베트남 금속 캔 포장 시장에서 52.78%를 차지했습니다. 지속적인 경량화를 통해 강도를 저하시키지 않으면서 두께를 얇게 할 수 있어, 단위당 금속 사용량과 운송 비용을 절감하고 있습니다. 2피스 형태의 베트남 금속 캔 포장 시장 규모는 음료 생산량 증가와 옴니채널 소매의 성장에 따라 확대될 전망입니다.
모노블록식 에어로졸 용기는 내압성을 위해 이음매 없는 벽면이 요구되는 퍼스널케어 및 의약품 스프레이 제품에 힘입어, 2031년까지 연평균 성장률(CAGR) 5.61%를 나타낼 것으로 전망됩니다. CANPACK의 Quadromix 단기 납기 생산 기술을 통해 계절 한정 프로모션이 가능해지며, 매장 내 가시성이 향상됩니다. 3피스 구조 용기는 부피가 큰 식품 포장에 사용되지만, 가동률과 그래픽 유연성을 극대화하는 유연한 2피스 생산 라인에 대한 투자가 주류를 이루고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the Vietnam metal can packaging market size was valued at USD 2.17 billion in 2025 and estimated to grow from USD 2.23 billion in 2026 to reach USD 2.58 billion by 2031, at a CAGR of 2.93% during the forecast period (2026-2031).
This report is Segmented by Material Type (Aluminium, and Steel), Can Structure (Two-Piece, Three-Piece, and Monobloc Aerosol), Capacity/Size (<=250 Ml, 250-500 Ml, 500-1, 000 Ml, >1, 000 Ml), Manufacturing Process (Drawn and Ironed, Drawn and Redrawn, and Impact Extrusion), and End-User Industry (Food, Beverage, and More). The Market Forecasts are Provided in Terms of Value (USD).
Vietnam Metal Can Packaging Market Trends and Insights
Growing Demand for Convenience Food and Beverages
Rapid urbanization is transforming grocery baskets and boosting single-serve formats. The food-processing sector expanded 7.4% in 2024 to USD 79.3 billion, and soft-drink consumption hit 4.658 billion liters, a 4.8% year-over-year increase. Domestic leaders such as Vinamilk posted Q2 2024 revenue of VND 11,850 billion (USD 478 million), reaffirming demand for shelf-stable, portion-controlled packages. The 250-500 ml range already dominates, yet <=250 ml cans record the fastest CAGR due to e-commerce and on-the-go lifestyles. Premium ready-to-drink energy beverages and alcoholic seltzers further widen the application base, sustaining volume growth for the Vietnam metal can packaging market.
High Recycling Rates and Sustainability Commitments
Vietnam's Extended Producer Responsibility law enforces a minimum 22% aluminum recycling rate from January 2024. HEINEKEN Vietnam processed 850 tonnes of used cans in its 2024 pilot, while Crown Holdings targets a 92% beverage-can collection rate by 2030. These initiatives cut raw-material costs, unlock secondary-aluminum feedstock and burnish brand credentials, giving the Vietnam metal can packaging market a clear sustainability advantage over flexible plastic competitors.
Rising Competition from Flexible Plastic and Paper Formats
Paper-based Tetra Recart claims 85% lower emissions than cans and began domestic runs at Doveco Sơn La in late 2024. SCG's USD 27.3 million purchase of Starprint Vietnam accelerates lightweight paper solutions. Nearly 4,000 plastic firms allocate 39% of capacity to packaging, exerting pricing pressure. Weight savings matter for e-commerce, yet cans still excel in carbonation retention, tamper evidence and premium cues, sustaining core demand for the Vietnam metal can packaging market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Modern Retail and E-Commerce Networks
- Domestic HRC Capacity Expansion Improving Input Supply
- Metal Price Volatility and Emerging Trade Tariffs/CBAM
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Aluminum captured 70.02% of the Vietnam metal can packaging market share in 2025, a lead cemented by the 22% recycling quota that came into force the same year. The Vietnam metal can packaging market size for aluminum-based formats is projected to expand at a 4.21% CAGR through 2031 as pharmaceutical and personal-care brands prioritize high-purity barriers. Domestic plans to expand bauxite-to-aluminum refining at Lam Dong promise future supply security while cutting freight emissions.
Steel retains a foothold in large-volume food cans where rigidity and cost advantages prevail, especially above 1,000 ml. Hoa Phat's in-house HRC drives down delivered prices, but the metal's heavier weight handicaps long-distance logistics. As brand owners pledge carbon neutrality, aluminum's proven closed-loop recyclability keeps siphoning demand from steel, reinforcing the Vietnam metal can packaging market growth trajectory.
Two-piece cans accounted for 52.78% of the Vietnam metal can packaging market in 2025 thanks to high-speed D&I lines and photo-quality printing. Continuous lightweighting shrinks wall gauges without sacrificing strength, lowering per-unit metal use and freight costs. The Vietnam metal can packaging market size for two-piece formats will increase in tandem with beverage output and omnichannel retail growth.
Monobloc aerosol containers exhibit a 5.61% CAGR to 2031, propelled by personal-care and pharma spray products that demand seamless walls for pressure resistance. CANPACK's Quadromix short-run technology enables seasonal promotions, improving shelf visibility. While three-piece bodies serve bulky food packs, investments tilt toward flexible two-piece lines that maximize uptime and graphics flexibility.
Complete Report Scope:
- By Material Type
- Aluminium
- Steel
- By Can Structure
- Two-Piece
- Three-Piece
- Monobloc Aerosol
- By Capacity / Size
- <=250 ml
- 250-500 ml
- 500-1,000 ml
- >1,000 ml
- By Manufacturing Process
- Drawn and Ironed (D&I)
- Drawn and Redrawn (DRD)
- Impact Extrusion
- By End-User Industry
- Food
- Beverage
- Personal Care and Cosmetics
- Pharmaceuticals
- Paints and Industrial Chemicals
- Automotive Fluids and Lubricants
- Other End-User Industry
List of Companies Covered in this Report:
- TBC-Ball Beverage Can Vietnam Ltd (Ball Corporation)
- Resonac Holdings Corporation
- Hanacans Joint Stock Company
- Kian Joo Can (Vietnam) Co. Ltd (Kian Joo Can Factory Berhad)
- Crown Beverage Cans Vietnam Ltd (Crown Holdings Inc.)
- Can-Pack Vietnam Co. Ltd (Can-Pack SA)
- Vietnam Baosteel Can Co. Ltd (Baosteel Group Corp.)
- Royal Can Industries Company Ltd
- Superior Multi-Packaging Limited (Singapore)
- Nam Viet Packaging Manufacturing Co. Ltd
- My Chau Printing & Packaging Corp.
- Rexam Beverage Can Vietnam (Ardagh Group S.A.)
- Daiwa Can Company Vietnam Ltd
- Crown Asia Pacific Holdings Ltd - Danang Plant
- Alucon Public Company Ltd - Vietnam Rep. Office
- Thai Containers Group - Vietnam Metal Unit
- Dai Thien Loc Corporation (steel can-sheet supplier)
- Hoa Phat Steel Sheet Co. Ltd
- Novelis Asia (equity recycling affiliate)
- VNSteel Can Stock Division
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand for convenience food and beverages
- 4.2.2 High recycling rates and sustainability commitments
- 4.2.3 Expansion of modern retail and e-commerce networks
- 4.2.4 Domestic HRC capacity expansion improving input supply
- 4.2.5 Closed-loop beverage-can recycling pilots
- 4.2.6 Government FDI incentives for supporting industries
- 4.3 Market Restraints
- 4.3.1 Rising competition from flexible plastic and paper formats
- 4.3.2 Metal price volatility and emerging trade tariffs/CBAM
- 4.3.3 Limited domestic rolling capacity for can-sheet quality
- 4.3.4 Urban logistics bottlenecks raising last-mile costs
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 The Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Aluminium
- 5.1.2 Steel
- 5.2 By Can Structure
- 5.2.1 Two-Piece
- 5.2.2 Three-Piece
- 5.2.3 Monobloc Aerosol
- 5.3 By Capacity / Size
- 5.3.1 <=250 ml
- 5.3.2 250-500 ml
- 5.3.3 500-1,000 ml
- 5.3.4 >1,000 ml
- 5.4 By Manufacturing Process
- 5.4.1 Drawn and Ironed (D&I)
- 5.4.2 Drawn and Redrawn (DRD)
- 5.4.3 Impact Extrusion
- 5.5 By End-User Industry
- 5.5.1 Food
- 5.5.2 Beverage
- 5.5.3 Personal Care and Cosmetics
- 5.5.4 Pharmaceuticals
- 5.5.5 Paints and Industrial Chemicals
- 5.5.6 Automotive Fluids and Lubricants
- 5.5.7 Other End-User Industry
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 TBC-Ball Beverage Can Vietnam Ltd (Ball Corporation)
- 6.4.2 Resonac Holdings Corporation
- 6.4.3 Hanacans Joint Stock Company
- 6.4.4 Kian Joo Can (Vietnam) Co. Ltd (Kian Joo Can Factory Berhad)
- 6.4.5 Crown Beverage Cans Vietnam Ltd (Crown Holdings Inc.)
- 6.4.6 Can-Pack Vietnam Co. Ltd (Can-Pack SA)
- 6.4.7 Vietnam Baosteel Can Co. Ltd (Baosteel Group Corp.)
- 6.4.8 Royal Can Industries Company Ltd
- 6.4.9 Superior Multi-Packaging Limited (Singapore)
- 6.4.10 Nam Viet Packaging Manufacturing Co. Ltd
- 6.4.11 My Chau Printing & Packaging Corp.
- 6.4.12 Rexam Beverage Can Vietnam (Ardagh Group S.A.)
- 6.4.13 Daiwa Can Company Vietnam Ltd
- 6.4.14 Crown Asia Pacific Holdings Ltd - Danang Plant
- 6.4.15 Alucon Public Company Ltd - Vietnam Rep. Office
- 6.4.16 Thai Containers Group - Vietnam Metal Unit
- 6.4.17 Dai Thien Loc Corporation (steel can-sheet supplier)
- 6.4.18 Hoa Phat Steel Sheet Co. Ltd
- 6.4.19 Novelis Asia (equity recycling affiliate)
- 6.4.20 VNSteel Can Stock Division
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


