|
시장보고서
상품코드
2121210
인쇄 라벨 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Print Label - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
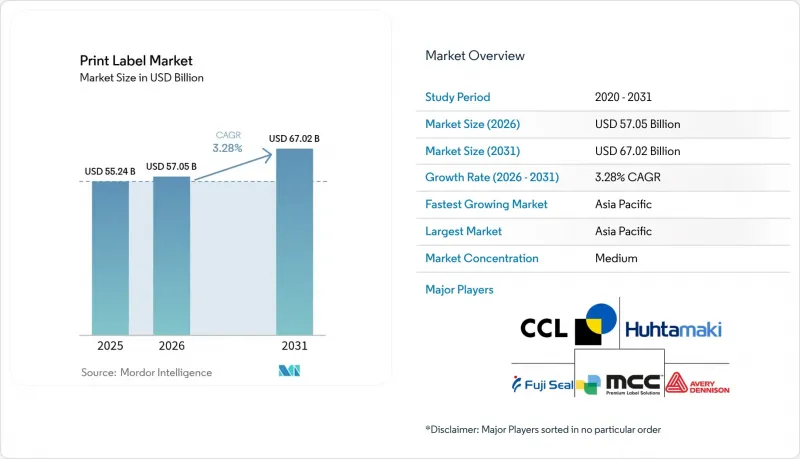
에 의하면, 2026년 인쇄 라벨 시장 규모는 570억 5,000만 달러로 추정되고, 2025년 552억 4,000만 달러에서 확대해, 2031년에는 670억 2,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR) 3.28%로 성장할 것으로 전망됩니다.
본 보고서는 인쇄 공정별(오프셋 리소그래피, 그라비아, 플렉소그래피, 스크린, 활판 인쇄, 전자 사진, 잉크젯), 라벨 형태별(습식 접착, 감압 접착, 라이너리스, 멀티파트 트래킹, 인몰드, 수축 및 스트레치 슬리브), 최종 사용자 산업별(식품, 음료, 헬스케어 및 의약품 등), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 인쇄 라벨 시장 동향 및 인사이트
소량 생산을 위한 고속 디지털 인쇄기 도입 가속화
디지털 잉크젯 플랫폼은 플렉소 인쇄의 기존 1만 개라는 임계치와 대조적으로, 불과 500개라는 소량 생산에서도 수익성 있는 생산을 가능하게 하여, 이를 통해 소비자 대상 브랜드를 위한 새로운 SKU 전략을 개척하고 있습니다. R.R. 도넬리(R.R. Donnelly)사가 조지아 주 시설 현대화에 투자한 2,500만 달러와 같은 설비 투자는 각 컨버터 기업들이 처리 능력과 가변 데이터의 유연성을 확보하기 위해 얼마나 큰 규모의 투자를 하고 있는지를 보여줍니다. 잉크젯과 플렉소 타워를 통합한 하이브리드 라인은 설비 전환을 효율화하지만, 한편으로는 작업자의 기술 격차도 초래하고 있습니다. 이러한 과제에 대해 플렉소그래피 기술 협회(Flexographic Technical Association) 등 업계 단체들은 ‘FIRST 5.0’ 커리큘럼을 통해 대응하고 있습니다. 고속 디지털 인쇄의 생산성이 아날로그 인쇄의 경제성과 융합됨에 따라, 라벨 인쇄 시장은 리드타임과 재고를 단축하는 혼합 기술 생산 셀로 전환될 것입니다.
폐기물 감축을 위한 브랜드 소유자의 라이너리스 라벨로의 전환
이형지를 제거함으로써 라벨 폐기물을 최대 30%까지 줄이고 롤 밀도를 높일 수 있으며, 이는 지속가능성 평가 지표에도 부합하는 물류 비용 절감으로 이어집니다. 시장을 선도하는 기업들은 특히 식품 소매 업계에서 확장된 생산자 책임(EPR) 요금이 도입을 촉진하고 있어, 라이너리스 제품의 매출이 두 자릿수 성장을 기록하고 있다고 보고하고 있습니다. 전환의 장벽으로는 습도 변동 하에서도 성능을 발휘해야 하는 특수한 부착기나 접착제 배합 등이 꼽히지만, 공급업체들은 생산 능력을 확대되고 있습니다. UPM Raflatac은 2025년 1분기에 전 분기 대비 13%의 성장을 보고했는데, 그 원인 중 하나는 유럽의 라이너리스 라벨 수요에 있습니다. 컨버터의 경쟁력은 기존의 감압 접착제 워크플로우와는 다른 새로운 코팅 및 슬리팅 기술을 습득할 수 있느냐에 달려 있습니다.
원자재 가격 변동이 컨버터의 이익률을 압박
제지 및 펄프, PET, 아크릴계 접착제의 가격 지수는 2024년 이후 두 자릿수 변동을 보이고 있으며, 수익원가의 최대 75%를 원자재가 차지하는 각 컨버터 기업들은 큰 영향을 받고 있습니다. 세계 기업들은 헤지 및 규모의 경제를 활용하여 대응하고 있지만, 에이버리 데니슨(Avery Dennison)은 매출이 0.1% 감소했음에도 비용 관리를 통해 EBIT를 유지한 반면, 중소기업(SME) 컨버터들은 연간 계약이 체결된 브랜드 소유주에게 추가 비용을 전가하는 데 어려움을 겪고 있습니다. 소노코(Sonoco)와 같은 통합 기업들은 공급을 확보하고 원자재 가격 변동의 영향을 완화하기 위해 3,000만 달러를 접착제 생산 능력 확대에 투자하고 있습니다. 기판 시장이 안정될 때까지는 이익률 압박으로 인해 인쇄 라벨 시장에서 중소기업의 투자 의욕이 위축될 것으로 보입니다.
부문별 분석
잉크젯 기술의 연평균 성장률(CAGR) 5.3%는 인쇄 라벨 시장의 재편 과정에서 이 기술이 차지하는 역할을 여실히 보여주고 있습니다. 플렉소 인쇄는 성숙한 제판 생태계 덕분에 여전히 대량 생산 SKU의 대부분을 차지하고 있지만, 잉크젯의 기판 범용성과 원클릭 전환 기능 덕분에 컨버터는 판촉 캠페인용 고수익 마이크로 런을 확보할 수 있게 되었습니다. 잉크젯 인쇄기와 관련된 인쇄 라벨 시장 규모는 설비 비용의 감소와 스크린 인쇄 품질에 필적하는 백색 잉크의 불투명도 덕분에 꾸준히 확대될 것으로 예측됩니다. 각 컨버터 기업에서는 플렉소 라인에 잉크젯 바를 추가하는 하이브리드 아키텍처가 설비 투자 계획의 주류를 이루고 있으며, 검증된 아날로그 다이컷 워크플로우를 유지한 채 가변 데이터 인쇄를 가능하게 하고 있습니다.
Drupa 2024에서 발표된 AstroNova사의 ‘TrojanLabel’ 플랫폼은 최소한의 셋업으로 오프셋 수준의 등록 정밀도를 요구하는 크래프트 음료 및 화장품 분야의 컨버터를 대상으로 한 미드웹 카테고리의 대표적인 사례입니다. 초장로트 생산 분야의 그라비아 인쇄 틈새 시장은 대형 음료 코팩커에게 여전히 확고한 입지를 차지하고 있지만, UV 잉크젯이 동등한 팬톤 색상 재현성을 제공함에 따라 오프셋 리소그래피 시장 점유율은 점차 줄어들고 있습니다. 스크린 인쇄 기술은 도막 두께가 극히 중요한 전자 기기와 내구 소비재 분야에서는 여전히 살아남고 있지만, 인쇄 라벨 시장에서의 점유율은 앞으로도 계속 축소될 것입니다.
지역별 분석
아시아태평양은 2025년에 35.86%의 점유율로 인쇄 라벨 시장을 장악했으며, 2031년까지 연평균 성장률(CAGR) 4.63%라는 최고 수준을 기록할 것으로 예측됩니다. 중국의 광범위한 제조거점과 2025년에 2,048억 1,000만 달러 규모에 달한 것으로 평가된 인도의 포장 시장 확대가 이 지역의 성장을 뒷받침하고 있습니다. 현지 컨버터 기업들은 급증하는 소비자 브랜드에 대응하기 위해 미드웹형 디지털 인쇄기에 대한 투자를 추진하고 있습니다. 한편, 일본과 한국의 정부 차원에서의 재활용 의무화로 인해 재활용 가능한 페이스 스톡과 워시오프 잉크의 채택이 촉진되고 있습니다. 동남아시아 국가들은 전자상거래 풀필먼트 허브로 전환되고 있어, 열전사 배송 라벨과 QR 코드 기반 반품 태그에 대한 수요를 자극하고 있습니다.
북미는 계속해서 기술의 선두주자 역할을 하고 있으며, 대형 소매점의 규제를 배경으로 클라우드 연결형 RFID 라벨의 급속한 보급이 진행되고 있습니다. 2024년에는 수지 가격 하락으로 인한 이익률 압박이 매출에 부정적인 영향을 미쳤으나, 각 변환 업체들은 자동화 및 고부가가치 용도로의 확장을 통해 이러한 역풍을 상쇄했습니다. 2024년 11월로 다가온 해당 지역의 의약품 일련번호 부여 기한으로 인해, 전미의 공장에서 하드웨어 업그레이드가 촉진되었고, 인쇄 라벨 시장에서 스마트 라벨의 보급이 더욱 강화되었습니다.
유럽에서는 성숙한 수요와 엄격한 순환형 경제 규제가 공존하고 있습니다. 프랑스와 독일에서 확대 생산자 책임(EPR) 제도가 도입됨에 따라, 라이너가 없는 라벨이나 단일 소재 구조의 라벨이 우대받고 있습니다. 영국의 ‘필수 요건 규정(Essential Requirements Regulations)’은 두께 감소와 재활용성을 지침으로 삼고 있어, 무용제 접착제의 연구 개발을 촉진하고 있습니다. 동유럽의 각 컨버터 기업들은 규제 준수를 희생하지 않으면서 비용 효율성을 추구하는 EU 전역의 브랜드로부터 수탁 제조 주문을 확보하고 있습니다.
라틴아메리카, 중동 및 아프리카의 기여도는 아직 작지만 증가 추세를 보이고 있습니다. 브라질과 멕시코에서는 음료용 수축 슬리브의 생산 능력을 확대하고 있는 반면, 걸프협력회의(GCC) 회원국들은 포장 식품 분야로 사업을 다각화하며, 자본 설비뿐만 아니라 기술적 노하우도 수입하고 있습니다. 아프리카 시장은 무역 장벽과 인프라 제약에 직면해 있지만, 모바일 커머스의 성장은 가변 데이터 라벨 솔루션의 장기적인 가능성을 시사하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, print label market size in 2026 is estimated at USD 57.05 billion, growing from 2025 value of USD 55.24 billion with 2031 projections showing USD 67.02 billion, growing at 3.28% CAGR over 2026-2031.
This report is Segmented by Print Process (Offset Lithography, Gravure, Flexography, Screen, Letterpress, Electrophotography, and Inkjet), Label Format (Wet-Glue, Pressure-Sensitive, Linerless, Multi-Part Tracking, In-Mold, and Shrink and Stretch Sleeves), End-User Industry (Food, Beverage, Healthcare and Pharmaceuticals, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Print Label Market Trends and Insights
Accelerated Adoption of High-Speed Digital Presses for Short-Run Production
Digital inkjet platforms enable profitable runs as low as 500 pieces, contrasting with flexography's historical 10,000-unit threshold, thereby unlocking new SKU strategies for consumer brands. Capital outlays, such as R.R. Donnelley's USD 25 million Georgia upgrade, illustrate the scale converters commit to gain throughput and variable-data flexibility. Hybrid lines integrating inkjet and flexo towers streamline changeovers yet create operator-skill gaps that industry groups like the Flexographic Technical Association address through FIRST 5.0 curricula. As high-speed digital productivity converges with analog economics, the print label market will migrate toward mixed-technology production cells that compress lead times and inventory.
Brand-Owner Shift Toward Linerless Labels for Waste Reduction
Eliminating release liners cuts label waste up to 30% and boosts roll density, generating logistics savings that resonate with sustainability scorecards. Market leaders report double-digit linerless revenue growth, especially within food retail, where Extended Producer Responsibility fees spur adoption. Transition barriers include specialized applicators and adhesive formulations that must perform across humidity swings, but suppliers are scaling capacity. UPM Raflatac reported 13% quarter-on-quarter growth in Q1 2025, partly on European linerless demand. Converter competitiveness hinges on mastering new coating and slitting techniques that diverge from conventional pressure-sensitive workflows.
Raw Material Price Volatility Pressuring Converter Margins
Paper pulp, PET, and acrylic adhesive indices have swung by double digits since 2024, leaving converters exposed because materials account for up to 75% of cost of sales. While global players leverage hedging and scale, Avery Dennison reported a 0.1% sales dip yet preserved EBIT via cost controls, SME converters struggle to pass surcharges to brand owners under annual contracts. Consolidators such as Sonoco channel USD 30 million into adhesive capacity expansions to secure supply and dilute input swings. Until substrate markets stabilize, margin compression will temper investment appetite among smaller firms in the print label market.
Other drivers and restraints analyzed in the detailed report include:
- E-Commerce Expansion Driving Variable-Data Printing Demand
- Regulatory Traceability Requirements Accelerating Smart-Label Adoption
- Technical Skill Gaps in Hybrid Digital-Flexo Operations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Inkjet technology's 5.3% CAGR underscores its role in reshaping the print label market. Flexography still produces the bulk of long-run SKUs thanks to mature platemaking ecosystems, but inkjet's substrate versatility and 1-click changeovers let converters secure high-margin micro-runs for promotional campaigns. The print label market size associated with inkjet presses is forecast to grow steadily as equipment costs fall and white ink opacity rivals screen-print quality. Across converters, hybrid architectures that bolt inkjet bars onto flexo lines dominate capex roadmaps, enabling variable data without abandoning proven analog die-cutting workflows.
AstroNova's TrojanLabel platform, launched at Drupa 2024, typifies the mid-web category aimed at craft beverage and cosmetics converters seeking near-offset registration with minimal setup. Gravure's niche in ultra-long runs remains secure for large beverage co-packers, yet offset lithography's footprint narrows as UV-inkjet delivers comparable Pantone coverage. Screen technology survives in electronics durables where film thickness is critical, but its share within the print label market will continue to erode.
Complete Report Scope:
- By Print Process
- Offset Lithography
- Gravure
- Flexography
- Screen
- Letterpress
- Electrophotography
- Inkjet
- By Label Format
- Wet-Glue Labels
- Pressure-Sensitive Labels
- Linerless Labels
- Multi-Part Tracking Labels
- In-Mold Labels
- Shrink and Stretch Sleeves
- By End-User Industry
- Food
- Beverage
- Healthcare and Pharmaceuticals
- Cosmetics and Personal Care
- Household Cleaning
- Industrial and Automotive
- Logistics and E-commerce
- Electronics and Appliances
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific dominated the print label market in 2025 with a 35.86% share and is projected to post the highest 4.63% CAGR to 2031. China's extensive manufacturing base and India's packaging expansion valued at USD 204.81 billion for 2025 underpin regional momentum. Local converters invest in mid-web digital presses to handle proliferating consumer brands, while government recycling mandates in Japan and South Korea encourage adoption of recyclable facestock and wash-off inks. Southeast Asian nations pivot toward e-commerce fulfillment hubs, stimulating demand for thermal shipping labels and QR-based return tags.
North America remains a technology bellwether, with rapid uptake of cloud-connected RFID labels driven by big-box retail mandates. Margin pressures from resin deflation challenged revenue in 2024, yet converters offset headwinds via automation and high-value applications. The region's pharma serialization deadline of November 2024 spurred hardware upgrades across U.S. plants, reinforcing smart-label penetration within the print label market.
Europe combines mature demand with stringent circular-economy rules. Extended Producer Responsibility fees in France and Germany favor linerless and mono-material constructions. The UK's Essential Requirements Regulations guide downgauging and recyclability, stimulating R&D into solvent-free adhesives. Eastern European converters attract contract manufacturing for pan-EU brands seeking cost efficiency without sacrificing regulatory compliance.
Latin America, the Middle East, and Africa account for smaller but rising contributions. Brazil and Mexico scale capacity for beverage shrink sleeves, while Gulf Cooperation Council members diversify into packaged foods, importing technical know-how alongside capital equipment. African markets grapple with trade barriers and infrastructure constraints, yet mobile commerce growth signals long-term potential for variable-data label solutions.
- CCL Industries Inc.
- Avery Dennison Corporation
- Multi-Color Corporation
- Fuji Seal International, Inc.
- Mondi plc
- Huhtamaki Oyj
- 3M Company
- Brady Corporation
- Ahlstrom-Munksjo Oyj
- Autajon Group
- Taghleef Industries LLC
- Ravenwood Packaging Ltd.
- SATO Holdings Corporation
- Taylor Corporation
- Weber Packaging Solutions, Inc.
- Resource Label Group, LLC
- Advanced Labelworx, Inc.
- Alliance Prints USA, Inc.
- Clarion Safety Systems, LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated adoption of high-speed digital (inkjet) presses for short-run, SKU-proliferated label jobs
- 4.2.2 Brand-owner shift toward linerless pressure-sensitive labels to cut waste and logistics costs
- 4.2.3 E-commerce boom driving demand for variable-data shipping and return labels
- 4.2.4 Regulatory push for smart/barcode labels enabling end-to-end traceability (e.g., EU FMD, U.S. DSCSA)
- 4.2.5 Growth of craft beverage and gourmet foods requiring premium, embellishment-rich labels
- 4.2.6 Emerging antimicrobial label coatings for food safety in cold-chain logistics
- 4.3 Market Restraints
- 4.3.1 Volatile paper, film and adhesive prices squeezing converter margins
- 4.3.2 Skill-gap in operating hybrid digital-flexo presses among SME converters
- 4.3.3 Rising brand-owner preference for direct-to-package digital printing (no label)
- 4.3.4 Difficult recycling of multi-layer shrink and in-mold labels in circular-economy markets
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Print Process
- 5.1.1 Offset Lithography
- 5.1.2 Gravure
- 5.1.3 Flexography
- 5.1.4 Screen
- 5.1.5 Letterpress
- 5.1.6 Electrophotography
- 5.1.7 Inkjet
- 5.2 By Label Format
- 5.2.1 Wet-Glue Labels
- 5.2.2 Pressure-Sensitive Labels
- 5.2.3 Linerless Labels
- 5.2.4 Multi-Part Tracking Labels
- 5.2.5 In-Mold Labels
- 5.2.6 Shrink and Stretch Sleeves
- 5.3 By End-User Industry
- 5.3.1 Food
- 5.3.2 Beverage
- 5.3.3 Healthcare and Pharmaceuticals
- 5.3.4 Cosmetics and Personal Care
- 5.3.5 Household Cleaning
- 5.3.6 Industrial and Automotive
- 5.3.7 Logistics and E-commerce
- 5.3.8 Electronics and Appliances
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 United Kingdom
- 5.4.3.2 Germany
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 Australia
- 5.4.4.6 Rest of Asia Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 United Arab Emirates
- 5.4.5.1.2 Saudi Arabia
- 5.4.5.1.3 Turkey
- 5.4.5.1.4 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Nigeria
- 5.4.5.2.3 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 CCL Industries Inc.
- 6.4.2 Avery Dennison Corporation
- 6.4.3 Multi-Color Corporation
- 6.4.4 Fuji Seal International, Inc.
- 6.4.5 Mondi plc
- 6.4.6 Huhtamaki Oyj
- 6.4.7 3M Company
- 6.4.8 Brady Corporation
- 6.4.9 Ahlstrom-Munksjo Oyj
- 6.4.10 Autajon Group
- 6.4.11 Taghleef Industries LLC
- 6.4.12 Ravenwood Packaging Ltd.
- 6.4.13 SATO Holdings Corporation
- 6.4.14 Taylor Corporation
- 6.4.15 Weber Packaging Solutions, Inc.
- 6.4.16 Resource Label Group, LLC
- 6.4.17 Advanced Labelworx, Inc.
- 6.4.18 Alliance Prints USA, Inc.
- 6.4.19 Clarion Safety Systems, LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment