

|
시장보고서
상품코드
2121415
인도의 플라스틱 포장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)India Plastic Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 인도의 플라스틱 포장 시장 규모는 2025년에 224억 4,000만 달러로 평가되었고, 2026년 231억 3,000만 달러에서 2031년까지 268억 9,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 3.06%를 기록할 전망입니다.
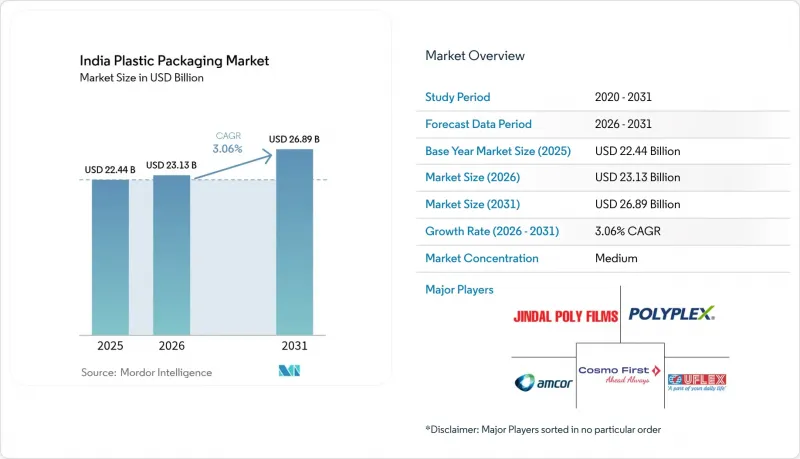
(1) 환경·산림·기후 변화부, 「확대 생산자 책임(EPR) 지침」, moef.gov.in 2024년에 제정된 확대 생산자 책임(EPR) 규정에 따라, 사용 후 폐기물에 대한 책임이 브랜드 소유자에게 부과됨에 따라 수요는 단순한 수량에서 부가가치가 높은 형태로 전환되고 있습니다. 이로 인해 컨버터는 재생 원료를 포함한 수지나 수익성이 높은 배리어 기술로 전환해야 하는 상황에 직면해 있습니다. 본 보고서는 소재 유형(폴리에틸렌, 폴리프로필렌 등), 포장 유형(연질, 경질),제품 형태(병·용기, 트레이·컨테이너 등), 최종 사용자 산업(식품, 음료 등), 제조 공정(압출 성형, 사출 성형, 블로우 성형, 열성형 등)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
인도의 플라스틱 포장 시장 동향 및 인사이트
확대되는 전자상거래 및 퀵커머스 물류 붐
2024년, 주요 대도시권에서 15분 배송 플랫폼을 통한 포장 물량은 300% 증가했으며, 여러 취급 공정을 거치더라도 확실한 밀봉 상태를 유지할 수 있는 위변조 방지 파우치에 대한 수요가 높아지고 있습니다. 자동화된 파우치 생산 라인을 도입한 컨버터는 분당 약 200팩의 사이클 타임을 달성하여, 하루 3회 재고를 보충하는 식료품 애그리게이터의 리드 타임을 단축하고 있습니다. 주요 FMCG 기업들은 충전 작업을 수요 거점 근처로 이전함으로써 이에 대응하고 있습니다. 예를 들어, 한 대형 음료 제조업체는 2025년에 아삼 주에 공장을 가동하여 평균 운송 거리를 450km로 단축하는 동시에 2차 포장 비용을 14% 절감했습니다. 이러한 변화로 인해 라스트 마일 이륜차 배송에서 흔히 발생하는 진동과 온도 변동에 견딜 수 있는 얇은 스트레치 필름에 대한 수요가 집중되고 있습니다. 또한, 지역 창고 네트워크에서는 몬순 시즌의 결로로 인한 손상을 방지하기 위해 WVTR이 10 g/m²/일 미만인 방습 필름이 지정되고 있습니다. 그 결과, 인도의 플라스틱 포장 시장에서는 충전율의 경제성을 해치지 않으면서도 기존 SKU보다 고가인 소형·고배리어성 솔루션에 대한 주문이 급속히 증가하고 있습니다.
경량 및 연포장 형태에 대한 수요
물류 사업자들은 유류 할증료를 전가하고 있으며, 이는 경량화를 촉진하는 인센티브가 되고 있습니다. 이에 따라 각 브랜드사는 경질 포장재에서 무게는 40% 가벼우면서도 낙하 시험 기준을 충족하는 단일 소재의 라미네이트 소재로 전환하고 있습니다. 배리어 코팅이 적용된 기판은 현재 산소 투과율을 1 cc/m2/일 미만으로 억제하는 데 성공하여, 상온 보관이 가능한 식품을 콜드체인 없이 더 먼 곳까지 운송할 수 있게 되었습니다. 분말 음료 믹스의 경우, 복합 캔 대신 플렉서블 파우치가 채택됨에 따라 각 컨버터 업체들은 100g 1회 분량당 최대 30%의 수지 중량을 절감할 수 있게 되어, 그램 수에 비례하여 증가하는 EPR(생산자 책임 회수) 수수료 부담을 경감하고 있습니다. 과거 유제품 용기 제조에 사용되던 열성형 라인은 현재 성형·충전·밀봉(FFS) 방식의 컵 뚜껑 제조로 전환되어, 프리미엄 요거트 신제품 출시에서 압도적인 시장 점유율을 차지하고 있습니다. 인도의 플라스틱 포장 시장에서는 이축 연신 PE 필름의 보급도 확대되고 있습니다. 이는 단일 소재 재활용 흐름에 부합하는 전 PE 라미네이트 소재의 실현을 가능하게 하기 위함입니다. 라미네이트 설비 개조에 소요되는 설비 투자는 라인당 평균 200만 달러이지만, 중소기업들은 정부가 지원하는 플라스틱 파크 내에서 후가공 설비를 공유하는 협동조합을 결성함으로써 위험을 줄이고 있습니다.
수지 가격 변동
2024년, 원유 가격 변동으로 인해 PE 및 PP의 계약 가격은 최대 30% 상승했으나, 6개월간 공급 계약을 체결한 가공업체들은 분기별로만 가격 조정이 가능하여 EBITDA 마진이 4퍼센트 포인트 가까이 압박받았습니다. 연질 플라스틱 가공업체의 재고는 평균적으로 고작 20일 분의 생산량에 불과합니다. 급격한 가격 급등은 이미 연 11%의 이자 부담을 안고 있는 운전 자금 조달에 추가적인 압박을 가하고 있습니다. 폴리머 선물을 통한 헤지는 아직 초기 단계에 있으며, 유동성이 낮아 월간 거래량의 5%를 초과하는 실질적인 헤지는 어렵습니다. 그 결과, 인도의 플라스틱 포장 시장에서는 협동조합이 공동 계약을 협상하여 대량 구매를 통한 할인을 확보하는 한편, 정유시설의 탱크 팜에 인접한 보관 창고를 공유하는 움직임이 나타나고 있습니다. 정부가 계획하고 있는 석유화학 분야의 ‘생산 연계형 인센티브(PLI)’ 제도에서는 관세 면제가 약속되어 있지만, 생산 능력 증강이 실현되는 것은 2028년 이후가 될 것이므로, 단기적인 전망은 세계 원자재 가격 변동의 영향을 받기 쉬운 상황입니다.
부문별 분석
2025년 인도의 플라스틱 포장 시장에서 폴리에틸렌은 37.78%라는 최대 점유율을 차지하고 있습니다. 이는 경쟁력 있는 수지 가격에 더해, 전국에 이미 도입된 블로우 필름 및 사출 성형 라인과의 호환성이 배경이 되고 있습니다. 쇼핑백, 농업용 시트, 세제 파우치 등 대량 생산 SKU에서 폴리에틸렌이 차지하는 비중이 생산량을 뒷받침하며, 주요 공장의 평균 가동률을 80% 이상으로 유지하고 있습니다. 또한 PE는 국내 크래커가 제공하는 유연한 원료 구성의 혜택도 받고 있으며, 전 세계적인 공급 차질이 발생하더라도 모노머의 안정적인 공급이 유지되기 때문에 현지 가공업체에게는 수입품과의 가격 비교에 있어 안정적인 기준이 됩니다. 한편, 폴리에틸렌 테레프탈레이트(PET)는 각 브랜드사가 즉석 음료나 조미료 용도로 투명성, 광택, 뛰어난 차단성을 요구함에 따라 2031년까지 연평균 성장률(CAGR) 4.18%를 나타낼 것으로 예측됩니다. PET의 재활용 가능성이라는 장점은 확대된 생산자 책임(EPR) 목표와 부합하며, 현재 진행 중인 여러 ‘병에서 병으로(Bottle-to-Bottle)’ 프로젝트를 통해 2027년까지 인도의 식품용 rPET 플레이크 시장 규모를 연간 100만 톤 이상으로 확대하는 것을 목표로 하고 있습니다.
성장세에도 불구하고, PET는 용융 여과 과정의 병목 현상에 직면해 있어 자본 집약도가 높아지고 있습니다. 고체 상태에서의 중축합이나 고압 사출 연신 공정이 필요하기 때문에 통합형 PET 생산 라인의 비용은 동등한 PE 생산 라인보다 20-25% 더 높습니다. 폴리프로필렌(PP)은 전자레인지용 트레이나 의약품용 캡 등 강성이나 내열성이 요구되는 특수 분야에서 수요가 있지만, 국내 PP 생산 능력은 섬유용 및 자동차용 등급에 중점을 두고 있어 공급은 여전히 부족한 상황입니다. 폴리스티렌(PS)과 발포 폴리스티렌(EPS)은 발포 식기에 대한 주 정부의 금지 조치로 인해 점차 감소하는 추세이지만, 완충성이 필요하고 재활용성에 대한 우려를 상쇄하는 가전제품 라이너 등에서는 여전히 틈새 수요가 존재합니다. 우타르 프라데시 주에서 진행 중인 3억 4,200만 달러 규모의 그린필드 프로젝트를 바탕으로 한 PLA 등 신흥 바이오플라스틱은 퇴비화 가능한 스낵 포장재 분야에서 잠재력을 지니고 있으나, 그 보급은 지자체 차원의 퇴비화 인프라가 시범 단계를 넘어 확대될지 여부에 달려 있습니다. 규제 당국이 각종 폴리머의 재생재 함유율 기준을 통일하기 위한 규범안을 공표하는 가운데, 가공업체들은 비용, 성능 및 재생재 함유율 할당 간의 균형을 맞춘 다중 소재 포트폴리오를 예상하고 있으며, 이는 향후 10년 동안 인도의 플라스틱 포장 산업의 구도를 재편하게 될 것입니다.
2025년 인도의 플라스틱 포장 시장 규모에서 연포장은 54.05%의 점유율을 차지하고 있으며, 이는 경질 포장에 비해 포장 중량 단위당 운송 비용을 30% 절감할 수 있는 필름 기반 시스템이 명확한 경제적 우위를 가지고 있음을 보여줍니다. EVOH 및 AlOx 코팅이 적용된 다층 라미네이트는 향기 차단 수명을 연장하여 냉장 트럭 없이도 지방으로의 유통을 가능하게 합니다. 탄소 발자국 공개를 목표로 하는 브랜드 소유주들은 수명 주기 평가(LCA) 모델에서 유리병에 비해 음료 1리터당 온실가스 배출량이 60% 적다고 평가되기 때문에 플렉서블 파우치를 선호하고 있습니다. 퀵 커머스의 급속한 성장으로 충동 구매에 적합한 가격대의 1회용 소포장에 대한 수요가 높아짐에 따라, 연포장 시장은 2031년까지 연평균 성장률(CAGR) 4.6%로 확대될 것으로 예측됩니다. 연포장이 주류를 이루고 있는 배경에는 생산 라인 전환이 신속하다는 점도 있습니다. 디지털 무용제 라미네이트는 2시간 이내에 경화되므로, 컨버터는 지역 한정 맛의 출시로 인한 SKU의 급증에도 대응할 수 있습니다.
경질 플라스틱 포장은 진열 시의 존재감과 촉감이 프리미엄 가격 책정을 좌우하는 화장품 분야에서 여전히 중요한 역할을 하고 있습니다. 퍼스널케어 제품용 압출 블로우 성형 HDPE 병에는 현재 근적외선을 이용한 선별이 가능한 마스터배치가 채택되어 있어, 다운스트림 공정에서의 재활용을 용이하게 하고 경질 포장을 순환형 경제의 목표에 부합시키고 있습니다. 사출 신장 블로우 성형된 PET 용기는 38mm 넥 마감이 유도 밀봉 라이너와 호환되어 휘발성 성분을 보존할 수 있기 때문에 뉴트라슈티컬 분야에서 점유율을 확대되고 있습니다. 그러나 EU의 테이저드 캡 요건이 전 세계 디자인에 영향을 미치면서 캡 및 마개용 수지 소비량은 정체 상태에 이르렀으며, 힌지 브리지의 경량화가 진행되고 있습니다. 이처럼 인도의 플라스틱 포장 시장에서는 미묘한 공존 관계가 나타나고 있습니다. 연포장재는 전자상거래의 성장세에 힘입어 성장하고 있는 반면, 경질 용기는 미관과 재사용성을 중시하는 프리미엄 틈새 시장에서 확고한 입지를 유지하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the India plastic packaging market size was valued at USD 22.44 billion in 2025 and estimated to grow from USD 23.13 billion in 2026 to reach USD 26.89 billion by 2031, at a CAGR of 3.06% during the forecast period (2026-2031).
[1] Ministry of Environment, Forest and Climate Change, "Extended Producer Responsibility Guidelines," moef.gov.in Demand pivots from pure volume to value-added formats as Extended Producer Responsibility (EPR) rules enacted in 2024 place the onus of post-consumer waste on brand owners, pushing converters toward recycled-content resins and higher-margin barrier technologies. This report is Segmented by Material Type (Polyethylene, Polypropylene, and More), Packaging Type (Flexible, Rigid), Product Form (Bottles and Jars, Trays and Containers, and More), End-User Industry (Food, Beverage, and More), Manufacturing Process (Extrusion, Injection Molding, Blow Molding, Thermoforming, and More). The Market Forecasts are Provided in Terms of Value (USD).
India Plastic Packaging Market Trends and Insights
Growing e-commerce and quick-commerce logistics boom
Package volumes from 15-minute delivery platforms grew 300% in major metros during 2024, requiring tamper-proof pouches that preserve integrity across multiple handling points. Converters that deploy automated pouch lines achieve cycle times near 200 packs per minute, shortening lead times for grocery aggregators that refresh inventory thrice daily. FMCG majors have responded by relocating filling operations closer to demand centers; for example, a leading beverage maker commissioned a plant in Assam in 2025, trimming average transit distance to 450 km and cutting secondary packaging spend by 14%. This shift concentrates demand for low-gauge stretch films that withstand vibration and thermal fluctuations common in last-mile two-wheeler delivery. Regional warehousing networks now specify moisture-barrier films with WVTR below 10 g / m2 / day to avoid condensation damage during the monsoon. The India plastic packaging market, therefore, receives a rapid influx of orders for small-format, high-barrier solutions that command price premiums over legacy SKUs without eroding fill-rate economics.
Demand for lightweight flexible formats
Logistics providers levy fuel-surcharge pass-throughs that incentivize weight reduction, steering brands away from rigid packs toward mono-material laminates that are 40% lighter yet meet drop-test thresholds. Barrier-coated substrates now achieve oxygen transmission rates below 1 cc / m2 / day, allowing shelf-stable food to travel farther without a cold chain. As flexible pouches replace composite cans in powdered beverage mixes, converters save up to 30% resin weight per 100 g serving, easing EPR fee liabilities that scale with grammage. Thermoforming lines that once served dairy tubs now pivot to form-fill-seal cup lidding, capturing an outsized share of premium yogurt launches. The India plastic packaging market also witnesses bi-axially oriented PE films gaining traction because they allow all-PE laminates that qualify for single-material recycling streams. Capital outlay for retrofitting lamination equipment averages USD 2 million per line; SMEs mitigate risk by forming cooperatives that share finishing assets inside government-backed plastic parks.
Resin price volatility
Crude swings drove PE and PP contract prices up to 30% during 2024, yet converters locked into six-month supply agreements could only reprice quarterly, compressing EBITDA margins by nearly 4 percentage points. Flexible converters carry inventory covering just 20 production days on average; sudden price hikes strain working capital facilities that already carry 11% interest. Hedging via polymer futures remains nascent, with low liquidity restricting meaningful coverage beyond 5% of monthly volume. The India plastic packaging market, therefore, sees cooperatives negotiating pooled contracts to gain bulk discounts while sharing storage depots adjacent to refinery tank farms. Government plans for a Production-Linked Incentive (PLI) scheme in petrochemicals promise duty waivers, but capacity additions will not materialize until 2028, leaving the near-term outlook vulnerable to global feedstock volatility.
Other drivers and restraints analyzed in the detailed report include:
- Uptake of recycled-content plastics
- EPR-linked rPET / rHDPE localization push
- Single-use-plastic regulatory bans
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene commands the highest 37.78% share of the India plastic packaging market in 2025, underpinned by competitive resin pricing and compatibility with blown-film and injection-molding lines already installed nationwide. Its role in high-volume SKUs such as shopping bags, agricultural sheets, and detergent pouches sustains throughput that keeps average operating rates above 80% in major plants. PE also benefits from the flexible feedstock slate of domestic crackers, which maintains a steady monomer supply even during global disruptions, giving local converters stable price benchmarks against imported parity levels. However, polyethylene terephthalate is projected to grow at a 4.18% CAGR through 2031 as brands seek clarity, gloss, and superior barrier credentials for ready-to-drink beverages and condiments. PET's recyclability advantage dovetails with EPR targets, and multiple bottle-to-bottle projects under implementation aim to lift the India plastic packaging market size for food-grade rPET flakes to more than 1 million TPA by 2027.
In spite of its growth, PET faces melt-filtration bottlenecks that raise capital intensity; integrated PET lines cost 20-25% more than equivalent PE lines due to solid-state polycondensation and higher-pressure injection stretches. Polypropylene fills specialized slots where rigidity and heat resistance matter, such as microwaveable trays and pharma caps, but supply remains tight because domestic PP capacities favor fiber and automotive grades. Polystyrene and EPS gradually decline owing to state bans on foamed tableware, though niche demand persists in appliance liners where cushioning outweighs recyclability concerns. Emerging bioplastics like PLA, backed by a USD 342 million greenfield project in Uttar Pradesh, hold potential in compostable snack packs but remain contingent on municipal composting infrastructure scaling beyond pilot units. As regulators publish draft norms to equate recycled-content thresholds across polymers, converters anticipate a multi-material portfolio balancing cost, performance, and recycle-content quotas, reshaping the India plastic packaging industry over the next decade.
Flexible formats account for 54.05% share of the India plastic packaging market size in 2025, demonstrating the clear economic edge of film-based systems that deliver 30% lower transportation cost per unit of packed weight than rigid alternatives. Multi-layer laminates engineered with EVOH or AlOx coatings extend aroma barrier life, enabling rural distribution without refrigerated trucks. Brand owners pursuing carbon-footprint disclosures favor flexible pouches because life-cycle-assessment models credit them with 60% fewer greenhouse-gas emissions per liter of beverage compared with glass bottles. Flexible packaging is forecast to expand at a 4.6% CAGR through 2031 as quick-commerce spurts heighten demand for single-serve sachets that meet impulse-buy price points. Flexible's dominance also stems from rapid line changeovers; digital solventless lamination cures in under two hours, allowing converters to manage SKU proliferation from regional flavor launches.
Rigid plastic packaging retains relevance in cosmetics where shelf presence and tactile cues command premium price points. Extrusion-blow-molded HDPE bottles for personal-care products now feature near-infrared sortable masterbatches that ease downstream recycling, aligning rigid formats with circularity goals. Injection-stretch-blown PET jars gain share in nutraceuticals because 38-mm neck finishes accommodate induction-seal liners, preserving volatile ingredients. However, cap-and-closure resin consumption plateaus as tethered-cap EU requirements influence design globally, prompting material light-weighting of hinge bridges. The India plastic packaging market thus exhibits a nuanced co-existence: flexible growth rides on e-commerce cycles, while rigid solutions maintain foothold in premium niches that value aesthetics and reusability.
Complete Report Scope:
- By Material Type
- Polyethylene (PE)
- Polypropylene (PP)
- Polyethylene Terephthalate (PET)
- Polystyrene and EPS
- Other Material Types
- By Packaging Type
- Flexible Plastic Packaging
- Rigid Plastic Packaging
- By Product Form
- Bottles and Jars
- Trays and Containers
- Pouches and Sachets
- Bags and Sacks
- Films and Wraps
- Other Product Forms
- By End-User Industry
- Food
- Beverage
- Pharmaceuticals and Healthcare
- Cosmetics and Personal Care
- Industrial
- Other End-user Industries
- By Manufacturing Process
- Extrusion
- Injection Molding
- Blow Molding
- Thermoforming
- Other Manufacturing Processes
List of Companies Covered in this Report:
- Amcor plc
- UFlex Limited
- Jindal Poly Films Limited
- Cosmo First Limited
- Polyplex Corporation Limited
- Manjushree Technopack Limited
- Hitech Corporation Limited
- TCPL Packaging Limited
- AptarGroup, Inc.
- Constantia Flexibles Group GmbH
- Mondi plc
- Sealed Air Corporation
- Huhtamaki India Limited
- Mold-Tek Packaging Limited
- ALPLA India Private Limited
- Garware Hi-Tech Films Limited
- Ester Industries Limited
- Chemco Plastic Industries Pvt. Ltd.
- Essel Propack Limited (EPL Ltd.)
- Sonoco Products Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing e-commerce and quick-commerce logistics boom
- 4.2.2 Demand for lightweight flexible formats
- 4.2.3 Uptake of recycled-content plastics
- 4.2.4 EPR-linked rPET/rHDPE localization push
- 4.2.5 AI-enabled converting lines for SMEs
- 4.2.6 Single-dose pharma pouch surge
- 4.3 Market Restraints
- 4.3.1 Resin price volatility
- 4.3.2 Single-use-plastic regulatory bans
- 4.3.3 Scarce food-grade PCR infrastructure
- 4.3.4 Import-dependent hi-end film machinery CAPEX
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Investment Analysis
- 4.7 Industry Value Chain Analysis
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Polyethylene (PE)
- 5.1.2 Polypropylene (PP)
- 5.1.3 Polyethylene Terephthalate (PET)
- 5.1.4 Polystyrene and EPS
- 5.1.5 Other Material Types
- 5.2 By Packaging Type
- 5.2.1 Flexible Plastic Packaging
- 5.2.2 Rigid Plastic Packaging
- 5.3 By Product Form
- 5.3.1 Bottles and Jars
- 5.3.2 Trays and Containers
- 5.3.3 Pouches and Sachets
- 5.3.4 Bags and Sacks
- 5.3.5 Films and Wraps
- 5.3.6 Other Product Forms
- 5.4 By End-User Industry
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Pharmaceuticals and Healthcare
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Industrial
- 5.4.6 Other End-user Industries
- 5.5 By Manufacturing Process
- 5.5.1 Extrusion
- 5.5.2 Injection Molding
- 5.5.3 Blow Molding
- 5.5.4 Thermoforming
- 5.5.5 Other Manufacturing Processes
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 UFlex Limited
- 6.4.3 Jindal Poly Films Limited
- 6.4.4 Cosmo First Limited
- 6.4.5 Polyplex Corporation Limited
- 6.4.6 Manjushree Technopack Limited
- 6.4.7 Hitech Corporation Limited
- 6.4.8 TCPL Packaging Limited
- 6.4.9 AptarGroup, Inc.
- 6.4.10 Constantia Flexibles Group GmbH
- 6.4.11 Mondi plc
- 6.4.12 Sealed Air Corporation
- 6.4.13 Huhtamaki India Limited
- 6.4.14 Mold-Tek Packaging Limited
- 6.4.15 ALPLA India Private Limited
- 6.4.16 Garware Hi-Tech Films Limited
- 6.4.17 Ester Industries Limited
- 6.4.18 Chemco Plastic Industries Pvt. Ltd.
- 6.4.19 Essel Propack Limited (EPL Ltd.)
- 6.4.20 Sonoco Products Company
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


