

|
시장보고서
상품코드
2121434
유럽의 위치 분석 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Location Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
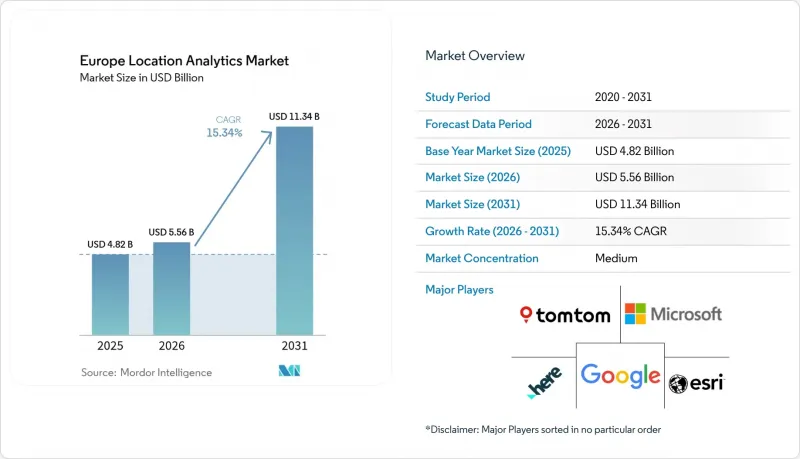
유럽의 위치 분석 시장 규모는 2025년에 48억 2,000만 달러로 평가되며, 2026년 55억 6,000만 달러에서 2031년까지 113억 4,000만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 15.34%가 될 전망입니다.
본 보고서는 위치 유형(실내 및 실외), 도입 형태(클라우드 및 온프레미스), 최종사용자(은행, 금융 서비스·보험, 기타), 용도(고객 방문 수 분석, 자산 추적, 위험·사고 관리, 기타), 및 지역(독일, 영국, 기타)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시됩니다.
유럽 위치 분석 시장의 동향 및 인사이트
실시간 차량 관리 솔루션 도입 확대
물류 사업자들은 공회전 거리를 줄이고 기업 지속가능성 보고 지침(CSRD)의 스코프 3 요건을 충족하기 위해 텔레매틱스 스택에 지리 공간 분석을 통합하고 있습니다. DHL은 2024년에 유럽의 전기자동차 차량군에 20억 유로(23억 3,000만 달러)를 할당하고, 엣지 게이트웨이를 교통 상황, 기상, 수송량 밀도 피드와 연동함으로써 경로 변동을 12% 줄였습니다. 마스크(Maersk)의 예측 도착 예정 시간(ETA) 엔진은 철도와 항만 간 인계에 위치 정보 AI를 적용함으로써 2024년 상반기에 허브에서의 체류 시간을 12% 단축했습니다. DB 카고(DB Cargo)는 자동화된 지오펜싱을 도입하여 건당 통관 소요 시간을 18분 단축함으로써 통관 절차를 신속하게 처리하고 있습니다. 현재 차량 관리 소프트웨어에는 위치 정보 분석과 예측 유지보수가 통합되어 있으며, 고도 프로필 및 도로 상황을 부품 마모 예측과 연계함으로써 고장을 미연에 방지하고 있습니다.
5G 확산 가속화가 가져오는 초지역 밀착형 분석
네트워크 슬라이싱 기능을 갖춘 독립형 5G는 10밀리초 미만의 지연을 보장하여, 증강 현실(AR) 내비게이션 및 자율주행형 창고용 지게차의 구현을 가능하게 합니다. Vodafone Germany는 2024년 중반까지 인구의 90%를 커버하며, 센티미터 단위의 정밀도를 가진 실내 위치 추적 기술을 활용한 프라이빗 5G 네트워크를 구현했습니다. Orange France는 2024년 말까지 국민의 75%에게 5G를 확대하여, 소매업체를 위한 실시간 혼잡도 히트맵 제공을 뒷받침하고 있습니다. ‘EU 디지털 데케이드’에서는 2030년까지 5G 커버리지율 75%를 목표로 하고 있으며, 공항 및 경기장에서의 밀리미터파 빔포밍을 지원합니다. 도이체 텔레콤과 TRUMPF는 UWB를 지원하는 공장에서 30cm의 정확도를 달성했으며, 5G 엣지 컴퓨팅이 클라우드 코어에 의존하지 않고도 진행 중인 작업 재고의 위치를 파악할 수 있음을 입증했습니다.
GDPR의 엄격한 위치 정보 동의 요건
유럽 데이터 보호 위원회는 2024년, Wi-Fi 및 BLE를 통한 MAC 주소 추적이 개인 데이터에 해당함을 명확히 하고, 소매업체에 동의 배너 표시를 의무화했습니다. 이로 인해 옵트인 비율은 옵트아웃 지역에 비해 30-40% 감소했습니다. 독일의 BSI는 클라우드로의 데이터 전송을 억제하기 위해 기기 내 처리와 차등 프라이버시(differential privacy)의 채택을 강력히 권장하고 있습니다. 벨기에는 명시적인 동의를 얻지 못했다는 이유로 한 비콘 공급업체에 25만 유로(291,596.25달러)의 벌금을 부과했으며, 이에 따라 업계 전반에 걸쳐 감사가 잇따랐습니다. 규정 준수 비용은 중소기업에 가장 큰 타격을 주고 있으며, 법무 부서를 보유한 대형 플랫폼 사업자와의 계약이 촉진되는 한편, 슈렘스 II 판결에서 문제시되고 있는 국경을 넘는 데이터 전송을 회피하기 위한 온프레미스 도입에 대한 수요도 높아지고 있습니다.
부문 분석
실내 분석 시장의 예상 연평균 성장률(CAGR)은 2026년부터 2031년까지 15.52%로 전망되며, 2025년 지출의 63.61%를 차지하는 실외 시스템을 능가할 것으로 예상됩니다. Wiliot사의 1달러 미만 앰비언트 IoT 태그와 Quuppa사의 10cm 정밀도 UWB(도착각 측정) 기술로 인해 하드웨어 진입 장벽이 낮아지면서, 유럽의 위치 분석 시장은 극장, 터미널, 병동 등으로의 침투를 더욱 심화시키고 있습니다. 기업의 구매 담당자들은 매월 유지보수 작업이 필요 없는 배터리 없는 설계를 높이 평가하고 있으며, 병원에서는 장비 분실률을 18% 감소시켰습니다. 갈릴레오 고정밀 서비스와 어디서나 이용 가능한 GPS 덕분에 대중교통 및 정밀 농업 분야에서 실외 분석은 여전히 필수적입니다. 그럼에도 불구하고 각국의 의료 시스템과 소매업체들이 BLE와 UWB를 결합한 하이브리드형 솔루션에 주력함에 따라 실내 도입이 급증하고 있습니다.
엣지 게이트웨이는 대역폭에 여유가 있을 때만 1초 미만의 실내 데이터를 클라우드 대시보드로 변환하여 GDPR의 데이터 최소화 원칙을 준수합니다. 금속이 밀집된 공장 내에서 진행된 도이치 텔레콤의 30cm UWB 파일럿 프로젝트는 Wi-Fi의 멀티패스 현상이 두드러지는 환경에서도 그 견고성이 입증되었습니다. 초광대역(UWB)은 고부가가치 산업용 사용 사례를 확보하고 있는 반면, BLE는 비용 효율성을 중시하는 소매 업계를 휩쓸고 있습니다. 이러한 요인들이 결합되어 대상 사용 사례가 확대되고, 실내 정확도가 향상됨에 따라 유럽의 위치 분석 시장이 더욱 강화되고 있습니다.
클라우드는 2025년 지출의 57.12%를 차지했으며, Azure, AWS, Fabric 내 API 번들링을 반영하여 연평균 성장률(CAGR) 16.1%를 기록할 것으로 전망됩니다. 마이크로소프트와 톰톰은 Azure 상의 Orbis Maps 제공을 2030년까지 연장하고, 라이선싱을 간소화하는 동시에 개발자들이 종량제 요금제를 채택하도록 장려하고 있습니다. HERE의 2024년 3분기 매출은 4억 2,800만 유로(4억 9,921만 달러)로 전년 대비 16% 증가하여 온프레미스 환경에서 클라우드로의 전환이 진행되고 있음을 뒷받침하고 있습니다. Microsoft Fabric은 OneLake에 공간 결합 기능을 추가하여, SQL 분석가가 GIS를 설치할 필요 없이 지오펜싱 쿼리를 실행할 수 있게 했습니다.
온프레미스는 국방, 은행, 중요 인프라 분야에서 여전히 필수적입니다. 유럽은행감독청(EBA)의 아웃소싱 지침은 금융 기관이 고객의 위치 정보를 프라이빗 클라우드에서 관리할 것을 권장하고 있습니다. Esri가 2025년 1월 TomTom과 제휴하여 데이터세트를 로컬에 보관한 채 ArcGIS에 클라우드 라우팅 기능을 통합한 것은 하이브리드 환경의 보급이 진행되고 있음을 보여줍니다. 하이퍼스케일러가 일상적인 공간 처리 업무를 흡수하는 가운데, 각 벤더들은 부가가치가 높은 트윈 시뮬레이션 및 AI 기반 인사이트 레이어로 사업을 전환하며, 유럽의 위치 분석 시장에서 차별화를 꾀하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the Europe location analytics market size was valued at USD 4.82 billion in 2025 and estimated to grow from USD 5.56 billion in 2026 to reach USD 11.34 billion by 2031, at a CAGR of 15.34% during the forecast period (2026-2031).
This report is Segmented by Location Type (Indoor, and Outdoor), Deployment (Cloud, and On-Premise), End User (Banking, Financial Services and Insurance, and More), Application (Customer Footfall Analytics, Asset Tracking, Risk and Incident Management, and More), and Geography (Germany, United Kingdom, and More). The Market Forecasts are Provided in Terms of Value (USD).
Europe Location Analytics Market Trends and Insights
Rising Adoption of Real-Time Fleet Management Solutions
Logistics carriers are embedding geospatial analytics into their telematics stacks to reduce empty-mile kilometers and meet the scope 3 requirements of the Corporate Sustainability Reporting Directive. DHL earmarked EUR 2 billion (USD 2.33 billion) for European EV fleets in 2024, pairing edge gateways with traffic, weather, and volume density feeds to reduce route variance by 12%. Maersk's predictive ETA engine cut hub dwell time 12% in H1 2024 by applying location AI to rail-port handoffs. DB Cargo has adopted automated geofencing, which reduces border crossings by 18 minutes per shipment, thereby accelerating customs clearance. Fleet software now bundles location analytics with predictive maintenance, tying elevation profiles and road quality to part-wear forecasts that pre-empt breakdowns.
Accelerated 5G Roll-Out Enabling Hyper-Local Analytics
Standalone 5G with network slicing guarantees sub-10 ms latency, unlocking augmented-reality navigation and autonomous warehouse forklifts. Vodafone Germany reached 90% population coverage by mid-2024, enabling private 5G networks employing centimeter-accurate indoor positioning. Orange France extended 5G to 75% of citizens by late-2024 to fuel real-time crowd-density heatmaps for retailers. EU Digital Decade aims for 75% 5G coverage by 2030, supporting millimeter-wave beamforming in airports and arenas. Deutsche Telekom and TRUMPF reached 30 cm accuracy in UWB-enabled factories, illustrating how 5G edge compute can localize work-in-progress inventory without relying on cloud cores.
Stringent GDPR Location-Consent Requirements
The European Data Protection Board clarified in 2024 that Wi-Fi and BLE MAC tracking counts as personal data, forcing retailers to deploy consent banners that sink opt-in rates 30-40% below opt-out regions. Germany's BSI urges on-device processing and differential privacy to curb cloud transfers. Belgium fined a beacon vendor EUR 250,000 (USD 291596.25) for lack of explicit consent, triggering sector-wide audits. Compliance costs hit SMEs hardest, steering contracts toward big-platform players with legal benches, yet also spur demand for on-premise deployments that avoid cross-border transfers flagged by the Schrems II ruling.
Other drivers and restraints analyzed in the detailed report include:
- Integration of Geospatial AI in Public-Safety Operations
- Mandates for Smart-City Open Data Portals
- De-Fragmented Local Government Procurement Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Indoor analytics posted a 15.52% CAGR forecast from 2026 to 2031, eclipsing outdoor systems that still held 63.61% of 2025 spend. Sub-USD 1 ambient-IoT tags from Wiliot and 10-cm angle-of-arrival UWB from Quuppa shrink hardware barriers and push the Europe location analytics market deeper into theaters, terminals, and wards. Enterprise buyers prize the batteryless form factor that eliminates monthly maintenance rounds, while hospitals cut equipment loss 18%. The Galileo High Accuracy Service and ubiquitous GPS keep outdoor analytics indispensable for transit and precision agriculture. Still, indoor adoption surges as national health systems and retailers converge on hybrid BLE-UWB blueprints.
Edge gateways translate sub-second indoor feeds to cloud dashboards only when bandwidth permits, honoring GDPR minimization. Deutsche Telekom's 30-cm UWB pilot inside metal-dense factories validates robustness where Wi-Fi multipath prevails. Ultra-wideband captures high-value industrial cases, while BLE dominates cost-sensitive retail. Collectively these factors multiply addressable use cases, reinforcing the Europe location analytics market as indoor accuracy climbs.
Cloud held 57.12% of the 2025 spend and is projected to have a 16.1% CAGR, reflecting API bundling within Azure, AWS, and Fabric. Microsoft and TomTom extended Orbis Maps in Azure through 2030, simplifying licensing and encouraging developers to adopt consumption-based billing. HERE's EUR 428 million(USD 499.21 million) Q3 2024 revenue, up 16%, underscores migration from on-premise estates. Microsoft Fabric has added spatial joins to OneLake, enabling SQL analysts to run geofencing queries without requiring GIS installations.
On-premise remains vital for defense, banking, and critical infrastructure. The European Banking Authority's outsourcing guide encourages financial institutions to maintain customer geolocation in private clouds. Esri's January 2025 link-up with TomTom channels cloud routing into ArcGIS, while datasets remain local, demonstrating hybrid traction. As hyperscalers swallow routine spatial operations, vendors pivot to value-added twin simulations and AI-driven insight layers, sustaining differentiation inside the Europe location analytics market.
Complete Report Scope:
- By Location Type
- Indoor
- Outdoor
- By Deployment
- Cloud
- On-Premise
- By End User
- Banking, Financial Services and Insurance (BFSI)
- Retail
- Transportation and Logistics
- Tourism and Hospitality
- Healthcare
- By Application
- Customer Footfall Analytics
- Asset Tracking
- Risk and Incident Management
- Marketing Campaign Optimization
- Urban Planning and Zoning
- By Country
- Germany
- United Kingdom
- France
- Rest of Europe
List of Companies Covered in this Report:
- Microsoft Corporation
- Esri Global, Inc.
- HERE Global B.V.
- Google LLC
- TomTom International B.V.
- SAS Institute Inc.
- Tableau Software LLC
- QlikTech International AB
- TIBCO Software Inc.
- Alteryx Inc.
- Hexagon AB
- Cisco Systems Inc.
- SAP SE
- Pitney Bowes Inc.
- Galigeo SAS
- Carto
- Foursquare
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Adoption of Real-Time Fleet Management Solutions
- 4.2.2 Accelerated 5G Roll-Out Enabling Hyper-Local Analytics
- 4.2.3 Integration of Geospatial AI in Public-Safety Operations
- 4.2.4 Mandates for Smart-City Open Data Portals
- 4.2.5 Growth of Digital-Twin Infrastructure Projects
- 4.2.6 Surge in Indoor IoT Sensor Fusion for Retail
- 4.3 Market Restraints
- 4.3.1 Stringent GDPR Location-Consent Requirements
- 4.3.2 De-Fragmented Local Government Procurement Cycles
- 4.3.3 Rising Cost of High-Resolution Satellite Imagery Licensing
- 4.3.4 Limited Availability of Qualified Geo-AI Talent
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Location Type
- 5.1.1 Indoor
- 5.1.2 Outdoor
- 5.2 By Deployment
- 5.2.1 Cloud
- 5.2.2 On-Premise
- 5.3 By End User
- 5.3.1 Banking, Financial Services and Insurance (BFSI)
- 5.3.2 Retail
- 5.3.3 Transportation and Logistics
- 5.3.4 Tourism and Hospitality
- 5.3.5 Healthcare
- 5.4 By Application
- 5.4.1 Customer Footfall Analytics
- 5.4.2 Asset Tracking
- 5.4.3 Risk and Incident Management
- 5.4.4 Marketing Campaign Optimization
- 5.4.5 Urban Planning and Zoning
- 5.5 By Country
- 5.5.1 Germany
- 5.5.2 United Kingdom
- 5.5.3 France
- 5.5.4 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Microsoft Corporation
- 6.4.2 Esri Global, Inc.
- 6.4.3 HERE Global B.V.
- 6.4.4 Google LLC
- 6.4.5 TomTom International B.V.
- 6.4.6 SAS Institute Inc.
- 6.4.7 Tableau Software LLC
- 6.4.8 QlikTech International AB
- 6.4.9 TIBCO Software Inc.
- 6.4.10 Alteryx Inc.
- 6.4.11 Hexagon AB
- 6.4.12 Cisco Systems Inc.
- 6.4.13 SAP SE
- 6.4.14 Pitney Bowes Inc.
- 6.4.15 Galigeo SAS
- 6.4.16 Carto
- 6.4.17 Foursquare
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


