

|
시장보고서
상품코드
2121505
아시아태평양 플라스틱 포장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Asia Pacific Plastic Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
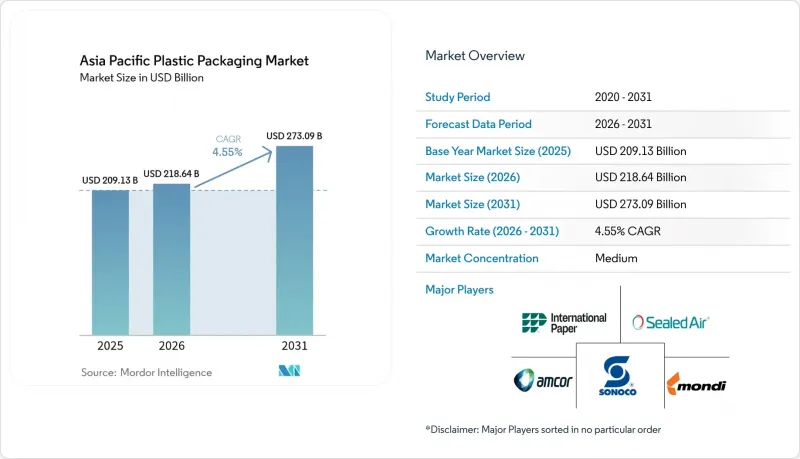
에 의하면, 아시아태평양 플라스틱 포장 시장 규모는 2025년 2,091억 3,000만 달러에서 2026년에는 2,186억 4,000만 달러에 이르고, 2026-2031년 CAGR 4.55%로 성장을 지속하여 2031년에는 2,730억 9,000만 달러에 달할 것으로 예측됩니다.
본 보고서는 소재 유형(폴리에틸렌, 폴리프로필렌 등), 포장 유형(연포장, 경질 포장), 제품 형태(병·항아리,트레이·용기 등), 최종 사용자 산업(식품, 음료, 의약품 및 헬스케어 등), 제조 공정(압출 성형 등), 국가별로 분류되어 있습니다. 시장 예측은 금액(미화) 기준으로 제시되어 있습니다.
아시아태평양 플라스틱 포장 시장 동향 및 인사이트
경량이며 파손에 강한 포장이 필요한 전자상거래의 급속한 성장
소포의 급증으로 인해, 각 컨버터 기업들은 운송 비용을 증가시키지 않으면서도 여러 취급 공정을 견딜 수 있는 포장을 설계해야 할 필요가 있습니다. 태국의 한 음료 제조업체는 2024년 풀필먼트 센터에서의 자동 분류를 원활하게 하기 위해 라벨이 없는 PET 병을 채택했습니다. 나노 클레이가 배합된 배리어 필름은 기존의 라미네이트 방식에 비해 30-50%의 경량화를 실현하여, 소재의 품질을 유지하면서 재료비를 절감합니다. 뛰어난 내충격성을 갖춘 특수 PE 및 PP 등급이 현재 전자기기 출하에서 주류를 이루고 있는 반면, 플랫폼 운영사는 검증된 압축 강도를 제공하는 공급업체를 우선시하는 엄격한 낙하 시험 기준을 공표하고 있습니다.
조직화된 소매업 및 편의점 식품의 확산
인도, 베트남, 인도네시아에서 현대식 소매업이 확대됨에 따라, 형광등 매장 조명에 맞추어 조정되고 상온 보관이 가능하며 미관이 뛰어난 패키지에 대한 수요가 증가하고 있습니다. SK그룹과 사밀제약의 베트남 제약 분야 투자는 정규 소매업이 포장 표준화를 어떻게 촉진하고 있는지를 보여줍니다. 고차단성 BOPP 및 메탈라이즈드 BOPET 필름이 호일을 대체하여 산소와 습기로부터의 보호를 보장하는 동시에 재활용성을 높이고 있습니다. 용량이 미리 조절된 유제품과 즉석식사는 콜드체인 대응 라미네이트 필름의 혜택을 받고 있으며, 대형 소매업체의 부상으로 인해 컨버터는 고정 비용을 더 많은 주문량에 분산시킬 수 있게 되었습니다.
격화되는 일회용 플라스틱 금지 조치와 EPR 요금
2026년에 도입될 싱가포르의 음료 용기 보증금 제도에서는 개당 0.10달러의 부과금이 부과되며, 이로 인해 포장 비용이 상승하고 소비자 수요는 리필 가능한 제품으로 이동하고 있습니다. 아세안(ASEAN) 국가마다 상이한 EPR 요금 체계로 인해 포장 디자인의 통일성이 어려워지고 있으며, 규제를 준수하는 기업들은 수지 대체 및 시험에 드는 비용 증가를 감당해야만 하여, 규제 대상이 아닌 경쟁사들에 비해 이익률이 압박받고 있습니다.
부문 분석
폴리에틸렌은 필름, 병, 캡 등 폭넓은 용도에서 비용 효율이 뛰어난 범용성을 발휘하여, 2025년에는 아시아태평양의 플라스틱 포장 시장에서 38.20%의 점유율을 차지했습니다. PET는 중국에서 연간 5만 톤의 rPET 생산을 목표로 하는 Wankai와 Carbios의 효소 분해 제휴 등에 힘입어 연평균 성장률(CAGR) 5.24%로 성장을 이어가고 있습니다. PET 핫필(hot-fill) 대응 병은 조미료 분야에서 유리병을 대체하며, 물류 안전성과 탄소 발자국 개선에 기여하고 있습니다. 폴리프로필렌은 높은 내열성이 요구되는 틈새 시장에서 입지를 유지하고 있는 반면, 생분해성 폴리머와 종이 라미네이트는 ISO 17088 인증을 획득함으로써 규제에 힘입어 프리미엄 시장 점유율을 확보하고 있습니다.
폴리에틸렌(PE)의 가격 경쟁력이 지속되고 있어 기존 생산 라인은 가동을 이어가고 있지만, EPR(확대 생산자 책임)에 힘입은 설계 전환과 ‘병에서 병으로(Bottle-to-Bottle)’ 인프라 덕분에 PET 단일 소재 순환 시스템이 우위를 점하고 있습니다. 산소 흡수 첨가제는 PET의 차단성을 향상시키며, 각 브랜드사의 재활용 소재 사용률에 대한 공약이 ‘텐더’ 방식의 조달을 촉진한 결과, 병 플레이크공급이 부족해지고 있습니다. PE 제조업체들은 향기에 민감한 상품을 보호하기 위해 금속 증착층을 배합한 고밀도 등급의 개발을 추진하고 있으며, 재활용성을 확보하면서도 PET와의 경쟁을 피하고 가격 경쟁력 면에서 대등함을 추구하고 있습니다.
2025년, 아시아태평양의 플라스틱 포장 시장 규모에서 연포장이 54.30%를 차지하며, 연평균 성장률(CAGR) 6.65%로 확대되고 있습니다. 이는 Huhtamaki India사의 ‘재활용 설계 지침’에 따라 가공업체들이 경량화를 도모하고, 단일 소재의 라미네이트 소재로의 전환을 추진하고 있기 때문입니다. 알루미늄 포일이나 PVC 첨가제를 배제함으로써 기계적 재활용 흐름이 촉진됩니다. 경질 용기는 치수 정밀도나 내충격성이 소재 사용의 이점을 능가하는 탄산음료나 퍼스널케어 제품의 펌프식 용기에서 여전히 필수적입니다.
소비자들의 ‘휴대용 스낵’ 및 ‘배달 음식’에 대한 선호도가 높아짐에 따라 스탠드업 파우치의 판매량은 증가하고 있습니다. 한편, 고밀도 폴리에틸렌(HDPE)으로 제작된 경질 병은 관리된 재사용 주기를 뒷받침하는 리필 스테이션에서 보급이 확대되고 있습니다. 각 브랜드 소유 기업들은 소비자를 수거 거점으로 유도하는 QR 코드가 탑재된 파우치의 시범 도입을 진행하며, 사용 후 재료 흐름에 관한 데이터 부족 문제를 해소하고 있습니다. 이와 병행하여 진행되고 있는 박리 기술에 대한 투자는 고부가가치 배리어 층의 회수를 목적으로 하며, 연포장재가 병의 재활용률에 필적할 수 있는 길을 열어주고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the Asia-Pacific plastic packaging market size is expected to grow from USD 209.13 billion in 2025 to USD 218.64 billion in 2026 and is forecast to reach USD 273.09 billion by 2031 at 4.55% CAGR over 2026-2031.
This report is Segmented by Material Type (Polyethylene, Polypropylene, and More), Packaging Type (Flexible, and Rigid), Product Form (Bottles and Jars, Trays and Containers, and More), End-User Industry (Food, Beverage, Pharmaceuticals and Healthcare, and More), Manufacturing Process (Extrusion, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Asia Pacific Plastic Packaging Market Trends and Insights
E-commerce boom demanding lightweight, damage-resistant packs
Rapid parcel growth obliges converters to engineer packaging that survives multiple handling points without inflating freight costs. Beverage producers in Thailand adopted label-free PET bottles during 2024 to facilitate automated sortation in fulfillment centers. Nanoclay-enhanced barrier films enable 30-50% weight reduction versus conventionally laminated formats, lowering material outlay while retaining integrity. Specialized PE and PP grades with superior impact resistance now dominate electronics shipments, whereas platform operators publish stringent drop-test standards that favor suppliers offering proven compression strength.
Growing organised retail and convenience-food penetration
Expansion of modern trade in India, Vietnam, and Indonesia lifts demand for shelf-stable, aesthetic packs calibrated for fluorescent store lighting. Vietnam's pharmaceutical investments by SK Group and Samil Pharmaceutical illustrate how formal retail elevates packaging standardization. High-barrier BOPP and metallized BOPET films replace foil, ensuring oxygen and moisture defense while improving recyclability. Portion-controlled dairy and ready meals benefit from cold-chain compatible laminates, and consolidated retailers enable converters to spread fixed costs across larger order volumes.
Escalating single-use-plastic bans and EPR fees
Singapore's beverage-container deposit scheme launching in 2026 imposes a USD 0.10 levy per unit, inflating pack costs and re-routing consumer demand toward refill options. Differing EPR fee structures across ASEAN complicate harmonized pack designs and spur compliant firms to absorb higher resin substitution and testing expenses, squeezing margins versus unregulated competitors.
Other drivers and restraints analyzed in the detailed report include:
- Shelf-life extension via advanced barrier films
- Sachet-to-refill transition programs in ASEAN
- Volatile crude-linked resin prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene held 38.20% Asia-Pacific plastic packaging market share in 2025 through cost-effective versatility across films, bottles, and closures. PET is marching at 5.24% CAGR, buoyed by enzymatic depolymerization partnerships such as Wankai-Carbios targeting 50,000 t/y rPET output in China. PET's hot-fill capable bottles displace glass in condiments, improving logistics safety and carbon footprints. Polypropylene sustains niches demanding high-heat tolerance, while biodegradable polymers and paper laminates secure premium, regulation-driven slots armed with ISO 17088 certifications.
Continued PE price competitiveness keeps legacy lines running, yet EPR-driven design shifts favor PET mono-material loops thanks to bottle-to-bottle infrastructure. Oxygen-scavenging additives enhance PET's barrier, and bottle flake supply closes as brand recycled-content pledges trigger Tender-based purchasing. PE producers explore high-density grades blended with metallized strip layers to protect aroma-sensitive goods, seeking parity with PET while safeguarding recyclability.
Flexible formats commanded 54.30% Asia-Pacific plastic packaging market size in 2025, scaling at 6.65% CAGR as converters strip weight and move toward mono-material laminates per Huhtamaki India's Design for Recycling Guidance. Eliminating aluminum foil and PVC additives unlocks mechanical recycling streams. Rigid containers remain essential for carbonated beverages and personal-care pumps where dimensional accuracy and impact resistance outweigh material-use advantage.
Consumer gravitation to on-the-go snacks and home-delivery meals boosts stand-up pouch volumes, while rigid HDPE bottles gain traction in refill stations supporting controlled reuse cycles. Brand owners pilot QR-enabled pouches that direct consumers to collection points, closing data gaps on post-use material flow. Parallel investment in delamination tech aims to salvage high-value barrier layers, offering flexible packs a path toward parity with bottle recycling rates.
Complete Report Scope:
- By Material Type
- Polyethylene (PE)
- Polypropylene (PP)
- Polyethylene Terephthalate (PET)
- Polystyrene and EPS
- Other Material Types
- By Packaging Type
- Flexible Plastic Packaging
- Rigid Plastic Packaging
- By Product Form
- Bottles and Jars
- Trays and Containers
- Pouches and Sachets
- Bags and Sacks
- Films and Wraps
- Other Product Forms
- By End-User Industry
- Food
- Beverage
- Pharmaceuticals and Healthcare
- Cosmetics and Personal Care
- Industrial
- Other End-user Industries
- By Manufacturing Process
- Extrusion
- Injection Molding
- Blow Molding
- Thermoforming
- By Country
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia Pacific
List of Companies Covered in this Report:
- Amcor plc
- Mondi plc
- Sonoco Products Company
- International Paper Company
- Sealed Air Corporation
- Huhtamaki Oyj
- ALPLA-Werke Alwin Lehner GmbH and Co KG
- Uflex Ltd.
- Plastipak Holdings Inc.
- Pactiv Evergreen Inc.
- Winpak Ltd.
- Toyo Seikan Group Holdings Ltd.
- Nihon Yamamura Glass Co., Ltd.
- Manjushree Technopack Ltd.
- Time Technoplast Ltd.
- Greif Inc.
- IFCO Systems GmbH
- Dynapack Asia Sdn Bhd
- Cheng Loong Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-commerce boom demanding lightweight, damage-resistant packs
- 4.2.2 Growing organised retail and convenience-food penetration
- 4.2.3 Shelf-life extension via advanced barrier films
- 4.2.4 Sachet-to-Refill" transition programmes in ASEAN
- 4.2.5 AI-enabled converting lines boosting small-lot customisation
- 4.2.6 Corporate green-bond funding tied to recycled-content KPIs
- 4.3 Market Restraints
- 4.3.1 Escalating single-use-plastic bans and EPR fees
- 4.3.2 Volatile crude-linked resin prices
- 4.3.3 PE and PP structural oversupply depressing converter margins
- 4.3.4 Traceability gaps limiting rPET food-grade uptake
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS(VALUE)
- 5.1 By Material Type
- 5.1.1 Polyethylene (PE)
- 5.1.2 Polypropylene (PP)
- 5.1.3 Polyethylene Terephthalate (PET)
- 5.1.4 Polystyrene and EPS
- 5.1.5 Other Material Types
- 5.2 By Packaging Type
- 5.2.1 Flexible Plastic Packaging
- 5.2.2 Rigid Plastic Packaging
- 5.3 By Product Form
- 5.3.1 Bottles and Jars
- 5.3.2 Trays and Containers
- 5.3.3 Pouches and Sachets
- 5.3.4 Bags and Sacks
- 5.3.5 Films and Wraps
- 5.3.6 Other Product Forms
- 5.4 By End-User Industry
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Pharmaceuticals and Healthcare
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Industrial
- 5.4.6 Other End-user Industries
- 5.5 By Manufacturing Process
- 5.5.1 Extrusion
- 5.5.2 Injection Molding
- 5.5.3 Blow Molding
- 5.5.4 Thermoforming
- 5.6 By Country
- 5.6.1 China
- 5.6.2 India
- 5.6.3 Japan
- 5.6.4 South Korea
- 5.6.5 Australia
- 5.6.6 Rest of Asia Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Investments
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Mondi plc
- 6.4.3 Sonoco Products Company
- 6.4.4 International Paper Company
- 6.4.5 Sealed Air Corporation
- 6.4.6 Huhtamaki Oyj
- 6.4.7 ALPLA-Werke Alwin Lehner GmbH and Co KG
- 6.4.8 Uflex Ltd.
- 6.4.9 Plastipak Holdings Inc.
- 6.4.10 Pactiv Evergreen Inc.
- 6.4.11 Winpak Ltd.
- 6.4.12 Toyo Seikan Group Holdings Ltd.
- 6.4.13 Nihon Yamamura Glass Co., Ltd.
- 6.4.14 Manjushree Technopack Ltd.
- 6.4.15 Time Technoplast Ltd.
- 6.4.16 Greif Inc.
- 6.4.17 IFCO Systems GmbH
- 6.4.18 Dynapack Asia Sdn Bhd
- 6.4.19 Cheng Loong Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


