

|
시장보고서
상품코드
2121541
중국의 압력 센서 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)China Pressure Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
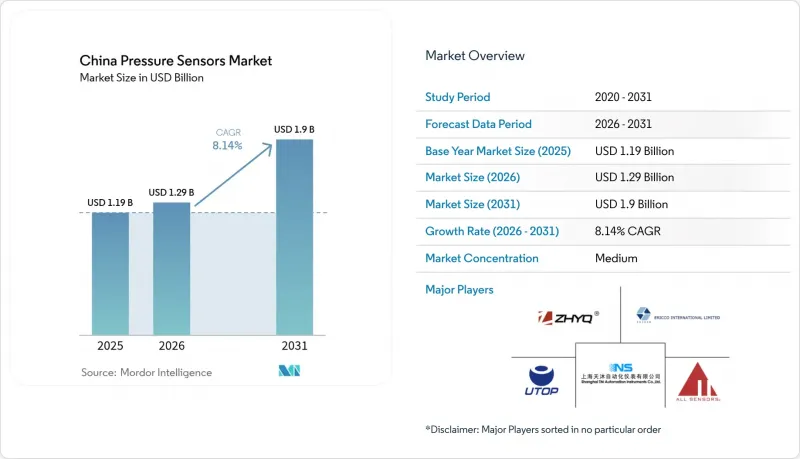
에 의하면, 중국의 압력 센서 시장 규모는 2025년에 11억 9,000만 달러로 평가되었고, 2026년 12억 9,000만 달러에서 2031년까지 19억 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 8.14%를 기록할 전망입니다.
본 보고서는 제품 유형(MEMS, 정전용량식, 압전식 등), 압력 측정 방식(게이지 압력, 절대 압력, 차압, 진공 압력, 밀폐 기준 압력), 최종 사용자 산업(자동차, 항공우주 및 방위, 화학제품 및 석유화학제품,의료기기 등), 기술 플랫폼(압전 저항식, 정전용량식 MEMS 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
중국의 압력 센서 시장 동향 및 인사이트
전기차에 MEMS 기반 소형 센서 채택 가속화
중국이 전기차 분야에서 주도적인 위치를 차지함에 따라, 자동차 규격에 부합하는 소형 압력 센서에 대한 수요가 전례 없는 규모로 확대되고 있습니다. 국내 제조 공장에서는 현재 연간 수백만 개의 MEMS 유닛을 생산하고 있으며, 이를 통해 수입 의존도가 낮아지고 공급 안정성이 확보되고 있습니다. 각 전기차에는 열 관리, 브레이크, ADAS(첨단 운전자 지원 시스템) 기능을 위해 15-20개의 센서가 탑재되어 있으며, 자율 주행과 전동화의 융합으로 차량당 센서 탑재 수는 더욱 증가하고 있습니다. 견고한 설계로 -40°C-150°C의 온도 변동과 격렬한 진동을 견디며, AEC-Q103의 신뢰성 요건을 충족하고 있습니다. 배터리 팩의 급속한 기술 혁신으로 인해, 안전성을 확보하기 위해 셀 압력을 모니터링하는 고정밀 차동 센서에 대한 수요가 더욱 높아지고 있습니다. 자동차 제조업체들이 부품 조달을 현지화하는 가운데, 가격과 성능의 균형 측면에서 전 세계 사양을 충족하면서도 총비용이 낮은 국산 MEMS가 유리한 입지를 점하고 있습니다.
국내 반도체 자급자족 및 센서 현지화를 위한 정부의 인센티브
국가 및 성 차원의 각 프로그램에서는 센서 제조 공장 및 연구개발 센터를 대상으로 막대한 보조금, 세제 혜택, 저리 융자가 배정되고 있습니다. 우시 하이테크 구만 해도 2024년에 4개의 압력 센서 관련 스타트업 기업에 수억 위안을 조달하여 클린룸 확장 및 후공정 패키징 라인에 자금을 지원했습니다. 현재 센서 파일럿 라인은 공유 계측 실험실의 혜택을 받고 있어 중소기업의 진입 장벽이 낮아졌습니다. ‘제14차 5개년 계획’에서는 핵심 공정 장비를 우선 과제로 삼고 있으며, 2030년까지 국산화율을 70% 이상으로 끌어올리는 것을 목표로 하고 있습니다. 슝안(雄安)이나 선전(深?)의 전략적 클러스터에서는 인허가 절차의 신속화, 토지 가격 할인, 노동력에 대한 보조금 등이 제공되어, 인증을 받은 장치 시장 출시까지 걸리는 기간을 단축하고 있습니다.
실리콘 웨이퍼 및 희토류 재료 가격 변동
세계 웨이퍼 제조 공장의 사이클에 따라 가격은 급격하게 변동하고 있습니다. 2024년 실리콘 현물 가격은 38% 상승한 후, 4분기 후반에 하락세를 보였습니다. 희토류 가공 분야에서 중국의 지배력은 추가적인 불확실성을 초래하고 있습니다. 수출 할당량 조정과 지정학적 긴장이 Nd 및 Pr을 주성분으로 하는 화합물의 가격에 영향을 미치고 있기 때문입니다. 각 제조업체는 여러 공급처로부터의 조달 및 안전 재고 확충을 통해 리스크 헤지를 실시하고 있으며, 그 결과 운전 자금이 묶여 매출 총이익률에 압박이 가해지고 있습니다. 대규모 제조업체들은 선물 계약을 활용하고 있지만, 소규모 제조업체들은 수주 대비 출하 비율이 압박을 받고 있어 생산 능력 확충이 지연되고 있습니다. 재활용 프로그램의 가속화로 인해 2026년 이후에는 공급망 리스크가 일부 완화될 가능성이 있습니다.
부문 분석
2025년 중국의 압력 센서 시장에서 MEMS 디바이스는 42.35%의 점유율을 차지하고 있으며, 이 부문은 2031년까지 연평균 성장률(CAGR) 9.34%를 나타낼 것으로 예측됩니다. 8인치 CMOS 라인에서 제조되는 MEMS 다이는 성숙한 제조 설비를 활용하여 높은 수율과 낮은 단가를 실현하고 있습니다. ADC와 온도 보정 로직을 동시에 집적화함으로써 플러그 앤 플레이(plug-and-play) 지원 모듈을 구현하여, 업종을 불문하고 드롭인(drop-in) 교체가 가능해집니다. 정전용량식 센서는 뛰어난 과부하 내성으로 인해 산업용 공압 기기에서 확고한 지지 기반을 유지하고 있는 반면, 압전식 센서는 항공우주 분야의 진동 요건을 충족하고 있습니다. 스트레인 게이지식 센서는 견고한 기계적 결합이 필요한 중장비에 활용되고 있습니다. 광학식 압력 센서는 발전소의 개폐소 등 전자기 간섭(EMI)이 강한 영역에서 좁은 틈새 시장을 차지하고 있습니다. MEMS 코어와 BLE 또는 Wi-Fi 마이크로컨트롤러를 결합한 하이브리드 스마트 모듈은 단일 매개변수 측정에서 종합적인 상태 모니터링으로의 진화를 보여주고 있습니다.
중국 내 MEMS 설계 압력 센서 시장 규모는 소형화, 저전력 소비, 고속 응답이 융합된 자동차 및 의료 분야의 시너지 효과로 인해 성장하고 있습니다. 국내 IDM 기업들은 스마트 워치 및 웨어러블 기기용 Z축 높이를 줄이기 위해 웨이퍼 레벨 칩 스케일 패키징(WLCSP)에 투자하고 있습니다. ASIC 설계 기업과의 전략적 제휴를 통해 BOM 비용이 절감되고 경쟁 주기가 가속화되고 있습니다. 2027년 이후, 팹이 12인치 MEMS용 장비 인증을 진행함에 따라 웨이퍼당 다이 생산량은 증가하고, 비용 곡선은 더욱 낮아져 가격에 민감한 가전제품으로의 채택이 확대될 전망입니다.
2025년에는 에어 브레이크, HVAC, 유압 회로용으로 공급되는 게이지형이 매출의 48.25%를 차지하며 중국의 압력 센서 시장을 주도했습니다. 그러나 유량 계측, 필터 모니터링, 스마트 빌딩의 VAV 제어에 힘입어 차압형 디바이스가 9.68%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 진공형 및 밀폐형 레퍼런스 장치는 10 mTorr 미만의 절대 정밀도가 필수적인 반도체 제조 장비 및 실험실용 계측 기기에 공급되고 있습니다. 무선 차압 모듈은 1µA의 절전 모드 전류로 서브파스칼 단위의 분해능을 실현하여, 배터리 구동 방식의 개조 프로젝트에 적합합니다.
중국 내 차압형 압력 센서 시장의 확대는 디지털 유전 프로그램의 확대와 고층 빌딩의 에너지 감사 증가를 반영하고 있습니다. 건축 기준에 따라 건물의 기밀성 관련 기준이 엄격해짐에 따라 기류 균형 조정이 의무화되면서 층당 센서 장착률이 상승하고 있습니다. 각 제조업체는 SOI(Silicon-on-Insulator) 다이어프램과 독자적인 미세 다공성 기준 공동을 채택하여 장기 안정성을 향상시키고, 드리프트를 연간 0.1% 미만으로 억제하고 있습니다. 생명공학 플랜트에서 등장하고 있는 마이크로플루이딕스식 투여 라인에서는 투여 정밀도를 확보하기 위해 밀리바르 범위의 차압 감지가 채택되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the China pressure sensors market size was valued at USD 1.19 billion in 2025 and estimated to grow from USD 1.29 billion in 2026 to reach USD 1.9 billion by 2031, at a CAGR of 8.14% during the forecast period (2026-2031).
This report is Segmented by Product Type (MEMS, Capacitive, Piezoelectric, and More), Pressure Measurement (Gauge, Absolute, Differential, Vacuum, and Sealed Reference), End-User Industry (Automotive, Aerospace and Defense, Chemical and Petrochemical, Medical Devices, and More), Technology Platform (Piezoresistive, Capacitive MEMS, and More). The Market Forecasts are Provided in Terms of Value (USD).
China Pressure Sensors Market Trends and Insights
Accelerating Adoption of MEMS-Based Miniaturized Sensors in Electric Vehicles
China's electric-vehicle leadership pushes unprecedented volumes for compact, automotive-qualified pressure sensors. Domestic fabs now deliver millions of MEMS units annually, lowering import dependence and ensuring supply resilience. Each EV integrates 15-20 sensing points for thermal management, braking, and ADAS functions, and the convergence of autonomy with electrification multiplies sensor content per car. Robust designs withstand -40 °C to 150 °C temperature swings and high vibration, meeting AEC-Q103 reliability demands. Rapid battery-pack innovation further fuels demand for high-accuracy differential sensors that monitor cell pressure for safety. As automakers localize component sourcing, price-performance dynamics favor homegrown MEMS that match global specifications at lower landed cost.
Government Incentives for Domestic Semiconductor Self-Sufficiency and Sensor Localization
National and provincial programs earmark substantial grants, tax incentives, and low-interest loans for sensor fabs and R&D centers. Wuxi High-tech Zone alone raised several hundred million RMB for four pressure-sensor start-ups in 2024, funding cleanroom expansion and backend packaging lines. Sensor pilot lines now benefit from shared metrology labs, lowering entry barriers for small firms. The 14th Five-Year Plan prioritizes core process equipment, aiming to lift domestic content above 70% by 2030. Strategic clusters in Xiong'an and Shenzhen offer expedited permitting, discounted land, and workforce subsidies, accelerating time-to-market for qualified devices.
Volatility in Silicon-Wafer and Rare-Earth Material Prices
Global wafer-fab cycles create sharp price swings; 2024 spot silicon rose 38% before softening in late Q4. China's dominance in rare-earth processing introduces additional uncertainty, as export-quota adjustments and geopolitical tensions influence Nd- and Pr-based compound pricing. Manufacturers hedge by multi-sourcing and holding higher safety stocks, tying up working capital and pressuring gross margins. Larger fabs leverage forward contracts, but smaller houses face squeezed book-to-bill ratios, delaying capacity upgrades. Accelerated recycling programs may partly ease supply-chain risk after 2026.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Industry 4.0 Smart Manufacturing Across Chinese Industrial Parks
- Rising Demand for High-Precision Medical Devices and Wearable Health Monitoring
- High Reliability-Certification Barriers for Automotive-Grade Sensors
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
MEMS devices accounted for 42.35% of the China pressure sensors market share in 2025, and this category is projected to grow at a 9.34% CAGR to 2031. MEMS dies fabricated on 8-inch CMOS lines leverage mature tooling, delivering high yield and low unit cost. Simultaneous integration of ADCs and temperature compensation logic enables plug-and-play modules, supporting drop-in replacement across industries. Capacitive sensors maintain a loyal base in industrial pneumatics thanks to superior overload tolerance, whereas piezoelectric variants meet aerospace vibration needs. Strain-gauge sensors serve heavy machinery requiring rugged mechanical bonding. Optical pressure sensors occupy small niches in high-EMI zones such as power-generation switchyards. Hybrid smart modules that pair MEMS cores with BLE or Wi-Fi microcontrollers illustrate an evolution from single-parameter measurement toward holistic condition monitoring.
The China pressure sensors market size for MEMS designs benefits from automotive and medical synergies, where miniaturization, low power, and fast response converge. Domestic IDMs invest in wafer-level chip-scale packaging to shrink Z-height for smartwatches and hearables. Strategic partnerships with ASIC design houses reduce BOM cost, quickening competitive cycles. As fabs qualify 12-inch MEMS tooling after 2027, die output per wafer will rise, further lowering cost curves and widening adoption into price-sensitive appliances.
Gauge variants led the China pressure sensors market with 48.25% revenue in 2025, serving air-brake, HVAC, and hydraulic circuits. However, differential devices will record the highest 9.68% CAGR, propelled by flow metering, filter monitoring, and smart-building VAV control. Vacuum and sealed-reference devices supply semiconductor tools and laboratory instrumentation where absolute accuracy below 10 mTorr is mandatory. Wireless differential modules achieve sub-Pascal resolution at 1 µA sleep currents, aligning with battery-powered retrofit projects.
China pressure sensors market size gains in differential configurations mirror expanding digital oilfield programs and high-rise energy audits. As construction codes tighten envelope-leakage limits, air-flow balancing becomes mandatory, lifting sensor attach rates per floor. Manufacturers improve long-term stability via silicon-on-insulator diaphragms and proprietary micro-porous reference cavities, curbing drift below 0.1% per year. Emerging micro-fluidic dosing lines in biotech plants adopt millibar-range differential sensing to assure dosing accuracy.
Complete Report Scope:
- By Product Type
- MEMS Pressure Sensors
- Capacitive Pressure Sensors
- Piezoelectric Pressure Sensors
- Strain Gauge Pressure Sensors
- Optical Pressure Sensors
- Other Product Types
- By Pressure Measurement
- Gauge Pressure Sensors
- Absolute Pressure Sensors
- Differential Pressure Sensors
- Vacuum Pressure Sensors
- Sealed Reference Pressure Sensors
- By End-user Industry
- Automotive
- Aerospace and Defense
- Chemical and Petrochemical
- Medical Devices
- HVAC and Building Automation
- Power Generation
- Industrial Manufacturing
- Oil and Gas
- Consumer Electronics
- Other Industries
- By Technology Platform
- Piezoresistive
- Capacitive MEMS
- Optical Fiber
- Resonant Solid State
- Electromagnetic
- Nano and Flexible
List of Companies Covered in this Report:
- Honeywell International Inc.
- Robert Bosch GmbH
- Infineon Technologies AG
- TE Connectivity Ltd.
- Siemens Aktiengesellschaft
- Emerson Electric Co.
- ABB Ltd.
- Sensata Technologies Holding plc
- Panasonic Holdings Corporation
- STMicroelectronics N.V.
- NXP Semiconductors N.V.
- First Sensor AG
- All Sensors Corporation
- Shanghai Zhaohui Pressure Apparatus Co., Ltd.
- Ericco International Limited
- Xi'an UTOP Measurement Instrument Co., Ltd.
- TM Automation Instruments Co., Ltd.
- Ninghai Sendo Sensor Co., Ltd.
- Suzhou Memsensor Technology Co., Ltd.
- Hunan Firstrate Sensor Co., Ltd.
- Jiangsu Hanwei Electronics Co., Ltd.
- WIKA Alexander Wiegand SE and Co. KG
- Keller Druckmesstechnik AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating adoption of MEMS-based miniaturized sensors in electric vehicles
- 4.2.2 Government incentives for domestic semiconductor self-sufficiency and sensor localization
- 4.2.3 Expansion of Industry 4.0 smart manufacturing across Chinese industrial parks
- 4.2.4 Rising demand for high-precision medical devices and wearable health monitoring
- 4.2.5 HVAC and smart-building retrofits boosting demand for wireless pressure sensors
- 4.2.6 Digital oil and gas field development requiring harsh-environment pressure sensing
- 4.3 Market Restraints
- 4.3.1 Volatility in silicon-wafer and rare-earth material prices
- 4.3.2 High reliability-certification barriers for automotive-grade sensors
- 4.3.3 Intellectual-property disputes limiting export opportunities
- 4.3.4 Short product lifecycles causing rapid obsolescence for consumer-grade sensors
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 MEMS Pressure Sensors
- 5.1.2 Capacitive Pressure Sensors
- 5.1.3 Piezoelectric Pressure Sensors
- 5.1.4 Strain Gauge Pressure Sensors
- 5.1.5 Optical Pressure Sensors
- 5.1.6 Other Product Types
- 5.2 By Pressure Measurement
- 5.2.1 Gauge Pressure Sensors
- 5.2.2 Absolute Pressure Sensors
- 5.2.3 Differential Pressure Sensors
- 5.2.4 Vacuum Pressure Sensors
- 5.2.5 Sealed Reference Pressure Sensors
- 5.3 By End-user Industry
- 5.3.1 Automotive
- 5.3.2 Aerospace and Defense
- 5.3.3 Chemical and Petrochemical
- 5.3.4 Medical Devices
- 5.3.5 HVAC and Building Automation
- 5.3.6 Power Generation
- 5.3.7 Industrial Manufacturing
- 5.3.8 Oil and Gas
- 5.3.9 Consumer Electronics
- 5.3.10 Other Industries
- 5.4 By Technology Platform
- 5.4.1 Piezoresistive
- 5.4.2 Capacitive MEMS
- 5.4.3 Optical Fiber
- 5.4.4 Resonant Solid State
- 5.4.5 Electromagnetic
- 5.4.6 Nano and Flexible
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Honeywell International Inc.
- 6.4.2 Robert Bosch GmbH
- 6.4.3 Infineon Technologies AG
- 6.4.4 TE Connectivity Ltd.
- 6.4.5 Siemens Aktiengesellschaft
- 6.4.6 Emerson Electric Co.
- 6.4.7 ABB Ltd.
- 6.4.8 Sensata Technologies Holding plc
- 6.4.9 Panasonic Holdings Corporation
- 6.4.10 STMicroelectronics N.V.
- 6.4.11 NXP Semiconductors N.V.
- 6.4.12 First Sensor AG
- 6.4.13 All Sensors Corporation
- 6.4.14 Shanghai Zhaohui Pressure Apparatus Co., Ltd.
- 6.4.15 Ericco International Limited
- 6.4.16 Xi'an UTOP Measurement Instrument Co., Ltd.
- 6.4.17 TM Automation Instruments Co., Ltd.
- 6.4.18 Ninghai Sendo Sensor Co., Ltd.
- 6.4.19 Suzhou Memsensor Technology Co., Ltd.
- 6.4.20 Hunan Firstrate Sensor Co., Ltd.
- 6.4.21 Jiangsu Hanwei Electronics Co., Ltd.
- 6.4.22 WIKA Alexander Wiegand SE and Co. KG
- 6.4.23 Keller Druckmesstechnik AG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


