|
시장보고서
상품코드
2121556
생검 기기 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Biopsy Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
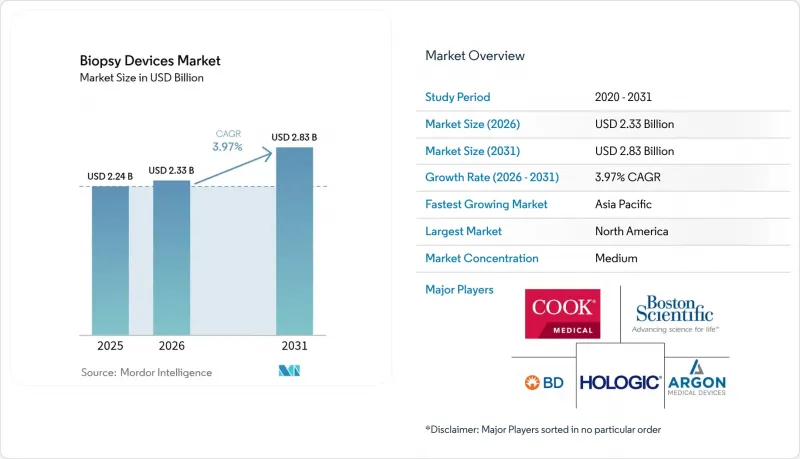
에 의하면, 2026년 생검 기기 시장 규모는 23억 3,000만 달러로 추정되며, 2025년 22억 4,000만 달러에서 2031년에는 28억 3,000만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 3.97%를 기록할 전망입니다.
본 보고서는 제품별(바늘을 이용한 생검 기구(코어 생검 기기 등), 시술 트레이 등), 용도별(유방 생검, 폐 생검,대장 생검, 전립선 생검 등), 최종 사용자(병원, 진단·영상진단센터 등), 지역(북미, 유럽, 아시아태평양 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 생검 기기 시장 동향 및 인사이트
저침습 암 진단에 대한 수요 증가
킹스 칼리지 런던에서 개발된 나노니들 패치는 사람의 머리카락 1,000분의 1 굵기의 미세 바늘 수백만 개를 삽입하여 통증 없는 조직 채취를 가능하게 하고, 조직을 손상시키지 않으면서 실시간 모니터링을 실현하고 있습니다. 또한, 공압 구동 로봇 카테터 기술의 병행된 발전으로 인해 구불구불한 관강 내 장기 내에서 6방향으로 시료 채취가 가능해져, 시술 시간 단축과 환자의 편의성 향상이 도모되고 있습니다. 그 결과, 의료 기관에서는 합병증을 최소화하고 고품질의 검체를 채취할 수 있는 저침습 기기가 점점 더 선호되고 있으며, 이것이 전 세계 생검 기기 시장의 주요 성장 동력이 되고 있습니다. 의료 시스템 구매 담당자들도 회복 기간 단축 및 재시술 감소로 인한 후속 비용 절감에 주목하고 있으며, 이것이 도입을 뒷받침하고 있습니다. 이러한 기술이 성숙해짐에 따라, 로봇 구동과 마이크로 샘플링을 통합한 일관된 플랫폼을 제공하는 공급업체들이 경쟁 우위를 확보하고 있습니다.
접근이 어려운 장기의 암 발병률 증가
폐암은 여전히 전 세계 암 사망 원인 1위를 차지하고 있으며, 2024년에는 전 세계 암 사망자의 18.7%를 차지할 것으로 예측됩니다. 폐, 췌장, 뇌에 대한 접근의 해부학적 장벽으로 인해 정밀 바늘, 조작 가능한 카테터 시스템 및 첨단 영상 진단용 액세서리에 대한 수요가 증가하고 있습니다. 고소득 국가에서 가장 큰 질병 부담이 보고되고 있지만, 신흥 시장에서는 동등한 진단 능력이 없음에도 불구하고 발병률이 급속히 증가하고 있습니다. 이에 따라 병원에서는 생검의 정확도를 높이고 마취 시간을 단축하는 영상 유도식 코어 샘플링 장치 및 진공 보조 장치로의 교체가 진행되고 있습니다. 이는 보상 제도가 엄격해지더라도 생검 기기 시장을 지속적으로 지탱해 주는 투자 패턴이 되고 있습니다.
의료기기 리콜 및 멸균 미비로 인한 사고
올림푸스는 선단부가 분리되어 26건의 중대한 상해가 발생한 것을 계기로 일회용 폐 생검용 시스를 회수했으며, 병원들은 재고를 격리하고 시술 일정을 재조정할 수밖에 없게 되었습니다. 홀로직(Hologic)사는 통증, 감염 및 마커 이동이 보고됨에 따라 5만 3,492개의 BioZorb 마커에 대해 클래스 I 리콜을 실시했습니다. 카디널 헬스(Cardinal Health)사도 마찬가지로 무균성에 대한 우려로 생검 관련 수술 키트를 회수했습니다. 이러한 사건들은 규제 당국의 감시를 강화하고, 비용이 많이 드는 시정 조치를 강요하며, 임상의들의 신뢰를 훼손할 가능성이 있어, 결과적으로 생검용 의료기기 시장의 단기적인 성장을 억제하게 될 것입니다.
부문 분석
바늘을 사용하는 기기는 2025년에 9억 9,000만 달러의 매출을 창출할 것으로 예상되며, 이는 생검 기기 시장 규모의 44.20%에 해당하며, 2031년까지 연평균 성장률(CAGR) 8.12%를 나타낼 것으로 전망됩니다. 코어형 및 진공 보조형 모델에는 전자기 추적 기능과 AI 분석 기능이 통합되어 있어, 의심스러운 조직을 실시간으로 식별함으로써 경험이 부족한 시술자의 숙련 기간을 단축합니다. Elucent Medical사의 ‘EnVisio X1’은 광학 내비게이션과 고주파 가이드를 통한 깊이 제어를 결합하여 FDA의 획기적 기술(Breakthrough) 지정을 획득했습니다. 이는 정밀한 표적 위치 결정에 대한 투자 경쟁이 치열함을 여실히 보여줍니다. 이와 병행하여, 일회용 바늘 카트리지는 감염 관리 요건을 충족하고 외래 수술실의 회전율을 향상시켜, 생검 기기 시장이 비응급 의료 현장으로의 확산을 촉진하고 있습니다.
시술용 트레이는 표준화된 키트가 설정을 효율화하고 사례당 비용을 절감하기 때문에 꾸준한 성장을 보이고 있습니다. 이는 종합적 지불 모델을 채택한 외래 시설에 있어 높이 평가되는 이점입니다. 위치 확인용 와이어는 여전히 유방 관리의 주류이지만, 용해형이나 저에너지 레이더 신호를 발산하는 새로운 클립형 마커는 환자의 편안함을 향상시키고 회수 절차를 생략함으로써 점차 와이어 수요를 잠식하고 있습니다. 캐뉼라, 오블레이터, 진공 튜브 등의 보조 액세서리에는 로트 추적을 자동화하고 리콜 관리를 간소화하는 RFID 태그가 탑재되기 시작했으며, 이는 최근의 멸균 불량 문제에 대한 대응책이 되고 있습니다.
지역별 분석
북미는 충실한 보험 적용 범위, 기술 지향적인 임상의, 그리고 명확하게 정의된 환급 경로를 바탕으로 2025년 매출의 41.25%를 차지하며, 세계 생검 기기 시장에서 이 지역의 주도적인 위상을 확고히 하고 있습니다. AI를 활용한 OCT, 로봇 보조 기관지 내시경 검사, 초박형 플렉서블 바늘 등으로 대표되는 지속적인 혁신을 통해 의료기기의 안정적인 업데이트 주기가 확보되고 있습니다. 그러나 병원들은 진료 패키지에 대해 보험사로부터 엄격한 감시를 받고 있으며, 이로 인해 의료 기관들은 비용 대비 효과가 높은 일회용 제품이나 불필요한 검체 채취를 줄이는 예측 분석 도입으로 방향을 전환하고 있습니다.
유럽에서는 각국의 의료 제도가 가치 기반 조달 및 맞춤형 의료를 중시하고 있어, 완만하지만 안정적인 성장이 나타나고 있습니다. 마진 평가에 도움이 되는 마커와 표적 치료의 지침이 되는 분자 검사의 도입이 두드러지며, 이로 인해 EU 내 고품질 조직 채취에 대한 수요가 촉진되고 있습니다. ‘의료기기 규정(MDR)’에 따른 규제 조화로 인해 승인까지의 기간은 길어졌지만, 명확한 임상적 유효성 입증이 이러한 행정적 부담을 상쇄하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 8.25%를 나타낼 것으로 예측되며, 생검 기기 시장에서 단연 가장 빠른 성장 속도를 보이고 있습니다. 인도의 6,120억 달러 규모 의료 부문 확대, 중국의 2급 암 센터 확대, 그리고 동남아시아의 민간 병원 급증으로 인해 대상 설치 기반이 확대되고 있습니다. 각국 정부는 동시에 폐암, 대장암, 자궁경부암 검진 정책을 전개하고 있으며, 이는 검사 건수 증가로 이어지고 있습니다. 국내 제조업체들도 부상하고 있지만, 진공식 및 영상 유도 시스템 분야에서는 미국, 일본, 유럽의 프리미엄 브랜드가 여전히 기술적 리더십을 유지하고 있습니다.
중동 및 아프리카, 남미는 시장 점유율은 작지만, 민관 파트너십을 통해 암 치료 거점에 자금이 지원되는 지역에서는 국지적인 수요 급증이 나타나고 있습니다. 걸프 국가에서는 대규모 전문 병원이 종합 암 치료 캠퍼스와 연계된 최고 수준의 생검 시설을 도입하고 있습니다. 브라질과 멕시코에서는 보험 환급 제도 개혁에 따라 민간 보험사가 첨단 생검 기술을 보험 적용 대상에 포함하도록 장려되고 있어 환자층이 점차 확대되고 있습니다. 공급망상의 과제와 규제 감독의 불균일성이 당장의 이익을 억제하고 있지만, 다국적 기업들은 미래 성장을 이끌어내기 위해 현지 조립 및 유통 제휴를 통해 시장 내 입지를 확고히 다지고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, biopsy devices market size in 2026 is estimated at USD 2.33 billion, growing from 2025 value of USD 2.24 billion with 2031 projections showing USD 2.83 billion, growing at 3.97% CAGR over 2026-2031.
This report is Segmented by Product (Needle-Based Biopsy Instruments [Core Biopsy Devices, and More], Procedure Trays, and More), Application (Breast Biopsy, Lung Biopsy, Colorectal Biopsy, Prostate Biopsy, and More), End-User (Hospitals, Diagnostic & Imaging Centers, and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Biopsy Devices Market Trends and Insights
Rising Demand For Minimally Invasive Cancer Diagnostics
Nanoneedle patches developed at King's College London allow painless tissue sampling by inserting millions of micro-needles that are 1,000 times thinner than human hair, enabling real-time monitoring without tissue damage. Parallel advances in pneumatically driven robotic catheters achieve six-direction sampling inside tortuous luminal organs, cutting procedure time and improving patient comfort. Clinics therefore increasingly favor less invasive hardware that minimizes complications and yields high-quality specimens, a key catalyst for the biopsy devices market worldwide. Health-system purchasers also note lower downstream costs from shorter recovery times and fewer repeat procedures, reinforcing adoption. As these technologies mature, suppliers that integrate robotic actuation and micro-sampling into cohesive platforms are gaining a competitive edge.
Growing Incidence Of Hard-To-Reach Organ Cancers
Lung cancer remains the world's top cause of cancer mortality, representing 18.7% of global cancer deaths in 2024. The anatomical obstacles of accessing lungs, pancreas, and brain heighten demand for precision needles, steerable catheter systems, and advanced imaging accessories. High-income nations report the greatest disease burden, yet emerging markets are witnessing rapid incidence growth without equivalent diagnostic capacity. Hospitals are therefore upgrading to image-guided core and vacuum-assisted devices that improve sampling accuracy and shorten anesthesia time-an investment pattern that sustains the biopsy devices market even as reimbursement regimes tighten.
Device Recalls & Sterility-Failure Events
Olympus withdrew single-use lung-biopsy sheaths after detachable tips caused 26 serious injuries, compelling hospitals to quarantine stock and reschedule procedures. Hologic's Class I recall of 53,492 BioZorb markers followed reports of pain, infection, and migration. Cardinal Health likewise pulled biopsy-related procedure kits over sterility concerns. Such events intensify regulatory scrutiny, force costly remediation programs, and can dampen clinician confidence, thereby restraining near-term growth for the biopsy devices market.
Other drivers and restraints analyzed in the detailed report include:
- AI-Enabled Image Guidance Improves First-Pass Yield
- Expansion Of Government-Funded Screening Programs
- Competition From Liquid-Biopsy Technologies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Needle-based instruments generated USD 0.99 billion of revenue in 2025, equal to 44.20% of the biopsy devices market size, and they are forecast to clock an 8.12% CAGR through 2031. Core and vacuum-assisted models integrate electromagnetic tracking and AI analytics that highlight suspicious tissue in real time, cutting the learning curve for less-experienced operators. Elucent Medical's EnVisio X1 earned FDA breakthrough status for combining optical navigation with radiofrequency-guided depth control, underscoring the investment arms race around precision targeting. In parallel, disposable needle cartridges align with infection-control mandates and accelerate turnover in ambulatory theatres, helping the biopsy devices market penetrate lower-acuity settings.
Procedure trays register steady gains because standardized kits streamline set-up and lower costs per case, an advantage prized by outpatient facilities under bundled-payment models. Localization wires remain a breast-care staple, yet newer clip-based markers that dissolve or emit low-energy radar signals are gradually cannibalizing demand by improving patient comfort and eliminating retrieval steps. Supporting accessories such as cannulas, obturators, and vacuum tubing now feature RFID tags that automate lot tracking and simplify recall management, a response to recent sterility failures.
Complete Report Scope:
- By Product
- Needle-based Biopsy Instruments
- Core Biopsy Devices
- Aspiration Biopsy Needles
- Vacuum-Assisted Biopsy Devices
- Procedure Trays
- Localization Wires
- Other Products
- Needle-based Biopsy Instruments
- By Application
- Breast Biopsy
- Lung Biopsy
- Colorectal Biopsy
- Prostate Biopsy
- Other Applications
- By End-User
- Hospitals
- Diagnostic & Imaging Centers
- Ambulatory Surgical Centers
- Others
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America captured 41.25% of 2025 revenue owing to robust insurance coverage, technology-minded clinicians, and well-defined reimbursement pathways, cementing the region's anchor position in the global biopsy devices market. Continuous innovation-illustrated by AI-assisted OCT, robotic bronchoscopy, and ultrathin flexible needles-ensures a steady refresh cycle for capital equipment. Nevertheless, hospitals face payer scrutiny over procedure bundles, nudging facilities toward cost-effective disposables and predictive analytics that prune unnecessary sampling.
Europe records modest but stable gains as national health systems emphasize value-based purchasing and personalized medicine. Uptake of markers that aid in margin assessment and molecular assays that guide targeted therapy is noticeable, spurring EU demand for high-quality tissue retrieval. Regulatory alignment under the Medical Device Regulation has lengthened approval timelines, but clear clinical-benefit documentation offsets the bureaucratic burden.
Asia-Pacific is projected to log an 8.25% CAGR through 2031, by far the fastest cadence for the biopsy devices market. India's USD 612 billion health-sector build-out, China's expansion of tier-2 oncology centers, and Southeast Asia's private hospital boom enlarge the addressable install base. Governments simultaneously roll out lung, bowel, and cervical screening policies that feed procedure pipelines. Domestic manufacturers are emerging, yet premium U.S., Japanese, and European brands maintain technical leadership in vacuum and image-guided systems.
The Middle East, Africa, and South America account for smaller shares but show selective spikes where public-private partnerships fund cancer hubs. In the Gulf, large specialty hospitals procure top-tier biopsy suites tied to comprehensive oncology campuses. In Brazil and Mexico, reimbursement reforms encourage private insurers to cover advanced biopsy techniques, incrementally widening the patient pool. Supply-chain challenges and variable regulatory oversight temper immediate gains, but multinationals are positioning via local assembly and distribution alliances to unlock future growth.
- Beckton Dickinson
- Hologic
- Danaher
- Cook Group
- Boston Scientific
- Gallini Medical
- TSK Laboratory Europe
- Argon Medical Devices
- B. Braun
- Cardinal Health
- Medtronic
- FUJIFILM
- INRAD
- Olympus
- Merit Medical Systems
- IZI Medical Products
- Danaher
- Devicor Medical Products
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand For Minimally-Invasive Cancer Diagnostics
- 4.2.2 Growing Incidence Of Hard-To-Reach Organ Cancers
- 4.2.3 AI-Enabled Image Guidance Improves First-Pass Yield
- 4.2.4 Expansion Of Government-Funded Screening Programs
- 4.2.5 Growth Of Ambulatory Surgical Centers In Emerging Markets
- 4.3 Market Restraints
- 4.3.1 Device Recalls & Sterility-Failure Events
- 4.3.2 Competition From Liquid-Biopsy Technologies
- 4.3.3 Reimbursement Pressure In High-Volume Markets
- 4.4 Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Needle-based Biopsy Instruments
- 5.1.1.1 Core Biopsy Devices
- 5.1.1.2 Aspiration Biopsy Needles
- 5.1.1.3 Vacuum-Assisted Biopsy Devices
- 5.1.2 Procedure Trays
- 5.1.3 Localization Wires
- 5.1.4 Other Products
- 5.1.1 Needle-based Biopsy Instruments
- 5.2 By Application
- 5.2.1 Breast Biopsy
- 5.2.2 Lung Biopsy
- 5.2.3 Colorectal Biopsy
- 5.2.4 Prostate Biopsy
- 5.2.5 Other Applications
- 5.3 By End-User
- 5.3.1 Hospitals
- 5.3.2 Diagnostic & Imaging Centers
- 5.3.3 Ambulatory Surgical Centers
- 5.3.4 Others
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Becton, Dickinson & Company
- 6.3.2 Hologic Inc.
- 6.3.3 Danaher Corporation
- 6.3.4 Cook Medical
- 6.3.5 Boston Scientific Corporation
- 6.3.6 Gallini Medical
- 6.3.7 TSK Laboratory Europe BV
- 6.3.8 Argon Medical Devices
- 6.3.9 B. Braun Melsungen AG
- 6.3.10 Cardinal Health Inc.
- 6.3.11 Medtronic PLC
- 6.3.12 Fujifilm Holdings Corporation
- 6.3.13 INRAD Inc.
- 6.3.14 Olympus Corporation
- 6.3.15 Merit Medical Systems Inc.
- 6.3.16 IZI Medical Products
- 6.3.17 Leica Biosystems
- 6.3.18 Devicor Medical Products
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment