

|
시장보고서
상품코드
2121829
프로젝트 관리 소프트웨어 시스템 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Project Management Software Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
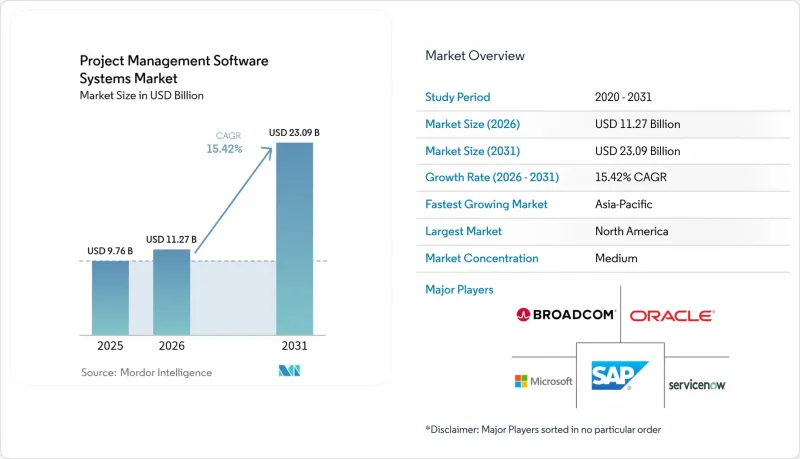
에 따르면 프로젝트 관리 소프트웨어 시스템 시장 규모는 2025년에 97억 6,000만 달러로 평가되며, 2026년 112억 7,000만 달러에서 2031년까지 230억 9,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 15.42%에 달할 전망입니다.

이 보고서는 배포 방식별(클라우드·온프레미스), 조직 규모별(대기업·중소기업), 최종사용자 산업별(IT·통신, 헬스케어, 기타),구독 유형별(월간 구독, 연간 구독, 일회성 라이선스), 지역별(북미, 유럽, 기타)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 프로젝트 관리 소프트웨어 시스템 시장의 동향 및 인사이트
원격·하이브리드형 프로젝트 팀에서의 ‘클라우드 퍼스트’ 도입
한 조직에 따르면 데스크톱 툴에서 클라우드 네이티브 플랫폼으로 전환함으로써 작업 완료 속도가 54% 향상되었다고 합니다. 실시간 동기화를 통해 분산된 팀이 시차에도 불구하고 추진력을 유지할 수 있으므로 프로젝트 관리 소프트웨어 시스템 시장은 성장세를 보이고 있습니다. IT 부서는 용량 계획의 부담을 덜어주는 클라우드의 확장성을 선호합니다. 규제 대상 산업의 경우, 접근 편의성과 데이터 관리의 균형을 중시하므로 하이브리드 모델은 연평균 성장률(CAGR) 18.4%로 성장할 것으로 예측됩니다. 각 벤더는 주권 요건을 충족하면서도 원활한 협업을 유지할 수 있는 데이터 거주지 옵션을 제공함으로써 이러한 수요에 대응하고 있습니다.
PM 플랫폼과 기업 SaaS 스택의 통합
기업은 평균 976개의 애플리케이션을 운영하고 있지만, 그중 실질적으로 통합된 것은 고작 28%에 불과하여 프로젝트 데이터 흐름이 정체되어 있습니다. 최신 플랫폼은 재무, CRM, 인사 시스템과 연동되는 통합 허브로서의 입지를 확립하고 있으며, 이를 통해 기업 아키텍처에서 프로젝트 관리 소프트웨어 시스템의 중요성을 높이고 있습니다. SaaS(Software-as-a-Service) 통합 부문은 2025년까지 150억 달러를 넘어설 것으로 예상되며, 포괄적인 통합 전략을 전개하고 있는 기업에서는 생산성이 30% 향상된 것으로 보고되고 있습니다. 클라우드 네이티브 벤더들은 오픈 API와 기성 커넥터를 통해 경쟁 우위를 확보하고 있으며, 이를 통해 고비용의 맞춤형 코딩 필요성이 줄어들고 있습니다.
레거시 시스템의 고비용 마이그레이션 및 맞춤화 비용
데이터 매핑, 검증, 사용자 교육에는 막대한 노력이 소요되므로, 기업은 라이선스 비용의 3배에 달하는 도입 비용에 직면하고 있습니다. 마이그레이션 비용은 평균 30%를 초과하며, 아카이브 1테라바이트당 1만 5,000달러에 달하는 경우도 있습니다. 이러한 장벽으로 인해 시스템 업데이트 주기가 지연되고, 워크플로가 고도로 맞춤화된 기존 기업에서 프로젝트 관리 소프트웨어 시스템의 시장 침투가 둔화되고 있습니다.
부문 분석
2025년에는 클라우드 배포가 매출의 74.20%를 차지했으나, 하이브리드 구성은 연평균 성장률(CAGR) 18.12%로 성장하며 프로젝트 관리 소프트웨어 시스템 시장에서 가장 강력한 성장세를 보였습니다. 하이브리드 솔루션은 로컬 저장소와 클라우드 작업 공간을 동기화합니다. 이러한 이중성은 데이터 소재지 규제의 제약을 받는 기업을 끌어들이고 있습니다. 온프레미스 솔루션은 정부 및 국방 부문에서 여전히 사용되고 있지만, 클라우드 영역의 보안 인증이 엄격해짐에 따라 그 점유율은 줄어들고 있습니다.
하이브리드 솔루션의 부상은 원활한 오프라인 동기화, 암호화 터널, 선택적 스토리지를 관리하는 툴의 등장을 반영합니다. 건설 회사는 도면을 로컬 서버에 저장하면서, 현장의 최신 정보를 클라우드 대시보드를 통해 공유하고 있습니다. 각 벤더는 세밀한 테넌트 관리 기능을 제공함으로써 차별화를 꾀하고, 규정 준수를 중심으로 한 업셀링 기회를 창출하고 있습니다.
2025년 지출 중 대기업이 60.35%를 차지하고 있지만, 중소기업(SME)은 연평균 성장률(CAGR) 16.89%를 기록하며 프로젝트 관리 소프트웨어 시스템 시장 규모 추이를 새롭게 바꾸고 있습니다. 성장의 중심은 아시아태평양에 있으며, 이 지역의 지방 자치 단체는 디지털 역량 향상을 위한 보조금을 지급하고 있습니다. 일본의 중소기업은 인력 부족을 보완하기 위해 AI를 활용한 스케줄링 시스템을 도입하고 있습니다. 가격 체계에서 사용자 수에 대한 최소 요건이 철폐되어 진입 장벽이 낮아졌습니다.
포화 상태에 이른 지역에서는 대기업 대상 성장세가 정체되어 있으며, 벤더들은 중소기업용 라이트 버전이나 커뮤니티 이벤트를 전개하고 있습니다. 다국적 기업은 여전히 복잡한 통합 기능과 프리미엄 분석 패키지를 통해 수익 기반을 지원하고 있습니다. 이러한 이중적인 초점으로 인해 제품 팀은 온보딩 프로세스를 복잡하게 만들지 않으면서도 확장성을 유지해야 하는 과제에 직면해 있습니다.
지역별 분석
2025년, 북미는 프로젝트 관리 소프트웨어 시스템 시장의 36.12%를 차지했습니다. 이 지역의 기업은 견고한 인프라와 풍부한 IT 예산을 활용하여 엔드투엔드 프로젝트 생태계를 구축하고 있습니다. 마이크로소프트는 Microsoft 365 내의 통합 프로젝트 기능을 바탕으로 2024년에 16%의 매출 성장을 기록하며 2,450억 달러에 도달했습니다. 혁신 허브는 계속해서 AI 모듈 개발을 주도하고 있지만, 보급률이 포화 상태에 가까워짐에 따라 해당 지역의 성장세는 둔화되고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 16.06%를 기록하며 모든 지역 중 가장 높은 성장률을 보이고 있습니다. 중국의 SaaS 부문은 연간 30%에 가까운 속도로 확장되고 있으며, 다국적 기업은 국경을 초월한 사업을 관리하기 위해 Salesforce와 Azure의 통합 스택을 도입하고 있습니다. 인도의 SaaS 매출은 클라우드 보급과 스타트업의 성장세에 힘입어 2023년 71억 8,000만 달러에서 2032년까지 629억 3,000만 달러로 증가할 것으로 예측됩니다. 동남아시아 전역의 중소기업은 지역 규정 준수 기준을 반영한 현지 언어 지원 PM 제품군을 채택하고 있습니다.
유럽에서는 GDPR로 인해 현지화 기능이 필수화됨에 따라 꾸준한 성장을 보이고 있으며, EU내 데이터센터와 고도화된 암호화 기술을 제공하는 벤더들이 유리한 입지를 점하고 있습니다. 남미, 중동 및 아프리카에서는 현재 광대역 및 결제 인프라가 정비되고 있으며, 그동안 인프라 부족으로 인해 저해되었던 클라우드 구독이 확대되고 있습니다. 각 벤더들은 접속 비용이 더욱 낮아지면 두 자릿수 성장이 예상된다고 전망하고 있습니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 세분화
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.03According to Mordor Intelligence, the project management software systems market size was valued at USD 9.76 billion in 2025 and estimated to grow from USD 11.27 billion in 2026 to reach USD 23.09 billion by 2031, at a CAGR of 15.42% during the forecast period (2026-2031).
This report is Segmented by Deployment (Cloud and On-Premise), Organization Size (Large Enterprises, and Small and Medium Enterprises), End-User Industry (IT and Telecom, Healthcare, and More), Subscription Type (Monthly Subscription, Annual Subscription, and One-Time License), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Project Management Software Systems Market Trends and Insights
Cloud-First Adoption for Remote and Hybrid Project Teams
Organizations report 54% faster task completion when shifting from desktop tools to cloud-native platforms. The project management software systems market gains traction because real-time synchronization enables distributed teams to sustain momentum across time zones. IT departments prefer cloud scalability that removes capacity planning burdens. Hybrid models are projected to grow at an 18.4% CAGR because regulated sectors balance accessibility with data control. Vendors respond by offering data-residency options that satisfy sovereignty mandates while maintaining friction-free collaboration.
Integration of PM Platforms with Enterprise SaaS Stacks
Enterprises run an average of 976 applications, yet only 28% are meaningfully integrated, stalling project data flow. Modern platforms position themselves as integration hubs tied to finance, CRM, and HR systems, thereby increasing the relevance of project management software systems in enterprise architecture. The SaaS integration segment is projected to exceed USD 15 billion by 2025, and firms that deploy comprehensive integration strategies report 30% productivity lifts. Cloud-native vendors gain an advantage through open APIs and pre-built connectors, which reduce the need for expensive custom coding.
High Migration and Customization Costs for Legacy Estates
Enterprises face implementation bills that triple license fees because data mapping, validation, and user training are labor-intensive. Migration overruns average 30% and can reach USD 15,000 per terabyte of archives. The hurdle delays refresh cycles and slows the project management software systems market uptake among incumbents with heavily customized workflows.
Other drivers and restraints analyzed in the detailed report include:
- SME Uptake Boosted by Low-Code / No-Code Configurability
- AI-Driven Predictive Analytics for Schedule and Cost Variance
- Data-Sovereignty and Privacy Concerns in Multi-Tenant Clouds
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud deployment accounted for 74.20% of revenue in 2025, but hybrid configurations grew at an 18.12% CAGR, signaling the strongest momentum within the project management software systems market. Hybrid solutions synchronize local repositories with cloud workspaces; this duality attracts firms bound by data residency statutes. On-premise solutions persist in government and defense, yet their share is shrinking as security certifications for cloud zones become tighter.
The hybrid rise reflects tools that now manage seamless offline sync, encrypted tunnels, and selective storage. Construction companies store drawings on local servers while sharing field updates through cloud dashboards. Vendors differentiate by offering granular tenancy controls, creating upsell paths around compliance.
Large enterprises controlled 60.35% of the 2025 spend, but SMEs chart a 16.89% CAGR, reshaping the project management software systems market size trajectory. Growth centers on the Asia-Pacific region, where local governments are funding digital upskilling grants. Japanese SMEs adopt AI-assisted scheduling to offset labor shortages. Pricing tiers remove user minimums, reducing the barrier to entry.
Enterprise growth plateaus in saturated regions, so vendors launch light editions and community events geared to smaller firms. Yet, multi-national corporations still anchor revenue with complex integrations and premium analytics bundles. Dual focus forces product teams to maintain scalability without complicating the onboarding process.
Complete Report Scope:
- By Deployment
- Cloud
- On-premise
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises
- By End-user Industry
- IT and Telecom
- Healthcare
- Construction and Infrastructure
- BFSI
- Government and Public Sector
- Manufacturing
- Others
- By Subscription Type
- Monthly Subscription
- Annual Subscription
- One-time License
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Nordics
- Rest of Europe
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Australia
- New Zealand
- Rest of Asia-Pacific
- North America
Geography Analysis
North America held 36.12% of the project management software systems market in 2025. Enterprises there leverage robust infrastructure and sizable IT budgets to roll out end-to-end project ecosystems. Microsoft recorded 16% revenue growth to USD 245 billion in 2024, supported by integrated project functions within Microsoft 365. Innovation hubs continue to pioneer AI modules, yet regional growth moderates as penetration nears saturation.
Asia-Pacific grows at a 16.06% CAGR through 2031, the fastest across regions. China's SaaS segment is expanding at nearly 30% annually, with multinationals installing integrated Salesforce and Azure stacks to manage cross-border initiatives. India's SaaS revenue is forecast to increase from USD 7.18 billion in 2023 to USD 62.93 billion by 2032, driven by cloud adoption and startup momentum. SMEs across Southeast Asia adopt local-language PM suites that embed regional compliance norms.
Europe posts steady gains as GDPR compels localization features, rewarding vendors offering EU data centers and advanced encryption. South America, and Middle East, and Africa are now improving broadband and payment rails, nurturing cloud subscriptions previously held back by infrastructure gaps. Vendors anticipate double-digit uptake once connectivity costs fall further.
- Adobe Inc. (Workfront)
- AEC Software Inc.
- Asana Inc.
- Atlassian Corporation PLC
- Basecamp LLC
- Broadcom Inc. (Clarity PPM)
- ClickUp (Mango Technologies, Inc.)
- Microsoft Corporation
- Monday.com Ltd.
- Oracle Corporation
- Planview Inc.
- Procore Technologies Inc.
- SAP SE
- ServiceNow Inc.
- Smartsheet Inc.
- Teamwork.com Ltd.
- Trello Enterprise (Atlassian)
- Unit4 N.V.
- Wrike Inc. (Citrix Systems)
- Zoho Corporation Pvt Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud-First Adoption for Remote and Hybrid Project Teams
- 4.2.2 Integration of PM Platforms with Enterprise SaaS Stacks
- 4.2.3 SME Uptake Boosted by Low-Code / No-Code Configurability
- 4.2.4 AI-Driven Predictive Analytics for Schedule and Cost Variance
- 4.2.5 Vertical-Specific PM Suites (e.g., Construction, Healthcare)
- 4.2.6 ESG Compliance Reporting Embedded in Project Workflows
- 4.3 Market Restraints
- 4.3.1 High Migration and Customization Costs for Legacy Estates
- 4.3.2 Data-Sovereignty and Privacy Concerns in Multi-Tenant Clouds
- 4.3.3 Feature Commoditization Heightening Vendor-Lock-in Risk
- 4.3.4 Change-Management Fatigue Curbing Large-Scale Roll-Outs
- 4.4 Evaluation of Critical Regulatory Framework
- 4.5 Industry Value Chain Analysis
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact Assessment of Key Stakeholders
- 4.9 Key Use Cases and Case Studies
- 4.10 Impact on Macroeconomic Factors of the Market
- 4.11 Investment Analysis
5 MARKET SEGMENTATION
- 5.1 By Deployment
- 5.1.1 Cloud
- 5.1.2 On-premise
- 5.2 By Organization Size
- 5.2.1 Large Enterprises
- 5.2.2 Small and Medium Enterprises
- 5.3 By End-user Industry
- 5.3.1 IT and Telecom
- 5.3.2 Healthcare
- 5.3.3 Construction and Infrastructure
- 5.3.4 BFSI
- 5.3.5 Government and Public Sector
- 5.3.6 Manufacturing
- 5.3.7 Others
- 5.4 By Subscription Type
- 5.4.1 Monthly Subscription
- 5.4.2 Annual Subscription
- 5.4.3 One-time License
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Nordics
- 5.5.3.7 Rest of Europe
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Turkey
- 5.5.4.1.4 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Nigeria
- 5.5.4.2.4 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 Asia-Pacific
- 5.5.5.1 China
- 5.5.5.2 India
- 5.5.5.3 Japan
- 5.5.5.4 South Korea
- 5.5.5.5 ASEAN
- 5.5.5.6 Australia
- 5.5.5.7 New Zealand
- 5.5.5.8 Rest of Asia-Pacific
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Adobe Inc. (Workfront)
- 6.4.2 AEC Software Inc.
- 6.4.3 Asana Inc.
- 6.4.4 Atlassian Corporation PLC
- 6.4.5 Basecamp LLC
- 6.4.6 Broadcom Inc. (Clarity PPM)
- 6.4.7 ClickUp (Mango Technologies, Inc.)
- 6.4.8 Microsoft Corporation
- 6.4.9 Monday.com Ltd.
- 6.4.10 Oracle Corporation
- 6.4.11 Planview Inc.
- 6.4.12 Procore Technologies Inc.
- 6.4.13 SAP SE
- 6.4.14 ServiceNow Inc.
- 6.4.15 Smartsheet Inc.
- 6.4.16 Teamwork.com Ltd.
- 6.4.17 Trello Enterprise (Atlassian)
- 6.4.18 Unit4 N.V.
- 6.4.19 Wrike Inc. (Citrix Systems)
- 6.4.20 Zoho Corporation Pvt Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


