

|
시장보고서
상품코드
2121965
인도네시아의 섬유 제조 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Indonesia Textile Manufacturing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
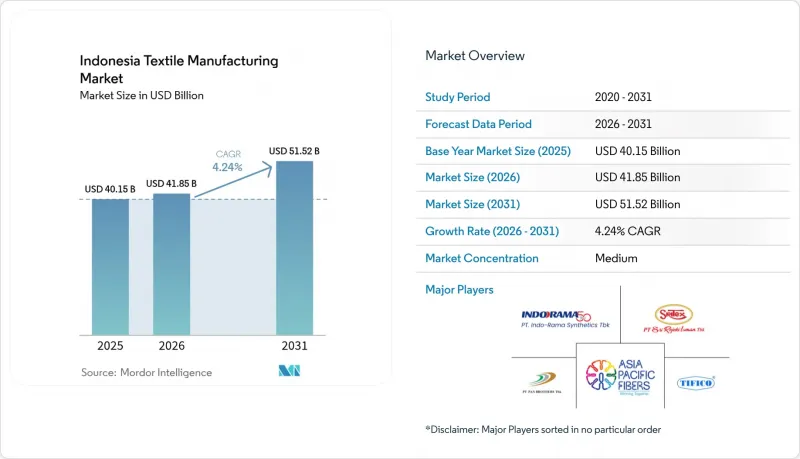
에 의하면, 2026년 인도네시아의 섬유 제조 시장 규모는 418억 5,000만 달러로 추정되며, 2025년 401억 5,000만 달러에서 2031년에는 515억 2,000만 달러에 달할 것으로 예측됩니다.
또한 2026-2031년 연평균 성장률(CAGR) 4.24%를 기록할 전망입니다.
본 보고서는 제조 공정별(직물, 편물, 방적 등), 섬유 제품별(원단, 실, 섬유 등),소재별(천연섬유(면, 비단 등) 등), 용도별(의류, 가정용 직물 등), 지역별(자바, 수마트라 등)로 분류되어 있습니다. 본 보고서에서는 상기 모든 부문에 대해 시장 규모 및 예측치(달러)를 제시하고 있습니다.
인도네시아의 섬유 제조 시장 동향 및 인사이트
미국 및 EU 브랜드의 액티브웨어 주문이 자바의 클러스터로 니어쇼어링되는 경향이 강해지고 있습니다.
기존 아시아 거점의 인건비 급등과 보다 신속한 재고 보충의 필요성으로 인해, 유럽 및 미국 브랜드들은 자바 섬의 대규모 공장에 주목하고 있습니다. 연간 생산 능력 1억 1,700만 벌을 자랑하는 판 브라더스(Pan Brothers)는 기능성 니트웨어의 추가 수주를 확보하며 인도네시아로의 전환이 두드러지고 있습니다. 섬 내 산업단지 내에서 실·원단·봉제 부문이 인접해 있어 리드 타임이 단축되고 취급 비용도 절감되고 있습니다. 그렇다 하더라도, 미국의 관세 인상 가능성에 대한 불확실성은 생산자들에게 여전히 주시해야 할 사항으로 남아 있습니다.
이슬람 패션 수출의 급성장이 고부가가치 의류 생산을 견인
인도네시아는 문화적 친화성과 디자인 역량을 활용하여, 2023년 3,610억 달러로 추정되는 지속적으로 확대되는 세계 ‘모데스트 패션’ 시장에 제품을 공급하고 있습니다. 뉴욕 패션 위크에서의 전시를 통해 국제적인 인지도가 높아지면서, 현지 브랜드는 더 높은 가격 책정이 가능해졌습니다. 부가가치가 높은 제품 라인은 고객과의 유대감을 강화하고, 고도의 장식 기술이 필요하기 때문에 방적 공장은 특수 기계 및 숙련된 장인 양성에 투자를 확대되고 있습니다.
불법 저가 수입품이 중소 직물 제조업체의 이익률을 잠식하고 있습니다.
불법 수입품은 현지 가격보다 낮아 공장 폐쇄와 인력 감축을 초래하고 있으며, 정부는 수입 허가 기준을 엄격히 하고 검사를 강화할 수밖에 없는 상황입니다. 200%의 세이프가드 관세가 부과되고 있음에도 불구하고, 집행 체계의 허술함으로 인해 위조품이나 규격 미달 원단이 항구를 통과해 버리고 있어, 지역에 뿌리를 둔 직물 클러스터는 간접비를 회수하지 못하고 있습니다. 새로운 Permenperin 5/2024 규정은 서류 요건을 명확히 하고 세관 데이터베이스를 연동함으로써 이러한 허점을 막는 것을 목적으로 합니다.
부문 분석
2025년, 인도네시아의 섬유 제조 시장에서 직물 부문은 36.92%의 점유율을 유지했습니다. 이는 서자바주의 클러스터에 기반을 둔 셔틀 직기 및 레이피어 직기의 생산 능력에 힘입은 결과입니다. 생산량은 주로 셔츠 원단과 데님용이며, 이러한 부문은 여전히 안정적인 수출량을 뒷받침하고 있습니다. 한편, 니트 부문은 퍼포먼스 의류 및 애슬레저 라인의 급증에 힘입어 2031년까지 연평균 성장률(CAGR) 4.93%로 성장을 지속하고, 있습니다. 생산자들은 소량 생산 및 기능성 혼방사에 대응할 수 있는 원형 편직기를 도입하여, 온라인 소매업체들이 선호하는 짧은 납기 모델에 부응하고 있습니다.
니트 분야의 성장은 동남아시아에서 신속한 재고 보충을 요구하는 스포츠웨어 브랜드의 주문 증가도 반영하고 있습니다. 자바 섬에 기반을 둔 제조업체들은 동일 부지 내의 염색 공장 및 프린트 공장을 활용하여 완제 의류를 납품함으로써, 원단만 공급하는 업체보다 높은 부가가치를 창출하고 있습니다. 중기적으로는 심리스 구조와 같은 첨단 니트 기술이 생산성을 향상시키고 생산 후 폐기물을 줄임으로써, 착용감을 중시하는 의류 분야에서 인도네시아의 경쟁력을 더욱 강화할 것으로 예측됩니다.
2025년, 인도네시아의 섬유 제조 시장 점유율의 59.5%를 의류가 차지하고 있으며, 이는 해당국의 높은 봉제 기술력과 풍부한 노동력을 뒷받침하고 있습니다. 생산자들은 재단·봉제·마감에 그치지 않고 풀 패키지 서비스로 전환하고 있으며, 브랜드 고객에게 디자인 제안, 머천다이징, 규정 준수 관련 서류 제공을 하고 있습니다. 가장 빠른 성장세를 보이고 있는 분야는 연평균 성장률(CAGR) 4.89%를 기록하는 기능성·산업용 섬유 분야로, 이는 인프라 투자와 자동차 OEM의 현지 생산화를 반영한 것입니다.
의류 분야에서 지속적인 주도적 지위는 인도네시아의 ‘모데스트웨어’라는 틈새 시장에도 기인합니다. 이 분야에서는 각 브랜드가 수출 시장을 겨냥해 전통적인 모티프와 현대적인 실루엣을 융합하고 있습니다. 업스트림 공정인 원단 제조 및 염색 공정을 자체적으로 관리하는 통합형 기업은 이익률 향상을 도모하는 동시에 브랜드의 감사 기준을 준수하는 품질을 확보하고 있습니다. 한편, 원단만을 생산하는 제조업체는 생산량의 상당 부분을 보호복, 필터, 자동차 부품으로 전환함으로써 패션 유행 주기에 대한 의존도를 낮추고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.10According to Mordor Intelligence, the Indonesia textile manufacturing market size market size in 2026 is estimated at USD 41.85 billion, growing from 2025 value of USD 40.15 billion with 2031 projections showing USD 51.52 billion, growing at 4.24% CAGR over 2026-2031.
This report is Segmented by Process Type (Weaving, Knitting, Spinning, and More), by Textile Type (Fabric, Yarn, Fiber, and More), by Material Type (Natural Fibers (Cotton, Silk Etc. ), and More), by Application (Apparel, Home Textiles, and More), and by Region (Java, Sumatra and More). The Report Offers Market Size and Forecasts in Value (USD) for all the Above Segments.
Indonesia Textile Manufacturing Market Trends and Insights
Rising Near-Shoring of Activewear Orders from US & EU Brands to Java Clusters
Labor cost escalation in legacy Asian hubs and the need for faster replenishment bring Western labels to Java's large-scale plants. Pan Brothers, with annual capacity of 117 million pieces, has secured incremental contracts for performance knitwear, underscoring the pivot toward Indonesia. Close proximity among yarn, fabric, and garment units inside the island's industrial estates compresses lead times and lowers handling expenses. Nevertheless, uncertainty over potential US tariff hikes remains a watchpoint for producers.
Boom in Muslim Fashion Exports Driving Value-Added Garment Production
Indonesia leverages cultural affinity and design talent to supply the expanding global modest-fashion segment, estimated at USD 361 billion in 2023. Showcases at New York Fashion Week have raised international visibility, allowing local brands to command higher price points. Value-added lines create stickier customer relationships and require advanced embellishment techniques, prompting mills to invest in specialty machinery and skilled artisans.
Illegal Low-Priced Imports Eroding SME Weaving Margins
Unlawful inflows undercut local price points and have triggered factory closures and layoffs, pushing the government to tighten import permits and step up inspections. Even with 200% safeguard tariffs, weak enforcement lets counterfeit and sub-standard fabrics slip through ports, leaving community-based weaving clusters unable to recover overheads. The new Permenperin 5/2024 regulation aims to close loopholes by clarifying documentation requirements and synchronizing customs databases.
Other drivers and restraints analyzed in the detailed report include:
- Government "Making Indonesia 4.0" Incentives Accelerating Textile Automation
- Surge in E-Commerce-Led Domestic Apparel Demand Among Gen-Z Consumers
- Chronic Port & Rail Bottlenecks Inflating Inter-Island Logistics Cost
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Weaving retained a 36.92% share of the Indonesia textile manufacturing market in 2025, anchored by entrenched shuttle and rapier loom capacity across West Java clusters. Output caters mainly to shirtings and denim, segments that still support steady export volumes. Knitting, however, posts a 4.93% CAGR through 2031 as performance apparel and athleisure lines surge. Producers deploy circular knitting machines capable of smaller lot sizes and functional yarn blends, aligning with the short-run model favored by online retailers.
Knitting's growth also reflects rising orders from sportswear labels seeking quick replenishment out of Southeast Asia. Java-based makers leverage co-located dye-houses and print shops to deliver fully packaged garments, capturing greater value than fabric-only suppliers. In the medium term, advanced knitting techniques such as seamless construction are expected to lift productivity and reduce post-production waste, reinforcing Indonesia's competitiveness in comfort apparel.
Garments represented 59.5% of the Indonesia textile manufacturing market share in 2025, testifying to the country's deep sewing expertise and abundant workforce. Producers have moved beyond cut-make-trim to full-package services, offering design input, merchandising, and compliance documentation to brand customers. The fastest expansion occurs in technical and industrial textiles at 4.89% CAGR, reflecting infrastructure spending and automotive OEM localization.
Continued garment leadership also stems from Indonesia's modest-wear niche, where brands merge traditional motifs with modern silhouettes for export markets. Integrated players that control upstream fabric and dyeing steps capture improved margins and ensure quality alignment with brand audits. Meanwhile, fabric-only producers channel more output into protective wear, filtration, and automotive components, reducing reliance on fashion cycles.
Complete Report Scope:
- By Process Type
- Spinning
- Weaving
- Knitting
- Finishing
- Other Processes (non-woven)
- By Textile Type
- Fiber
- Yarn
- Fabric
- Garments
- Other Textiles
- By Material Type
- Natural Fibers (Cotton, Silk etc.)
- Synthetic Fibers (Polyester, Nylon etc.)
- Others (Regenerated & Recycled Fibers, Speciality Fibers)
- By Application
- Apparel
- Home Textiles
- Technical/Industrial Textiles
- Other Applications
- By Region (Indonesia)
- Java
- Sumatra
- Others (Kalimantan, Sulawesi, Bali, etc.)
List of Companies Covered in this Report:
- PT Asia Pacific Fibres Tbk
- Indo-Rama Synthetics Tbk
- PT Sri Rejeki Isman Tbk (Sritex)
- PT Tifico Fiber Indonesia Tbk
- PT Pan Brothers Tbk
- PT Ever Shine Tex Tbk
- PT Trisula Textile Industries Tbk
- PT Century Textile Industry Tbk (Toray)
- PT Polychem Indonesia Tbk
- PT Argo Pantes Tbk
- Duniatex Group
- PT Kahatex
- PT Apac Inti Corpora
- PT Eratex Djaja Tbk
- PT Ateja Tritunggal
- PT Sinar Para Taruna
- PT Kewalram Indonesia
- PT Pura Group (Textile Div.)
- PT Multi Garmenjaya
- PT Delami Garment Industries
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government "Making Indonesia 4.0" incentives accelerating textile automation
- 4.2.2 Rising near-shoring of activewear orders from US & EU brands to Java clusters
- 4.2.3 Boom in Muslim fashion exports driving value-added garment production
- 4.2.4 Surge in e-commerce-led domestic apparel demand among Gen-Z consumers
- 4.2.5 Import-substitution push for man-made fibers amid high cotton dependency
- 4.2.6 Investor tax breaks for green dye-house upgrades in Central Java
- 4.3 Market Restraints
- 4.3.1 Illegal low-priced imports eroding SME weaving margins
- 4.3.2 Chronic port & rail bottlenecks inflating inter-island logistics cost
- 4.3.3 Volatile PLN electricity tariffs squeezing energy-intensive spinning
- 4.3.4 Tight labour pool in West Java driving wage inflation vs. Vietnam
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory & Government-Initiative Outlook
- 4.6 Technological Outlook - Industry 4.0 & Digital Transformation Readiness
- 4.7 Industry Attractiveness - Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Recent Global Disruptions on the Indonesia Textile Manufacturing Industry
- 4.9 Sustainability & Circular Economy Trends
5 Market Size & Growth Forecasts (Value, In USD Billion)
- 5.1 By Process Type
- 5.1.1 Spinning
- 5.1.2 Weaving
- 5.1.3 Knitting
- 5.1.4 Finishing
- 5.1.5 Other Processes (non-woven)
- 5.2 By Textile Type
- 5.2.1 Fiber
- 5.2.2 Yarn
- 5.2.3 Fabric
- 5.2.4 Garments
- 5.2.5 Other Textiles
- 5.3 By Material Type
- 5.3.1 Natural Fibers (Cotton, Silk etc.)
- 5.3.2 Synthetic Fibers (Polyester, Nylon etc.)
- 5.3.3 Others (Regenerated & Recycled Fibers, Speciality Fibers)
- 5.4 By Application
- 5.4.1 Apparel
- 5.4.2 Home Textiles
- 5.4.3 Technical/Industrial Textiles
- 5.4.4 Other Applications
- 5.5 By Region (Indonesia)
- 5.5.1 Java
- 5.5.2 Sumatra
- 5.5.3 Others (Kalimantan, Sulawesi, Bali, etc.)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)}
- 6.4.1 PT Asia Pacific Fibres Tbk
- 6.4.2 Indo-Rama Synthetics Tbk
- 6.4.3 PT Sri Rejeki Isman Tbk (Sritex)
- 6.4.4 PT Tifico Fiber Indonesia Tbk
- 6.4.5 PT Pan Brothers Tbk
- 6.4.6 PT Ever Shine Tex Tbk
- 6.4.7 PT Trisula Textile Industries Tbk
- 6.4.8 PT Century Textile Industry Tbk (Toray)
- 6.4.9 PT Polychem Indonesia Tbk
- 6.4.10 PT Argo Pantes Tbk
- 6.4.11 Duniatex Group
- 6.4.12 PT Kahatex
- 6.4.13 PT Apac Inti Corpora
- 6.4.14 PT Eratex Djaja Tbk
- 6.4.15 PT Ateja Tritunggal
- 6.4.16 PT Sinar Para Taruna
- 6.4.17 PT Kewalram Indonesia
- 6.4.18 PT Pura Group (Textile Div.)
- 6.4.19 PT Multi Garmenjaya
- 6.4.20 PT Delami Garment Industries
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment


