|
시장보고서
상품코드
2121990
퍼스널케어 포장 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Personal Care Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
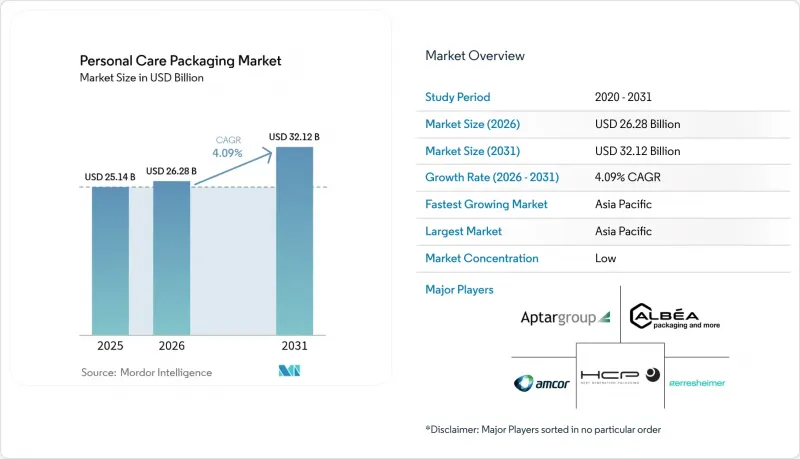
에 의하면, 퍼스널케어 포장 시장 규모는 2025년에 251억 4,000만 달러로 평가되었고 2026년 262억 8,000만 달러에서 2031년까지 321억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 4.09%를 나타낼 전망입니다.
본 보고서는 소재 유형(플라스틱, 유리, 금속, 종이 및 판지), 포장 형태(연포장, 경질 포장), 제품 유형(병·용기, 튜브·스틱, 펌프·디스펜서,파우치·사셰 등), 용도(스킨케어, 헤어케어, 구강 관리, 메이크업 제품 등), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 퍼스널케어 포장 시장 동향 및 인사이트
신흥 시장에서 미용 제품의 프리미엄화
인도, 브라질, 중국의 중산층 소득 증가에 따라 소비자들은 높은 품질을 나타내는 유리, 알루미늄, 고급 플라스틱으로 제작된 패키지에 담긴 브랜드 퍼스널케어 제품을 선택하고 있습니다. 인도의 미용 시장은 2025년에 12% 성장할 것으로 예상되며, 도시 지역 소비자들은 엠보싱 처리된 병, 메탈라이즈 처리된 용기, 위조 방지 기능이 있는 펌프와 같은 고급 제품으로 구매를 전환했습니다. 브라질의 브랜드 ‘나투라(Natura)’는 지속가능성을 증명하는 수단으로 재충전 가능한 유리 용기 프로그램을 확대하여, 진열대에서 프리미엄 가격 책정을 촉진했습니다. 중국에서는 2선 도시에서 유효 성분을 보호하고 과학적인 브랜드 이미지를 강화하기 위해 에어리스 디스펜서가 필요한 남성용 그루밍 세럼이 18% 급증했습니다. 그 결과, 컨버터의 투자는 소매업체의 고급스러운 디자인에 대한 요구를 충족시키면서 높은 수익률을 가져다주는 핫 스탬핑, 진공 메탈라이제이션 및 에어리스 펌프 생산 라인으로 이동하고 있습니다.
옴니채널 풀필먼트가 보호 기능과 배송 대응을 겸비한 패키지를 주도
2025년, 뷰티 관련 전자상거래는 북미 매출의 35%, 유럽에서는 28%에 달할 전망이며, 패키지 디자인은 진열대에 전시할 수 있는 외관을 유지하면서도 소포 분류 공정을 견딜 수 있는 사양으로 전환되고 있습니다. 암콜(Amcor)의 이중벽 플렉서블 파우치는 소비자에게 직접 배송되는 과정에서 파손률을 40% 감소시켰으며, 얇고 단단한 병을 경량 필름으로 대체할 수 있음을 입증했습니다. 또한 소매업체들은 매장 진열에서 배송용 상자로 옮길 때 불필요한 완충재가 필요 없는 포장을 요구하고 있어, 손잡이가 일체형으로 되어 있고 쌓을 수 있는 경질 병, 응력이 가해지는 모서리가 보강된 파우치가 보급되고 있습니다. 운임이 도착 비용의 평균 8-12%를 차지하기 때문에 화주들은 팔레트의 적재 밀도를 높여, 부피 중량에 따른 추가 요금을 절감할 수 있는 디자인을 선호합니다.
변동이 심한 폴리올레핀 및 PET 원료 가격
2024년, 폴리에틸렌 및 PET 가격은 전 분기 대비 15-25% 변동하여, 60-90일간의 판매 가격에 묶여 있던 가공업체의 이익률을 압박했습니다. PCR-PET는 버진 PET에 비해 10-15%의 프리미엄 가격으로 거래되고 있어, 재활용 소재 함유 의무를 추구하는 기업들에게 가격 변동 위험을 더욱 증폭시키고 있습니다. 헤지 수단이 없는 중소규모 사업자들은 시장에서 철수하거나 합병을 단행했습니다. 그 예로 2025년에 사업을 매각한 유럽의 튜브 제조업체 3곳을 들 수 있습니다. 가격 급등에 따라 설비 투자가 정체되고, 새로운 압출 성형 및 블로우 성형 라인 도입이 지연되면서 공급의 유연성이 저하되고 있습니다. PCR PET는 버진 PET에 비해 10-15%의 프리미엄을 붙여 거래되고 있어, 재활용 소재 함유율 의무화 목표를 추구하는 기업들에게 가격 변동의 격차를 더욱 확대시키고 있습니다. 이에 반해, 각 브랜드 기업들은 예산의 확실성을 우선시하여 기회적 비용 절감을 희생하는 연간 수지 계약을 체결하고 있으나, 이러한 전략은 단기적인 유연성을 저해하는 결과를 초래하고 있습니다.
부문 분석
플라스틱은 2025년 매출의 41.12%를 차지하며, PCR 및 바이오 수지의 통합에 힘입어 2031년까지 4.89%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망이며, 퍼스널케어 포장 시장에서 그 우위를 더욱 공고히 하고 있습니다. 폴리에틸렌으로 만든 파우치와 스퀴즈 튜브가 주류를 이루는 이유는 내화학성과 열 밀봉 강도가 농축액 리필에 적합하기 때문입니다. 한편, 폴리프로필렌은 내피로성이 요구되는 캡이나 펌프 분야에서 뛰어난 성능을 보입니다. PET는 향을 보호하는 투명한 경질 병 분야에서 점유율을 유지하고 있지만, 가소제 이화와 관련된 유럽의 단계적 폐지 압력으로 인해 PVC의 점유율은 축소되고 있습니다. 사탕수수 유래 폴리에틸렌과 옥수수 유래 PLA는 플라스틱 부문의 3%를 차지하고 있으며, 포장을 통해 지속가능성을 어필하기 위해 두 자릿수의 프리미엄을 지불하는 것을 마다하지 않는 브랜드들로부터 지지를 받고 있습니다.
2025년에는 22%를 차지할 유리는 중후한 느낌이 장인 정신을 상징하는 고급 향수 시장에서 우위를 점하고 있지만, 전자상거래(EC)에서의 파손 위험과 높은 운송 비용이 판매량 확대를 저해하고 있습니다. 알루미늄은 데오도란트 에어로졸 및 여행용 사이즈 제품에 힘입어 18%의 점유율을 확보하고 있으며, ‘무한히 재활용 가능’이라는 점이 호재로 작용하고 있습니다. 판지의 점유율은 19%로, 브랜드 스토리를 전달하는 접이식 카톤이 주를 이루지만, 습기에 약하다는 특성 때문에 1차 포장에서의 사용이 제한되고 있습니다. 이러한 동향이 맞물려 플라스틱은 퍼스널케어 포장 시장의 중심적인 지위를 유지하고 있지만, 바이오 유래 소재 증가로 인해 소재 선택의 폭이 넓어지면서 각 컨버터 기업들은 압출 성형기 라인업을 다양화하려고 하고 있습니다.
2025년 시장 가치의 62.76%를 차지하는 경질 용기는 스킨케어 및 헤어케어 제품에 필수적인 확립된 충전 라인 인프라와 매장 내 존재감 덕분에 여전히 지배적인 위치를 유지하고 있습니다. 일체형 펌프와 에어로졸 밸브는 정확한 용량을 공급함으로써 브랜드에 대한 신뢰를 높이고, 퍼스널케어 포장 시장에서 고가 제품의 인기를 뒷받침하고 있습니다. 나머지 37.24%를 차지하는 연포장은 전자상거래에서의 높은 내구성, 최대 70%에 달하는 소재 중량 절감, 그리고 무거운 경질 제품에 부과되는 규제상의 친환경 조정 요금의 뒷받침을 받아 연평균 성장률(CAGR) 4.51%로 시장 평균을 상회하는 성장을 보이고 있습니다.
배리어 층과 완충 층을 일체화한 Amcor의 이중벽 파우치는 차세대 제품으로, 별도의 삽입물이 필요 없으며 파손 관련 클레임을 절반으로 줄이고 있습니다. 리필 플랫폼에 대한 선호도는 재사용 가능한 파우치가 욕실에서의 전체 사용 주기에 걸쳐 운송 시 발생하는 배출량을 분산시키기 때문에 더욱 유연한 농축형으로 기울고 있습니다. 한편, 경질 용기 제조업체들은 소비자가 익숙한 사용감을 해치지 않으면서 EU 지침을 충족하기 위해 경량화와 테더가 부착된 캡 채택을 추진함으로써 시장 점유율 하락을 막고 있습니다.
지역별 분석
아시아태평양은 2025년에 33.37%의 점유율을 차지하며, 퍼스널케어 포장 시장의 핵심으로 계속해서 군림하고 있습니다. 중국에서는 프리미엄 향수의 신제품에 리필 가능한 유리 용기가 채택되어, 환경 의식이 높은 소비자를 끌어모으고 있습니다. 한편, 인도의 도시권 소비자층은 스킨케어 및 헤어케어 제품에서 메탈라이즈 가공된 펌프식 용기로의 업그레이드가 진행되고 있습니다. 동남아시아에서는 남성 그루밍 시장의 두 자릿수 성장이 알루미늄 에어로졸 캔 제품 수요를 견인하고 있으며, 일본에서는 고령화 사회를 배경으로 안티에이징용 에어리스 디스펜서 수요가 증가하고 있습니다. 한국에서는 수출 지향적인 K-뷰티 브랜드들이 열대 지역 운송을 견딜 수 있는 방습 파우치를 지정하고 있으며, 호주는 30%의 PCR(소비 후 재활용) 의무화에 가장 먼저 대응하여 아시아 전역으로의 확대에 앞서 추적성 기술의 실증 무대가 되고 있습니다.
2025년, 유럽은 28%의 점유율을 차지했는데, 이는 엄격한 PCR 할당량, 캡 고정 규제, 그리고 컨버터에게 화학 재활용 제휴를 요구하는 에코라벨 감사에 의해 형성된 결과입니다. 독일과 프랑스에서는 매장 내 리필 코너가 확대되면서 1회당 사용 재료를 70% 절감하는 동시에, 쇼핑객들에게 내구성이 뛰어난 용기 사용을 장려하고 있습니다. 이탈리아와 스페인에서는 향수 시장에서 고급스러운 느낌을 표현하기 위해 유리 병에 의존하고 있지만, 운송비와 파손 문제가 단위당 성장을 억제하고 있습니다. 폴란드가 주도하는 동유럽에서는 낮은 인건비와 지역적 근접성을 결합한 컨버터의 니어쇼어링이 촉진되어, 유럽 및 미국 브랜드를 위한 튜브와 캡의 생산 능력이 강화되고 있습니다.
2025년에는 북미가 매출의 22%를 차지할 전망이며, 미국의 옴니채널 수요에 힘입어 불필요한 완충재를 사용하지 않고 진열대에서 집 앞까지 배송할 수 있는 포장이 장려되고 있습니다. 캐나다의 일회용 플라스틱 단계적 금지 조치로 인해 단일 소재의 연포장재 및 판지 사용이 가속화되고 있습니다. 멕시코의 니어쇼어링을 통한 생산 능력은 미국 브랜드에 대한 관세 및 리드타임 제약을 완화하고 있습니다. 주별 법률의 차이, 특히 캘리포니아주의 SB 54나 워싱턴주의 포장세는 복잡성을 가중시키고 있으며, 포트폴리오의 파편화를 피하기 위해 전미에서 가장 엄격한 기준을 채택하는 추세가 진행되고 있습니다.
2031년까지 연평균 성장률(CAGR) 5.08%의 성장이 예상되는 남미 시장은 브라질의 리필용 유리 용기 도입 노력과 고부가가치 포장을 갖춘 수입 향수에 소득을 투자하는 아르헨티나 도시 지역의 고소득층 수요에 힘입고 있습니다. 중동(성장률 8%)에서는 고급 향수를 위한 장식용 유리 용기와 메탈릭 마감 캡에 초점이 맞추어져 있으며, 튀르키예가 컨버터의 거점으로 자리 잡고 있습니다. 아프리카 시장의 7% 점유율은 저렴한 가격 덕분에 향 주머니에 크게 의존하고 있지만, 지방 정부의 일회용 플라스틱 금지 조치로 인해 시장은 재밀봉이 가능한 다회용 파우치로 전환되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.11According to Mordor Intelligence, the personal care packaging market size was valued at USD 25.14 billion in 2025 and is estimated to grow from USD 26.28 billion in 2026 to reach USD 32.12 billion by 2031, at a CAGR of 4.09% during the forecast period (2026-2031).
This report is Segmented by Material Type (Plastic, Glass, Metal, and Paper and Paperboard), Packaging Format (Flexible, and Rigid), Product Type (Bottles and Jars, Tubes and Sticks, Pumps and Dispensers, Pouches and Sachets, and More), Application (Skin Care, Hair Care, Oral Care, Make-Up Products, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Personal Care Packaging Market Trends and Insights
Premiumization Of Beauty SKUs In Emerging Markets
Rising middle-class incomes in India, Brazil, and China steer shoppers toward branded personal-care products packaged in glass, aluminum, and premium plastics that signal quality. India's beauty sector grew 12% in 2025 as urban consumers traded up to embossed bottles, metallized jars, and tamper-evident pumps. Brazilian brand Natura scaled refillable glass programs that position permanence as proof of sustainability, fostering premium shelf pricing. In China, tier-2 cities recorded an 18% surge in male-grooming serums that require airless dispensers to protect active ingredients and reinforce scientific branding. Converter investment therefore tilts to hot-stamping, vacuum-metallization, and airless-pump lines that deliver higher-margin orders while satisfying retailer calls for luxury aesthetics.
Omni-Channel Fulfilment Driving Protective And Ship-Ready Packs
Beauty e-commerce reached 35% of North American sales and 28% in Europe during 2025, shifting packaging design toward variants that survive parcel sorting while remaining shelf-presentable. Amcor's dual-wall flexible pouch reduced breakage rates by 40% in direct-to-consumer shipments, proving that thin, rigid bottles can be replaced with lighter films. Retailers also demand packs that migrate from store display to mailing carton without extra void fill, promoting stackable rigid bottles with integrated handles and pouches reinforced at stress corners.As freight averages 8-12% of landed cost, shippers favor designs that boost pallet density and reduce dimensional weight fees.
Volatile Polyolefin and PET Feed-Stock Prices
Polyethylene and PET swung 15-25% quarter-over-quarter during 2024, compressing margins for converters locked into 60-90-day selling prices. PCR PET trades at a 10-15% premium to virgin PET, magnifying volatility for firms pursuing recycled-content mandates. Smaller players without hedging tools exited or merged, evidenced by three European tube makers that sold out in 2025. Capital-spending pauses follow price spikes, delaying the installation of new extrusion or blow-molding lines and crimping supply responsiveness. PCR PET trades at a 10-15% premium to virgin, compounding volatility for firms chasing recycled-content mandates. Brands respond by signing annual resin contracts that sacrifice opportunistic savings for budgeting certainty, yet the strategy stifles short-term flexibility.
Other drivers and restraints analyzed in the detailed report include:
- Sustainability Rules Mandating More Than 30% PCR Content
- Rapid Adoption Of Refill-At-Home Dispensing Formats
- Single-Use Plastics Bans Across The EU And Select US States
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastics generated 41.12% of 2025 revenue and, aided by PCR and bio-resin integration, are on track for the fastest 4.89% CAGR to 2031, reinforcing their primacy in the personal care packaging market. Polyethylene pouches and squeeze tubes dominate because chemical resistance and heat-seal strength align with concentrate refills, while polypropylene excels in closures and pumps that require fatigue resilience. PET maintains share for clear rigid bottles that protect fragrances, even as PVC recedes under European phase-out pressure tied to plasticizer migration. Sugarcane-based polyethylene and corn-origin PLA pick up 3% of the plastics segment, favored by brands willing to pay double-digit premiums to flag sustainability on-pack.
Glass, accounting for 22% in 2025, wins in prestige fragrance where heft signals craftsmanship, yet e-commerce breakage and higher freight hinder volume scaling. Aluminum's 18% foothold, driven by deodorant aerosols and travel formats, benefits from narratives of infinite recyclability. Paperboard's 19% share centers on folding cartons that tell brand stories, though moisture sensitivity curtails primary-pack usage. Together, these dynamics keep plastics at the core of the personal care packaging market, but rising bio-derived options broaden material choices and encourage converters to diversify their extruder portfolios.
Rigid units accounted for 62.76% of the 2025 value and maintain dominance due to established filling-line infrastructure and shelf presence vital to skin and hair care. Integrated pumps and aerosol valves bolster brand trust through precise dosing, supporting higher price points within the personal care packaging market. Flexible packs, the remaining 37.24%, outpace the market at 4.51% CAGR, fueled by e-commerce durability, material-weight savings of up to 70%, and regulatory eco-modulation fees that penalize heavy, rigid items.
Amcor's dual-wall pouch that merges barrier and cushioning layers proves the next step, eliminating separate inserts while halving breakage claims. Refill platform preferences further tilt toward flexible concentrates, as multi-use pouches amortize freight emissions across several bathroom cycles. Meanwhile, rigid producers mitigate share erosion by pushing lightweighting and tethered-cap compliance to satisfy EU directives without sacrificing consumer familiarity.
Complete Report Scope:
- By Material Type
- Plastic
- Polyethylene
- Polypropylene
- PET and PVC
- Polystyrene
- Bio-Based Plastics
- Other Plastic Material Types
- Glass
- Metal
- Paper and Paperboard
- Plastic
- By Packaging Format
- Flexible
- Rigid
- By Product Type
- Bottles and Jars
- Tubes and Sticks
- Pumps and Dispensers
- Pouches and Sachets
- Caps and Closures
- Other Product Types
- By Application
- Skin Care
- Hair Care
- Oral Care
- Make-Up Products
- Deodorants and Fragrances
- Baby Care
- Other Applications
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific held 33.37% in 2025 and remains the anchor of the personal care packaging market. China's premium fragrance launches adopt refillable glass to court eco-minded shoppers, while India's urban consumers trade up to metallized pumps across skin and hair care. Southeast Asia's double-digit growth in male grooming drives aluminum aerosol can lines, while Japan's aging society supports anti-aging airless dispensers. South Korea's export-oriented K-beauty labels specify moisture-barrier pouches that withstand tropical transits, and Australia moves early on 30% PCR mandates, serving as a proving ground for traceability tech before Asia-wide rollout.
Europe controlled 28% in 2025, shaped by strict PCR quotas, tethered-cap rules, and eco-label audits that force converters into chemical-recycling alliances. Germany and France scale in-store refill aisles, cutting per-use material by 70% and binding shoppers to durable containers. Italy and Spain rely on glass flacons to express luxury in fragrance clusters, but freight and breakage temper unit growth. Eastern Europe, led by Poland, attracts converter nearshoring that pairs lower labor cost with regional proximity, adding tube and closure capacity for Western brands.
North America contributed 22% of revenue in 2025, with US omni-channel demands spurring packs that move from shelf to doorstep without extra void fill. Canada's phased single-use plastics ban accelerates mono-material flexibles and paperboard. Mexico's nearshored capacity alleviates tariff and lead-time constraints for US brands. Divergent state laws, notably California's SB 54 and Washington's packaging tax, raise complexity, prompting nationwide adoption of the toughest standard to avoid fragmented portfolios.
South America, forecast to rise 5.08% CAGR through 2031, benefits from Brazil's refillable glass initiatives and Argentina's aspirational urban buyers who invest income in imported fragrances that command elevated pack values. The Middle East, at 8%, focuses on ornate glass and metallized closures for luxury scents, with Turkey as a converter hub. Africa's 7% share of the market relies heavily on sachets for affordability, yet municipal bans on single-use plastics are nudging markets toward resealable, multi-use pouches.
- Albea S.A.
- HCP Packaging Group
- Gerresheimer AG
- Amcor plc
- AptarGroup, Inc.
- Cosmopak USA LLC
- Quadpack Industries, S.A.
- Libo Cosmetics Co., Ltd.
- Mpack Poland sp. z o.o.
- POLITECH SP. Z O.O.
- Rieke Corporation (TriMas Corporation)
- Berlin Packaging LLC
- MKTG Industry SRL
- Silgan Holdings, Inc.
- Stoelzle Oberglas GmbH
- EPL Limited
- Verescence Inc.
- Apackaging Group LLC
- Heinz-Glass GmbH & Ko. KGaA
- Roetell Group
- Vitro SAB De CV
- Vidraria Anchieta Ltda.
- Lumson S.p.A
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Premiumization of Beauty SKUs in Emerging Markets
- 4.2.2 Omni-Channel Fulfilment Driving Protective and Ship-Ready Packs
- 4.2.3 Sustainability Rules Mandating More Than 30% PCR Content
- 4.2.4 Rapid Adoption of Refill-at-Home Dispensing Formats
- 4.2.5 Edge-AI Enabled Filling Lines Cutting SKU Cost
- 4.2.6 Explosive Growth of Male Grooming in Southeast Asia
- 4.3 Market Restraints
- 4.3.1 Volatile Polyolefin and PET Feedstock Prices
- 4.3.2 Single-Use Plastics Bans Across the EU and Select US States
- 4.3.3 Supply-Chain Chokepoints in Aluminium and Glass
- 4.3.4 Rise of Solid-Format Toiletries Replacing Primary Packs
- 4.4 Industry Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Plastic
- 5.1.1.1 Polyethylene
- 5.1.1.2 Polypropylene
- 5.1.1.3 PET and PVC
- 5.1.1.4 Polystyrene
- 5.1.1.5 Bio-Based Plastics
- 5.1.1.6 Other Plastic Material Types
- 5.1.2 Glass
- 5.1.3 Metal
- 5.1.4 Paper and Paperboard
- 5.1.1 Plastic
- 5.2 By Packaging Format
- 5.2.1 Flexible
- 5.2.2 Rigid
- 5.3 By Product Type
- 5.3.1 Bottles and Jars
- 5.3.2 Tubes and Sticks
- 5.3.3 Pumps and Dispensers
- 5.3.4 Pouches and Sachets
- 5.3.5 Caps and Closures
- 5.3.6 Other Product Types
- 5.4 By Application
- 5.4.1 Skin Care
- 5.4.2 Hair Care
- 5.4.3 Oral Care
- 5.4.4 Make-Up Products
- 5.4.5 Deodorants and Fragrances
- 5.4.6 Baby Care
- 5.4.7 Other Applications
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 France
- 5.5.3.3 United Kingdom
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Egypt
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Albea S.A.
- 6.4.2 HCP Packaging Group
- 6.4.3 Gerresheimer AG
- 6.4.4 Amcor plc
- 6.4.5 AptarGroup, Inc.
- 6.4.6 Cosmopak USA LLC
- 6.4.7 Quadpack Industries, S.A.
- 6.4.8 Libo Cosmetics Co., Ltd.
- 6.4.9 Mpack Poland sp. z o.o.
- 6.4.10 POLITECH SP. Z O.O.
- 6.4.11 Rieke Corporation (TriMas Corporation)
- 6.4.12 Berlin Packaging LLC
- 6.4.13 MKTG Industry SRL
- 6.4.14 Silgan Holdings, Inc.
- 6.4.15 Stoelzle Oberglas GmbH
- 6.4.16 EPL Limited
- 6.4.17 Verescence Inc.
- 6.4.18 Apackaging Group LLC
- 6.4.19 Heinz-Glass GmbH & Ko. KGaA
- 6.4.20 Roetell Group
- 6.4.21 Vitro SAB De CV
- 6.4.22 Vidraria Anchieta Ltda.
- 6.4.23 Lumson S.p.A
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment