

|
시장보고서
상품코드
2122006
중동 및 아프리카의 플라스틱 포장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Middle East And Africa Plastic Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 중동 및 아프리카의 플라스틱 포장 시장 규모는 2025년 263억 9,000만 달러, 2026년 268억 달러에서 2031년까지 304억 1,000만 달러에 이르고, 2026-2031년 연평균 복합 성장률(CAGR)은 2.56%를 기록할 전망입니다.
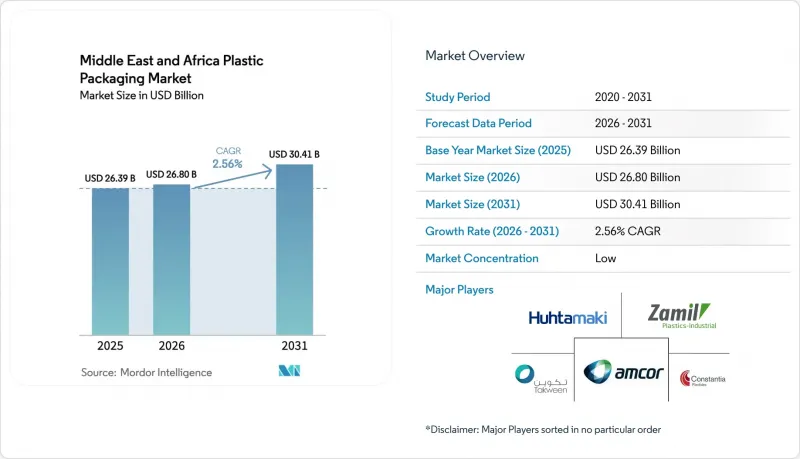
본 보고서는 소재 유형(폴리에틸렌, 폴리프로필렌 등), 포장 유형(연포장, 경질 포장 등), 제품 형태(트레이·용기 등),최종 사용자 산업(식품, 음료, 의약품 및 헬스케어 등), 제조 공정(압출 성형, 사출 성형 등), 그리고 국가별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
중동 및 아프리카의 플라스틱 포장 시장 동향 및 인사이트
가공 식품에 대한 수요의 꾸준한 증가
도시로의 인구 이동, 맞벌이 가정 증가, 그리고 기후 변화로 인한 식품 안전에 대한 우려로 인해, 해당 지역 전체에서 밀폐성이 높고 분량이 관리된 식료품 라인에 대한 수요가 증가하고 있습니다. 슈퍼마켓 체인은 진열 공간을 개별 판매되는 주식에서 미리 포장된 육류, 유제품, 스낵류로 전환하고 있으며, 이로 인해 주변 온도 40°C 이하에서 저장 기간을 연장하는 다층 배리어 필름 수요가 견인되고 있습니다. 사우디아라비아는 이미 서유럽 수준에 근접한 포장 식품 소비 수준을 보이고 있지만, 나이지리아 시장 침투율은 15% 미만에 그치고 있어 새로운 생산 능력 확대의 여지가 크다는 것이 드러나고 있습니다. 각 변환 업체들은 부패를 방지하고 매장에서의 폐기물을 줄여주는 가스 치환 포장 소포장 및 진공 스킨 트레이를 제공함으로써 이러한 수요에 대응하고 있습니다. 유통망이 지방 도시까지 확대됨에 따라, 소형 파우치를 통해 소매업체는 합리적인 가격과 위생 면의 균형을 맞출 수 있게 되었으며, 중동 및 아프리카의 플라스틱 포장 시장에서 연질 플라스틱 솔루션의 채택이 더욱 가속화되고 있습니다.
전자상거래 주문 처리용 포장의 성장 가속화
2024년, 온라인 소매는 30%의 성장률을 기록하며, 걸프 지역 노동력의 대부분을 차지하는 35세 미만 소비자층에 힘입어 다른 판매 채널을 능가하는 성장을 이어가고 있습니다. 울퉁불퉁한 도로와 여러 차례의 수거가 수반되는 불안정한 공급 경로는 파손 위험을 높이며, 물류 사업자들은 완충재 층을 지나치게 두껍게 할 수밖에 없는 상황에 몰리고 있습니다. 경량 플로우랩, 에어필로우, 스트레치 필름은 운송비를 과도하게 끌어올리지 않으면서 주문 상품을 보호해 주며, 라스트 마일 배송에서 플라스틱 제품의 보급을 더욱 촉진하고 있습니다. 나이지리아의 전자상거래 시장만 해도 2023년부터 2028년 사이에 57억 1,000만 달러의 매출 증가가 예상되며, 이는 보호 필름이나 기포 봉투가 필요한 소포가 수백만 개 증가할 것임을 의미합니다. 두바이와 리야드의 퀵 커머스 플랫폼에서는 온도 관리 배송이라는 새로운 흐름이 도입되어, 스티로폼 라이너와 진공 패널의 활용 확대를 뒷받침하고 있습니다. 이러한 동향들이 결합되어 중동 및 아프리카의 플라스틱 포장 시장에서 평균을 상회하는 출하량 증가를 뒷받침하고 있습니다.
걸프 국가들의 일회용 플라스틱 금지 조치 확산
아랍에미리트(UAE)는 2024년 연방 법령 제36호를 시행하여, 2026년 1월부터 일회용 봉투, 식기, 빨대를 금지하고, 2028년까지 벌금을 단계적으로 인상할 예정입니다. 사우디아라비아도 ‘그린 이니셔티브’에 따라 유사한 의향을 보이고 있지만, 시행 시기는 미정이어서 가공업체들에게 투자 불확실성을 안겨주고 있습니다. 퇴비화 가능한 수지공급은 이제 막 시작되었으며, 가격은 기존 폴리에틸렌보다 40% 비싸 중소기업에게는 비용 면에서 장벽이 되고 있습니다. 일회용 제품에 맞추어 조정된 압출 성형 및 사출 성형 라인의 자산 감가상각 가능성이 이익률을 위협하고 있습니다. 그럼에도 불구하고, 이러한 금지 조치는 제품 포트폴리오를 재사용 가능하거나 인증된 재활용 가능한 형태로 전환하는 것을 촉진하며, 궁극적으로는 중동 및 아프리카의 플라스틱 포장 시장 전체에 더 높은 사양 기준을 정착시키는 결과로 이어질 것입니다.
부문 분석
2025년 중동 및 아프리카의 플라스틱 포장 시장에서 폴리에틸렌은 39.32%의 시장 점유율을 차지하고 있습니다. 이는 비용 면에서의 우위뿐만 아니라 블로우 성형, 사출 성형, 회전 성형과 같은 다양한 제조 공정에서의 범용성 덕분입니다. 선형 저밀도 폴리에틸렌(LLDPE)은 먼지가 많은 고속도로를 주행하는 팔레트를 고정하는 스트레치 랩 및 수축 필름 분야를 주도하고 있는 반면, 고밀도 폴리에틸렌(HDPE)은 내화학성이 요구되는 세제나 윤활유 병 분야를 선도하고 있습니다. 폴리프로필렌은 특히 테더가 부착된 캡에 대한 규제가 확산됨에 따라 캡 및 직물 봉투 분야에서 여전히 매력적인 소재이지만, 재활용 경로는 PET에 비해 뒤처져 있습니다. PET는 연평균 성장률(CAGR) 3.56%로 확대되어 중동 및 아프리카의 플라스틱 포장 시장 전체의 성장률을 상회할 것으로 예측됩니다. 인드라마 벤처스는 2024년, 상부 하중 강도를 유지하면서 프리폼의 질량을 15% 줄인 경량 PET 병을 출시하여, 이를 통해 수지 사용량과 운송 시 배출량을 저감했습니다. 고온 충전 음료 라인에서는 폴리에틸렌과 달리 85°C의 살균 처리에서도 변형되지 않기 때문에 PET가 선호되고 있습니다. 남아프리카와 케냐의 확대 생산자 책임(EPR) 제도에서는 재활용이 불가능한 용기에 대해 더 높은 수수료가 부과되므로, 브랜드 소유주들은 PET로의 전환을 추진하고 있습니다.
폴리에틸렌의 회복력은 사우디아라비아의 대형 석유화학 기업이 현지 원료를 공급함으로써 뒷받침되고 있으며, 이를 통해 적시 공급과 가격 면에서의 우위가 확보되고 있습니다. 폴리프로필렌은 유제품 및 커피 분야의 사출 성형 재밀봉 가능 뚜껑에 대한 수요 증가의 혜택을 받고 있습니다. 폴리스티렌의 틈새 시장은 단열 식품 용기 및 보호용 완충재를 아우르고 있으나, 규제 당국은 그 미세화 추세를 엄격히 감시하고 있습니다. 한편, 재활용성을 높이기 위해 단일 소재의 PET 뚜껑용 필름이 즉석식사용 트레이에 채택되기 시작했습니다. 재생재 함유율 기준이 엄격해지는 가운데, 가공업체들은 자사 공급망을 통한 폴리에틸렌의 안정적인 공급과 PET의 재활용성에 대한 최종 시장의 선호도 사이의 균형을 신중하게 검토하고 있습니다. 이러한 경쟁으로 인해 PET가 점진적인 성장을 이루고 있음에도 불구하고, 두 폴리머는 중동 및 아프리카의 플라스틱 포장 시장에서 여전히 중심적인 위치를 차지하고 있습니다.
연포장 시장은 2025년에 55.62%의 점유율을 차지할 것으로 예상되며, 무게 대비 효율이 뛰어나고 운송 시 환경 부하가 적다는 점을 반영하여 연평균 성장률(CAGR) 3.87%를 나타낼 것으로 전망됩니다. 스탠드업 파우치는 유리병에 비해 매립 폐기물 양을 줄이고 운송 시 배출량을 절반으로 줄이는 특징이 있어, 소매업체의 마케팅에서 친환경 점수(에코 스코어)를 높이는 데 크게 활용되고 있습니다. 후타마키사는 2024년에 아랍에미리트(UAE) 거점을 재편하고 5층 공압출 설비를 통합했습니다. 이는 생산 능력 향상과 얇은 두께 구현을 위한 경쟁이 격화되고 있음을 시사합니다. 경질 용기는 소스, 스프레드, 가정용 세제 등의 분야에서 여전히 중요한 위치를 차지하고 있으며, 이러한 제품의 경우 용량 조절과 촉감을 통한 브랜딩이 구매 결정에 영향을 미치고 있습니다. 그럼에도 불구하고, 화장품용 소포장, 영양 보조제 분말, 밀키트의 택배 배송 수요 증가로 인해 플로우랩 및 메일러 필름의 필요성이 커지고 있습니다. 따라서 중동 및 아프리카의 연포장 시장 규모는 경질 용기에 비해 확대 추세를 유지할 전망입니다.
경질 용기는 진열 시의 임팩트와 위조 방지가 중요한 음료, 요거트, 비타민제 분야에서 여전히 주류를 이루고 있습니다. PET 병의 사출 신장 블로우 성형은 투명성과 내균열성을 확보하고 있으며, 이는 특히 걸프 지역의 여행 소매 채널에서 판매되는 프리미엄 주스에 있어 중요합니다. 블로우 성형된 고밀도 폴리에틸렌 제리캔은 위험물로 유엔 인증이 필요한 농약이나 모터 오일을 안전하게 보관합니다. 하이브리드 설계는 기존의 경계를 모호하게 만들고 있습니다. 얇은 폴리에틸렌 라이너에 종이 튜브 슬리브를 접합한 구조를 통해 브랜드 소유자는 재활용성을 저해하지 않으면서 강성과 인쇄 적합성을 향상시킬 수 있습니다. 이러한 이중 전략을 통해 변환업체는 규제 준수 및 소비자 편의성이라는 상반된 요구에 대응하면서도 이익률을 유지할 수 있게 됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.10According to Mordor Intelligence, the Middle East and Africa plastic packaging market size is projected to expand from USD 26.39 billion in 2025 and USD 26.80 billion in 2026 to USD 30.41 billion by 2031, registering a CAGR of 2.56% between 2026 to 2031.
This report is Segmented by Material Type (Polyethylene, Polypropylene, and More), Packaging Type (Flexible, and Rigid), Product Form (Trays and Containers, and More), End-User Industry (Food, Beverage, Pharmaceuticals and Healthcare, and More), Manufacturing Process (Extrusion, Injection Molding, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Middle East And Africa Plastic Packaging Market Trends and Insights
Steady Rise in Demand for Processed Food
Urban migration, rising dual-income households, and climate-driven food-safety concerns lift demand for hermetically sealed, portion-controlled grocery lines across the region. Supermarket chains shift shelf space from loose staples to pre-packed meats, dairy, and snacks, pulling through multilayer barrier films that extend shelf life under 40 °C ambient temperatures. Saudi Arabia already approaches Western European packaged-food consumption benchmarks, while Nigeria's penetration lags below 15%, indicating significant headroom for new capacity. Converters respond with modified-atmosphere sachets and vacuum-skin trays that curb spoilage and shrink in-store waste. As distribution networks reach second-tier cities, small-format pouches allow retailers to balance affordability with hygiene, reinforcing adoption of flexible plastic solutions within the Middle East and Africa plastic packaging market.
Accelerating Growth of E-Commerce Fulfilment Packaging
Online retail expanded at 30% in 2024 and continues to outpace other channels, driven by consumers under 35 who dominate the Gulf workforce. Fragile supply routes that involve bumpy roads or multiple hand-offs increase breakage risk, pushing logistics operators to over-specify cushioning layers. Lightweight flow-wraps, air pillows, and stretch films safeguard orders without unduly raising freight costs, deepening penetration of plastics in last-mile distribution. Nigerian e-commerce alone is expected to add USD 5.71 billion in sales between 2023 and 2028, translating into millions of additional parcels that demand protective films and bubble mailers. Quick-commerce platforms in Dubai and Riyadh introduce a parallel stream for temperature-controlled shipments, spurring uptake of expanded polystyrene liners and vacuum panels. These dynamics collectively underpin above-average volume growth for the Middle East and Africa plastic packaging market.
Emerging Gulf Single-Use Plastic Bans
The United Arab Emirates enforces Federal Decree-Law 36 of 2024, prohibiting single-use bags, cutlery, and straws from January 2026, with escalating fines through 2028. Saudi Arabia signals similar intent under its Green Initiative, though timelines remain fluid, generating investment uncertainty for converters. Compostable resin supply is nascent and priced 40% above conventional polyethylene, raising cost barriers for smaller firms. The possibility of asset write-offs on extrusion and injection lines tuned for single-use products threatens margins. Nonetheless, bans catalyze portfolio pivots toward reusable or certified-recyclable formats, ultimately embedding higher specification standards across the Middle East and Africa plastic packaging market.
Other drivers and restraints analyzed in the detailed report include:
- Sovereign Wealth-Fund Backing for Recycling Capacity
- Expanding Regional Healthcare Infrastructure
- High Raw-Material Costs and Limited Recycling Infrastructure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene holds a 39.32% market share in the Middle East and Africa plastic packaging market in 2025, driven by its cost advantages and versatility across blown-film, injection, and rotational molding operations. Linear low-density polyethylene dominates the stretch-wrap and shrink-film segments that secure pallets traveling on dusty highways, while high-density polyethylene leads the way in detergent and lubricant bottles, which require chemical resistance. Polypropylene remains attractive for closures and woven sacks, particularly as tethered-cap regulations gain traction, although its recycling pathways lag behind those of PET. PET is forecast to expand at a 3.56% CAGR, surpassing the overall Middle East and Africa plastic packaging market. Indorama Ventures launched a lightweight PET bottle in 2024 that reduces preform mass by 15% while maintaining top-load strength, thereby lowering resin use and freight emissions. Hot-fill beverage lines prefer PET because it withstands 85 °C pasteurization without warping, unlike polyethylene. Extended producer responsibility schemes in South Africa and Kenya impose steeper fees on non-recyclable formats, prompting brand owners to shift toward PET.
Polyethylene's resilience rests on local feedstock from Saudi petrochemical giants, ensuring timely supply and price leverage. Polypropylene benefits from growing demand for injection-molded reclosable lids in dairy and coffee. Polystyrene's niche covers insulated food containers and protective cushioning, yet regulators scrutinize its micro-fragmentation tendencies. Meanwhile, mono-material PET lidding films enter ready-meal trays to improve recyclability. As recycled-content quotas tighten, converters weigh the security of captive polyethylene supply against end-market preference for PET circularity. This competitive interplay keeps both polymers central to the Middle East and Africa plastic packaging market, even as PET captures incremental growth.
Flexible packaging commanded 55.62% share in 2025 and is projected to record a 3.87% CAGR, reflecting its weight efficiency and low shipping footprint. Stand-up pouches reduce landfill volumes and cut transportation emissions in half compared to glass jars, an attribute that retailers' marketing eco-scores leverage heavily. Huhtamaki rationalized its United Arab Emirates sites in 2024 to pool five-layer coextrusion assets, signaling a race toward higher throughput and thinner gauges. Rigid containers maintain relevance in sauces, spreads, and household cleansers where controlled dispensing and tactile branding influence purchase decisions. Nonetheless, the rising demand for courier shipments of cosmetics sachets, nutraceutical powders, and meal kits amplifies the need for flow-wraps and mailer films. The Middle East and Africa plastic packaging market size for flexible formats will, therefore, remain on an expansion path relative to rigid counterparts.
Rigid solutions still dominate beverages, yogurts, and vitamins, where shelf impact and tamper evidence are critical. Injection stretch blow moulding of PET bottles ensures clarity and crack resistance, particularly important for premium juices sold across the Gulf's travel retail channel. Blow-molded high-density polyethylene jerrycans secure agrochemicals and motor oils that require UN-certification for hazardous goods. Hybrid designs blur boundaries; paperboard sleeves bonded to thin polyethylene liners give brand owners improved stiffness and printability without compromising recyclability. The dual strategy allows converters to safeguard margins while meeting opposing pressures of regulatory compliance and consumer convenience.
Complete Report Scope:
- By Material Type
- Polyethylene (PE)
- Polypropylene (PP)
- Polyethylene Terephthalate (PET)
- Polystyrene and EPS
- Other Material Types
- By Packaging Type
- Flexible Plastic Packaging
- Rigid Plastic Packaging
- By Product Form
- Bottles and Jars
- Trays and Containers
- Pouches and Sachets
- Bags and Sacks
- Films and Wraps
- Other Product Forms
- By End-User Industry
- Food
- Beverage
- Pharmaceuticals and Healthcare
- Cosmetics and Personal Care
- Industrial
- Other End-user Industries
- By Manufacturing Process
- Extrusion
- Injection Molding
- Blow Molding
- Thermoforming
- Other Manufacturing Processes
- By Region
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- Middle East
List of Companies Covered in this Report:
- Zamil Plastic Industries Co.
- Huhtamaki South Africa (Pty) Ltd
- Takween Advanced Industries
- Napco National
- Constantia Flexibles Afripack
- Packaging Products Company (PPC)
- PrimePak Industries Nigeria Ltd (Enpee Group)
- Al Bayader International (H and H Group of Companies)
- Falcon Pack
- Arabian Flexible Packaging LLC
- Hotpack Packaging Industries LLC
- ENPI Group
- Gulf East Paper and Plastic Industries LLC
- Obeikan Investment Group (OIG Packaging)
- Sealed Air Corporation
- Taghleef Industries
- Alpla Group
- Greif Inc.
- RPC M&H Plastics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demand for Oxo-Degradable Plastics
- 4.2.2 Steady Rise in Demand for Processed Food
- 4.2.3 Accelerating Growth of E-Commerce Fulfilment Packaging
- 4.2.4 Expanding Regional Healthcare Infrastructure
- 4.2.5 Sovereign Wealth-Fund Backing for Recycling Capacity
- 4.2.6 Adoption of High-Barrier Films for Hot-Fill Beverages
- 4.3 Market Restraints
- 4.3.1 Environmental Concerns Over Recycling and Safe Disposal
- 4.3.2 High Raw-Material Costs and Limited Recycling Infrastructure
- 4.3.3 Emerging Gulf Single-Use Plastic Bans
- 4.3.4 Currency Volatility Impacting Polymer Resin Imports
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Recycling and Sustainability Landscape
- 4.7 Technological Outlook
- 4.8 Regulatory Landscape
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Bargaining Power of Suppliers
- 4.9.2 Bargaining Power of Consumers
- 4.9.3 Threat of New Entrants
- 4.9.4 Threat of Substitute Products
- 4.9.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Polyethylene (PE)
- 5.1.2 Polypropylene (PP)
- 5.1.3 Polyethylene Terephthalate (PET)
- 5.1.4 Polystyrene and EPS
- 5.1.5 Other Material Types
- 5.2 By Packaging Type
- 5.2.1 Flexible Plastic Packaging
- 5.2.2 Rigid Plastic Packaging
- 5.3 By Product Form
- 5.3.1 Bottles and Jars
- 5.3.2 Trays and Containers
- 5.3.3 Pouches and Sachets
- 5.3.4 Bags and Sacks
- 5.3.5 Films and Wraps
- 5.3.6 Other Product Forms
- 5.4 By End-User Industry
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Pharmaceuticals and Healthcare
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Industrial
- 5.4.6 Other End-user Industries
- 5.5 By Manufacturing Process
- 5.5.1 Extrusion
- 5.5.2 Injection Molding
- 5.5.3 Blow Molding
- 5.5.4 Thermoforming
- 5.5.5 Other Manufacturing Processes
- 5.6 By Region
- 5.6.1 Middle East
- 5.6.1.1 Saudi Arabia
- 5.6.1.2 United Arab Emirates
- 5.6.1.3 Rest of Middle East
- 5.6.2 Africa
- 5.6.2.1 South Africa
- 5.6.2.2 Egypt
- 5.6.2.3 Nigeria
- 5.6.2.4 Rest of Africa
- 5.6.1 Middle East
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Zamil Plastic Industries Co.
- 6.4.2 Huhtamaki South Africa (Pty) Ltd
- 6.4.3 Takween Advanced Industries
- 6.4.4 Napco National
- 6.4.5 Constantia Flexibles Afripack
- 6.4.6 Packaging Products Company (PPC)
- 6.4.7 PrimePak Industries Nigeria Ltd (Enpee Group)
- 6.4.8 Al Bayader International (H and H Group of Companies)
- 6.4.9 Falcon Pack
- 6.4.10 Arabian Flexible Packaging LLC
- 6.4.11 Hotpack Packaging Industries LLC
- 6.4.12 ENPI Group
- 6.4.13 Gulf East Paper and Plastic Industries LLC
- 6.4.14 Obeikan Investment Group (OIG Packaging)
- 6.4.15 Sealed Air Corporation
- 6.4.16 Taghleef Industries
- 6.4.17 Alpla Group
- 6.4.18 Greif Inc.
- 6.4.19 RPC M&H Plastics
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


