

|
시장보고서
상품코드
2122161
심혈관 중재시술 디바이스 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Interventional Cardiology Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
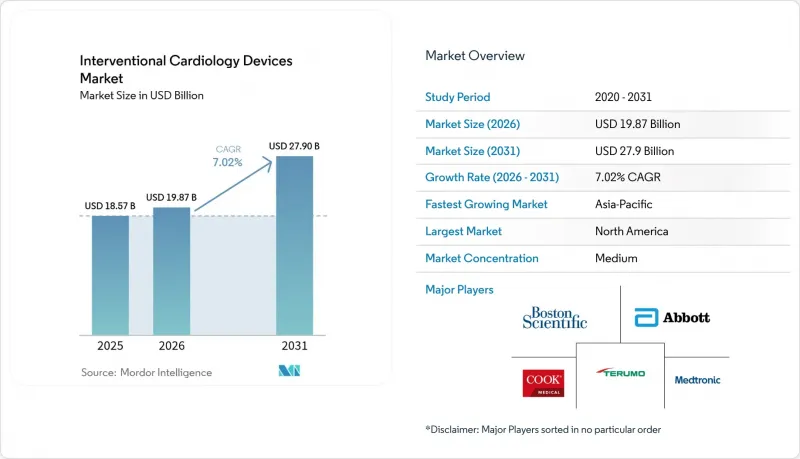
에 따르면 심혈관 중재시술 디바이스 시장 규모는 2025년에 185억 7,000만 달러로 평가되며, 2026년 198억 7,000만 달러에서 2031년까지 279억 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 7.02%에 달할 전망입니다.
이 보고서는 제품 유형(관상동맥 스텐트[베어메탈 스텐트 등], 카테터[혈관조영 카테터 등], PTCA 풍선, 가이드와이어 등), 최종사용자(병원, 외래 수술 센터 등), 소재(코발트·크롬 합금, 니티놀 등),지역(북미, 유럽 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 심혈관 중재 시술 기기 시장의 동향 및 인사이트
관상동맥질환(CAD) 및 PCI 시술 유병률 증가
관상동맥질환(CAD)은 여전히 전 세계 주요 사망 원인이며, 미국에서만 2,000만 명 이상의 성인이 이 질환을 앓고 있습니다. 고령화, 비만, 그리고 앉아 있는 생활 습관으로 인해 특히 IVL 치료의 혜택을 받는 다지병변이나 복잡한 석회화 병변에 대한 시술 수요가 증가하고 있습니다. 아시아태평양에서는 도시화에 따라 식생활과 활동 패턴이 변화함에 따라 시장이 가장 급격하게 확대되고 있습니다. 관상동맥질환(CAD)이 만성질환으로 관리되게 되면서 재시술이 전체 시술 건수에서 차지하는 비중이 증가하고 있으며, 일회성 치료를 넘어 기기 사용이 지속되고 있습니다.
저침습 치료로의 전환 가속화
병원과 보험사는 입원 기간을 단축하고 합병증을 줄여주는 경피적 접근법을 선호하고 있습니다. COVID-19 팬데믹은 이러한 추세를 더욱 강화하여 약물 방출형 풍선 및 생체흡수성 스캐폴드의 도입을 촉진했습니다. AI를 활용한 영상 진단은 정확도를 높이고 조영제 부하를 줄여, 과거 개흉 수술에서는 고위험군으로 여겨졌던 고령자나 동반 질환이 있는 환자의 적응증 범위를 확대하고 있습니다.
각 지역의 엄격한 규제 절차
EU의 의료기기 규정(MDR)에서는 더욱 엄격한 임상 데이터와 시판 후 조사가 요구되고 있으며, 시장 출시까지의 기간과 규정 준수 비용이 증가하고 있습니다. 동시에 미국에서는 몇 건의 클래스 I 사고를 계기로 리콜에 대한 감독이 강화되고 있습니다. 지역별로 상이한 요건으로 인해 제조사는 병행하여 승인 절차를 진행해야만 하며, 이는 중소 혁신 기업에게 큰 부담이 되고 있습니다.
부문 분석
관상동맥 스텐트는 경피적 중재술에 대한 지속적인 수요에 힘입어 2025년에는 심혈관 중재술 기기 시장의 40.86%를 차지하며 가장 큰 매출을 창출했습니다. IVL 플랫폼은 아직 발전 단계에 있지만, 2031년까지 연평균 성장률(CAGR) 10.75%로 확대될 것으로 예측됩니다. 중증 석회화 병변에 대한 경피적 치료가 더욱 빈번해짐에 따라 IVL 기술을 이용한 심혈관 중재 시술 기기 시장의 규모는 현저히 확대될 것으로 전망됩니다. 초박형 스트럿형 약물 방출 스텐트 및 차세대 생체흡수성 스캐폴드는 재협착을 줄이고 생리적인 혈관 치유를 촉진합니다. 베어메탈 스텐트는 현재 단기 이중 항혈소판 요법이 필요한 환자에게만 사용되고 있습니다. PTCA용 풍선 및 가이드와이어는 안정적인 판매량 증가세를 유지하고 있으며, 2024년 Agent 플랫폼이 FDA 승인을 받은 것을 계기로 스텐트내 재협착 관리 분야에서 약물 코팅 풍선이 주목받고 있습니다.
IVUS 및 OCT 카테터와 같은 시술 보조 기기는 AI 기반 오버레이 기술의 활용을 통해 병변 평가 정확도가 향상되고, 기기 크기 선정이 최적화되고 있습니다. 시술 후 즉시 보행이 가능하게 하는 지혈 기기는 당일 퇴원 프로토콜에 필수적인 요소로 자리 잡고 있습니다. 이러한 혁신 기술이 결합되어 시술 효율을 높이고, PCI의 임상적 적용 범위를 확대하고 있습니다.
지역별 분석
북미는 광범위한 보험 적용, 견고한 임상 연구 네트워크, 그리고 AI 기반 영상 진단의 급속한 보급을 배경으로 2025년에는 매출의 41.25%를 차지하며 심혈관 중재 시술 기기 시장을 주도했습니다. 이 지역은 복잡한 PCI에 ASC(외래 수술 센터)를 도입하고 당일 퇴원을 선도하고 있지만, FDA의 리콜 감시가 강화되고 카테터실 인력 부족으로 인해 성장이 억제되고 있습니다. 유럽은 성숙해 가면서도 혁신에 우호적인 시장으로 그 뒤를 잇고 있으며, 지속가능성에 대한 노력이 생체흡수성 스텐트와 저탄소 공급망을 지원하고 있습니다. MDR(의료기기 규정) 준수 비용이 중소 제조업체의 부담이 되고 있지만, 독일과 프랑스에서는 차세대 의료기기의 조기 인체 사용 시험이 계속해서 진행되고 있습니다.
아시아태평양은 예측 연평균 성장률(CAGR) 12.05%라는 눈에 띄는 성장 동력이 되고 있습니다. 중국에서는 공적 보험의 확대와 병원 건설 붐으로 인해 PCI 건수가 증가하고 있는 반면, 인도에서는 가격 상한선이 설정된 환경 속에서 현지 생산을 기반으로 한 비용 대비 효율이 높은 DES 플랫폼이 우위를 점하고 있습니다. 일본에서는 엄격한 승인 절차로 인해 제품 출시 속도가 둔화되고 있지만, 승인이 나면 프리미엄 가격으로 판매할 수 있습니다. 한국과 호주는 높은 시술 품질과 AI의 조기 도입을 특징으로 하며, 이를 통해 제2의 혁신 허브로서의 입지를 확립하고 있습니다. 이러한 동향들이 맞물려 심혈관 중재 시술 기기 시장에서 지역의 경쟁력 구도를 재편하고, 향후 수입원의 재분배를 가져올 것으로 전망됩니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, the interventional cardiology devices market size was valued at USD 18.57 billion in 2025 and estimated to grow from USD 19.87 billion in 2026 to reach USD 27.9 billion by 2031, at a CAGR of 7.02% during the forecast period (2026-2031).
This report is Segmented by Product Type (Coronary Stents [Bare-Metal Stents, and More], Catheters [Angiography Catheters, and More], PTCA Balloons, Guide Wires, and More), End-User (Hospitals, Ambulatory Surgical Centers, and More), Material (Cobalt-Chromium Alloy, Nitinol, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Interventional Cardiology Devices Market Trends and Insights
Growing Prevalence of CAD & PCI Procedures
CAD remains the leading global cause of mortality, affecting more than 20 million adults in the United States alone. Aging populations, obesity and sedentary lifestyles are increasing procedural demand, particularly for multivessel disease and complex calcified lesions that benefit from IVL therapy. Asia-Pacific markets show the steepest rise as urbanization alters dietary and activity patterns. Re-interventions now constitute a larger portion of procedural volume because CAD is managed as a chronic condition, sustaining device utilization beyond single-episode care.
Accelerating Shift to Minimally Invasive Therapies
Hospitals and payers favor percutaneous approaches that shorten admissions and reduce complications. The COVID-19 pandemic reinforced this preference and catalyzed adoption of drug-eluting balloons and bio-resorbable scaffolds. AI-assisted imaging enhances precision, lowers contrast load and expands eligibility for elderly or comorbid patients once deemed high risk for open surgery.
Stringent Multi-Region Regulatory Pathways
EU Medical Device Regulation demands more rigorous clinical data and post-market surveillance, increasing time-to-market and compliance costs. Concurrently, the United States has heightened recall oversight after several Class I events. Divergent regional requirements force manufacturers to run parallel approval programs, straining smaller innovators.
Other drivers and restraints analyzed in the detailed report include:
- Continuous DES Price Erosion Expanding Addressable Pool
- AI-Augmented Pre-PCI Imaging & Decision Support Adoption
- Global Shortage of Cath-Lab Personnel & Interventional Cardiologists
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Coronary stents generated the largest revenue, holding 40.86% of the interventional cardiology devices market in 2025, supported by durable demand for percutaneous interventions. IVL platforms, although nascent, are forecast to advance at 10.75% CAGR through 2031. The interventional cardiology devices market size for IVL technology is expected to expand markedly as heavily calcified lesions become more frequently treated percutaneously. Ultra-thin-strut drug-eluting stents and next-generation bio-absorbable scaffolds reduce restenosis and facilitate physiologic vessel healing. Bare-metal stents are now reserved for patients requiring abbreviated dual antiplatelet therapy. PTCA balloons and guidewires maintain steady volume growth, with drug-coated balloons gaining attention for in-stent restenosis management following FDA approval of the Agent platform in 2024.
Procedural adjuncts such as IVUS and OCT catheters benefit from AI overlays that refine lesion assessment and optimize device sizing. Hemostasis devices that enable immediate ambulation are integral to same-day discharge protocols. Collectively, these innovations bolster procedural efficiency and extend the clinical reach of PCI.
Complete Report Scope:
- By Product Type
- Coronary Stents
- Bare-metal Stents
- Drug-eluting Stents
- Bio-absorbable Scaffolds
- Catheters
- Angiography Catheters
- IVUS/OCT Catheters
- PTCA Guiding Catheters
- PTCA Balloons
- Guidewires
- Hemostasis & Vascular Closure Devices
- Intravascular Lithotripsy (IVL) Systems
- Coronary Stents
- By End-user
- Hospitals
- Ambulatory Surgical Centers
- Cardiac Catheterization Labs
- By Material
- Cobalt-Chromium Alloy
- Platinum-Chromium Alloy
- Nitinol
- Polymer/Bio-resorbable
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led the interventional cardiology devices market with 41.25% revenue in 2025 on the back of broad insurance coverage, robust clinical research networks and rapid uptake of AI-guided imaging. The region is also pioneering ASC adoption and same-day discharge for complex PCI, although FDA recall vigilance and cath-lab staffing gaps temper growth. Europe follows as a mature yet innovation-friendly arena where sustainability initiatives encourage bio-resorbable scaffolds and lower-carbon supply chains. MDR compliance costs weigh on small manufacturers, but Germany and France continue to pilot early human use of next-generation devices.
Asia-Pacific is the standout growth engine with a 12.05% forecast CAGR. China's public insurance expansion and hospital construction boom are scaling PCI volumes, while India's price-capped environment favors cost-effective DES platforms anchored by local production. Japan's stringent approval process slows rollouts but commands premium pricing once clearance is secured. South Korea and Australia showcase high procedural quality and early AI integration, positioning them as secondary innovation hubs. Together these trends are set to re-shape regional competitive dynamics and redistribute future revenue pools within the interventional cardiology devices market.
- Abbott Laboratories
- Medtronic
- Boston Scientific
- B. Braun
- Terumo Corp.
- Biosensors International
- BIOTRONIK
- Cardinal Health
- Cook Group
- Koninklijke Philips
- Edwards Lifesciences Corp.
- Nano Therapeutics Pvt. Ltd.
- Shockwave Medical Inc.
- Merit Medical Systems
- Siemens Healthineers
- AngioDynamics
- C. R. Bard (BD)
- MicroPort Scientific Corp.
- Alvimedica
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Prevalence of CAD & PCI Procedures
- 4.2.2 Accelerating Shift To Minimally-Invasive Therapies
- 4.2.3 Continuous DES Price Erosion Expanding Addressable Pool
- 4.2.4 AI-Augmented Pre-PCI Imaging & Decision Support Adoption
- 4.2.5 Hospital Migration To Same-Day Discharge & ASC Settings
- 4.2.6 Sustainability Push For Fully Bio-Resorbable Platforms
- 4.3 Market Restraints
- 4.3.1 Stringent Multi-Region Regulatory Pathways
- 4.3.2 Availability Of Potent First-Line Pharmacotherapy
- 4.3.3 Global Shortage Of Cath-Lab Personnel & Interventional Cardiologists
- 4.3.4 Anti-Plastic Legislation Challenging Polymer-Based DES Supply Chain
- 4.4 Technological Outlook
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Coronary Stents
- 5.1.1.1 Bare-metal Stents
- 5.1.1.2 Drug-eluting Stents
- 5.1.1.3 Bio-absorbable Scaffolds
- 5.1.2 Catheters
- 5.1.2.1 Angiography Catheters
- 5.1.2.2 IVUS/OCT Catheters
- 5.1.2.3 PTCA Guiding Catheters
- 5.1.3 PTCA Balloons
- 5.1.4 Guidewires
- 5.1.5 Hemostasis & Vascular Closure Devices
- 5.1.6 Intravascular Lithotripsy (IVL) Systems
- 5.1.1 Coronary Stents
- 5.2 By End-user
- 5.2.1 Hospitals
- 5.2.2 Ambulatory Surgical Centers
- 5.2.3 Cardiac Catheterization Labs
- 5.3 By Material
- 5.3.1 Cobalt-Chromium Alloy
- 5.3.2 Platinum-Chromium Alloy
- 5.3.3 Nitinol
- 5.3.4 Polymer/Bio-resorbable
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 Medtronic PLC
- 6.3.3 Boston Scientific Corp.
- 6.3.4 B. Braun Melsungen AG
- 6.3.5 Terumo Corp.
- 6.3.6 Biosensors International
- 6.3.7 Biotronik SE & Co. KG
- 6.3.8 Cardinal Health Inc.
- 6.3.9 Cook Medical Inc.
- 6.3.10 Koninklijke Philips N.V.
- 6.3.11 Edwards Lifesciences Corp.
- 6.3.12 Nano Therapeutics Pvt. Ltd.
- 6.3.13 Shockwave Medical Inc.
- 6.3.14 Merit Medical Systems
- 6.3.15 Siemens Healthineers AG
- 6.3.16 AngioDynamics Inc.
- 6.3.17 C. R. Bard (BD)
- 6.3.18 MicroPort Scientific Corp.
- 6.3.19 Alvimedica
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment


