|
시장보고서
상품코드
2122176
바이오로직스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Biologics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
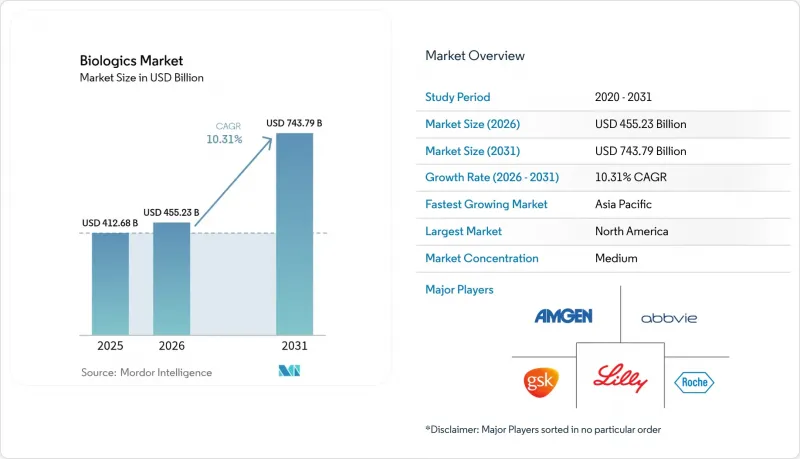
에 의하면, 바이오로직스 시장 규모는 2025년에 4,126억 8,000만 달러로 평가되었습니다. 2026년 4,552억 3,000만 달러에서 성장하여 2031년까지 7,437억 9,000만 달러에 이를 것으로 추정되고 있습니다.
예측 기간(2026-2031년) 동안 연평균 성장률(CAGR)은 10.31%를 나타낼 전망입니다.
본 보고서는 제품별(단일클론 항체, 백신 등), 용도별(종양학, 자가면역·염증성 질환 등),원료원(포유류 세포 배양 등), 제조 기술(일회용 바이오리액터 등), 최종 사용자(제약·바이오기술 기업 등), 지역(북미, 유럽 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 바이오로직스 시장 동향 및 인사이트
전 세계 만성 질환 부담 증가
암, 자가면역 질환, 대사성 질환은 저분자 의약품으로는 더 이상 완전히 대처할 수 없는 복잡한 병태를 보이고 있습니다. 면역 요법이 치료의 초기 단계로 전환되는 가운데, 종양학 분야에서의 바이오로직스 활용은 36.54%의 점유율을 차지하며 연평균 성장률(CAGR) 13.78%로 성장을 지속하고 있습니다. 신규 B세포 제거 항체로 치료를 받은 류마티스 관절염 환자에서는 재발이 87% 감소한 것으로 보고되어, 뛰어난 임상적 조절 효과가 입증되었습니다. 당뇨병 및 비만 치료용 GLP-1 작용제는 공급을 초과하는 수요가 있어, 노보노르디스크는 새로운 충전 및 마무리 시설에 41억 달러를 투자하기로 결정했습니다. 희귀질환 치료제는 프리미엄 가격 책정이 가능한 희귀의약품 우대 조치의 혜택을 받고 있으며, 바이오로직스 시장 내에서 규모는 작지만 수익성이 높은 틈새 시장을 다수 창출하고 있습니다.
규제 승인 및 지정 절차의 신속화
FDA의 간소화된 호환성 지침에 따라, 바이오시밀러 개발 기업은 분석적 동등성이 입증되면 전환 시험을 생략할 수 있게 되었습니다. RMAT(신속 승인) 및 획기적 치료제 지정을 통해 2024년에 승인된 7개의 세포 및 유전자 치료제(흑색종 치료제 ‘리필레우셀’ 및 B형 혈우병 치료제 ‘피다나코젠 엘라파르보벡’ 등)의 승인까지 소요된 기간이 단축되었습니다. EMA(유럽의약품청)가 미국의 정책에 발맞춤에 따라 대서양을 가로지르는 동시 출시가 가능해져 중복 비용이 절감되고 있습니다. 중국의 국가약품감독관리국(NMPA)은 심사 절차를 근본적으로 재검토했으며, 이에 따라 Akeso사는 세계 기준을 상회하는 데이터를 바탕으로 이보네스시맙(ivonescimab)의 승인을 앞당길 수 있게 되어, 생물학적 제제 시장에서의 경쟁력을 강화했습니다.
높은 제조·개발 비용
노보 노르디스크의 클레이튼 공장 확장이나 일라이 릴리의 30억 달러 규모의 위스콘신 주 거점이 보여주듯이, 바이오로직스 공장 한 곳을 건설하는 데는 10억 달러 이상의 자본이 필요합니다. 일회용 시스템 덕분에 건설 기간은 단축되었지만, 백의 빈번한 교체와 특수 배지의 사용으로 인해 운영 비용은 증가하고 있습니다. 엔드투엔드 프로그램은 10-15년에 달하며, 임상시험만으로도 3억 달러의 비용이 소요될 수 있어 소규모 생명공학 기업 시장 진입을 제한하고 있습니다. CHO 배지, 수지, 무균 주사기공급 병목 현상은 비용을 상승시키고 일정을 위협하고 있습니다. 규모 확대 과정에서 발생하는 어떠한 편차도 제품의 무결성을 훼손할 위험이 있으므로 엄격한 공정 검증은 필수적이지만, 이는 막대한 비용이 소요됩니다.
부문별 분석
단일 클론 항체는 수십 년에 걸친 제조 기술의 정교화의 혜택을 받아, 2025년에는 2,720억 9,000만 달러를 차지하여 바이오로직스 시장 규모의 65.92%에 해당했습니다. 이 분야는 종양학, 자가면역 질환, 염증성 질환의 치료 용도로 확대되고 있으며, 예측 가능한 약리학적 특성으로 인해 광범위한 지불 기관으로부터 수용되고 있습니다. 대조적으로, 유전자 기반 바이오로직스은 혈우병 및 유전성 망막 질환에 대한 ‘퍼스트-인-클래스(First-in-Class)’ 제품의 승인을 발판으로, 2031년까지 연평균 성장률(CAGR) 12.11%를 나타낼 것으로 전망됩니다. 각국 정부가 팬데믹 대책에 자금을 투입하고 있어 백신은 여전히 견고한 주축으로 남아 있지만, 재조합 단백질은 성숙한 바이오시밀러로 인한 가격 하락 압력에 직면해 있습니다.
파이프라인에 대한 투자는 세포 치료로 이동하고 있으며, 2024년에 동종 CAR-T 치료 및 줄기세포 제품에 대한 7건의 새로운 FDA 승인이 이를 입증하고 있습니다. ADC(항체-약물 복합체)와 다중 특이성 항체는 표적 인식 도메인과 세포 독성 또는 면역 조절 작용을 가진 페이로드를 융합함으로써 정밀 종양학의 영역을 확대되고 있습니다. 현재 250건이 넘는 단백질 공학 프로그램이 반감기, 조직 투과성 및 면역원성 프로파일의 최적화를 위해 노력하고 있습니다. 이러한 변화들이 결합되어 바이오로직스 시장의 가치 제안을 높이고, 치료 범위를 확대하며, 지속적인 두 자릿수 성장을 뒷받침하고 있습니다.
2025년에는 종양학 분야가 바이오로직스 시장 규모의 36.12%를 차지했으며, 체크포인트 억제제, ADC, CAR-T 요법의 급속한 보급을 반영하여 연평균 성장률(CAGR) 13.45%로 확대될 것으로 예측됩니다. 그 다음으로 자가면역질환 분야가 꼽힙니다. 차세대 이중 특이성 항체가 TNF 억제제에 비해 우수한 질환 제어 효과를 보이고 있기 때문입니다. 감염증 분야의 바이오로직스은 예방 백신에 그치지 않고, 바이러스나 세균의 위협에 대한 노출 후 치료제로 발전하고 있습니다.
대사·내분비 질환 분야는 GLP-1 작용제의 적응증이 만성적인 체중 관리로 확대됨에 따라 규모가 커지고 있으며, 전 세계적으로 150억 달러를 넘는 생산 능력 확장 프로젝트가 추진되고 있습니다. 안과 분야는 1회 투여로 지속적인 효과를 가져다주는 유전자 치료의 혜택을 받을 전망입니다. 희귀질환 파이프라인은 희귀질환 치료제(오펀)에 대한 인센티브에 힘입어 대상 환자층을 확대되고 있습니다. 전반적으로 치료 영역의 다양화로 인해, 비록 특정 치료 영역이 부진하더라도 바이오로직스 시장의 회복력이 강화되고 있습니다.
지역별 분석
북미는 견실한 보험 환급 제도, 풍부한 벤처 캐피털, 그리고 ‘획기적 치료제 지정(Breakthrough Designation)’을 신속하게 승인하는 FDA의 지원에 힘입어 2025년 바이오로직스 시장 점유율 39.98%를 유지하며 리더십을 지켰습니다. 이 지역에서는 150억 달러 이상이 신규 생산 능력 확충에 투자되었으며, ‘리서치 트라이앵글’은 노보노르디스크, 일라이 릴리, 앰젠을 핵심으로 하는 세계 허브로 변모하고 있습니다. 시장 침투가 진행됨에 따라 성장률은 연평균 성장률(CAGR) 9.56%로 둔화되겠지만, 바이오시밀러가 정착됨에 따라 경쟁은 격화되고 있습니다.
아시아태평양은 중국, 일본, 인도가 규제 절차를 정비하고 바이오 제조에 투자함에 따라 11.32%라는 가장 높은 연평균 성장률(CAGR)을 보일 것입니다. 중국의 승인 절차 효율화로 인해 국내 기업들은 유럽과 미국의 기존 기업들에 도전할 수 있는 혁신적인 항암 바이오로직스을 시장에 출시할 수 있게 될 것입니다. 일본은 세제 혜택 및 공공 자금을 활용하여 중개 연구를 지원하고 있는 반면, 한국의 삼성바이오로직스는 CDMO(위탁 개발·제조) 역량을 전 세계로 수출하고 있습니다. 인도는 바이오시밀러 및 초기 단계 프로젝트에서 저비용 인력을 활용하여 해당 지역 내 입지를 더욱 공고히 하고 있습니다.
유럽은 성숙한 바이오시밀러 체계와 높은 공공 의료비 지출을 배경으로 9.05%라는 안정적인 연평균 성장률(CAGR)을 유지하고 있습니다. 독일과 스위스에서는 복잡한 항체의 고부가가치 생산이 이루어지고 있는 반면, 아일랜드와 덴마크는 유리한 법인세 제도를 통해 다국적 기업의 사업 확장을 유치하고 있습니다. 고령화와 만성 질환 유병률 증가가 수요의 기반이 되고 있으며, 규제 지침의 EU 전역에 걸친 조화를 통해 시장 진입 장벽이 낮아지고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the biologics market size was valued at USD 412.68 billion in 2025 and estimated to grow from USD 455.23 billion in 2026 to reach USD 743.79 billion by 2031, at a CAGR of 10.31% during the forecast period (2026-2031).

This report is Segmented by Product (Monoclonal Antibodies, Vaccines, and More), Application (Oncology, Autoimmune & Inflammatory, and More), Source (Mammalian Cell-Culture, and More), Manufacturing Technology (Single-Use Bioreactors, and More), End-User (Pharmaceutical & Biotech Companies, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Biologics Market Trends and Insights
Rising Global Chronic Disease Burden
Cancer, autoimmune disorders, and metabolic diseases present complex pathways that small-molecule drugs no longer address fully. Oncology uses of biologics command 36.54% share and post a 13.78% CAGR as immunotherapies move into earlier treatment lines. Rheumatoid arthritis patients treated with novel B-cell depletion antibodies report 87% flare reduction, illustrating superior clinical control. GLP-1 agonists for diabetes and obesity have outstripped supply, prompting Novo Nordisk to commit USD 4.1 billion to new fill-finish space. Rare disease therapies enjoy orphan incentives that allow premium pricing, creating many small but profitable niches within the biologics market.
Accelerated Regulatory Approvals and Designations
The FDA's streamlined interchangeability guidance lets biosimilar developer s bypass switching studies if analytical sameness is proven. RMAT and breakthrough labels shortened timelines for seven cell and gene therapies cleared in 2024, including lifileucel for melanoma and fidanacogene elaparvovec for hemophilia B. EMA alignment with U.S. policy now delivers simultaneous trans-Atlantic launches, trimming duplication costs. China's National Medical Products Administration has overhauled its process, enabling Akeso to bring ivonescimab forward with data that outperforms global standards and strengthens competitiveness in the biologics market.
High Manufacturing and Development Costs
A single biologics plant demands capital above USD 1 billion, as illustrated by Novo Nordisk's Clayton expansion and Eli Lilly's USD 3 billion Wisconsin site. Although single-use systems reduced build time, frequent bag changeovers and specialized media lift operating expense. End-to-end programs span 10-15 years and can cost USD 300 million in trials alone, limiting small biotech participation. Supply bottlenecks in CHO media, resins, and sterile syringes inflate costs and threaten scheduling. Any deviation during scale-up risks product integrity, making rigorous process validation essential and expensive.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Biosimilar Adoption Globally
- Continuous Innovation in Biologic Modalities
- Complex Regulatory and Quality Compliance Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Monoclonal antibodies contributed USD 272.09 billion, equal to 65.92% of the biologics market size in 2025, benefiting from decades of manufacturing refinement. The class spans oncology, autoimmune, and inflammatory uses, and its predictable pharmacology supports broad payer acceptance. In contrast, gene-based biologics post a 12.11% CAGR through 2031, propelled by first-in-class approvals for hemophilia and inherited retinal diseases. Vaccines remain a steady pillar as governments fund pandemic readiness, while recombinant proteins face downward price pressure from mature biosimilars.
Pipeline investment tilts toward cell-based modalities, evidenced by seven fresh FDA approvals in 2024 that validated allogeneic CAR-T and stem cell products. ADCs and multispecific antibodies broaden precision oncology by fusing targeting domains with cytotoxic or immune-modulatory payloads. Over 250 protein-engineering programs now optimize half-life, tissue penetration, and immunogenicity profiles. These shifts collectively raise the biologics market value proposition and expand therapeutic range, underwriting sustained double-digit growth.
Oncology accounted for 36.12% of the biologics market size in 2025 and will rise at a 13.45% CAGR, mirroring rapid uptake of checkpoint inhibitors, ADCs, and CAR-T therapies. Autoimmune conditions follow, as next-generation bispecific antibodies demonstrate superior disease control relative to TNF inhibitors. Infectious disease biologics develop beyond prophylactic vaccines into post-exposure therapeutics against viral and bacterial threats.
Metabolic and endocrine disorders add scale as GLP-1 agonists extend indications to chronic weight management, triggering worldwide capacity projects valued above USD 15 billion. Ophthalmology stands to gain from gene therapy that delivers durable benefit after a single administration. Rare disease pipelines, spurred by orphan incentives, deepen the addressable patient pool. Collectively, diversified applications reinforce resilience in the biologics market even if one therapeutic area softens.
Complete Report Scope:
- By Product
- Monoclonal Antibodies
- Vaccines
- Recombinant Proteins/Hormones
- Cellular-based Biologics (incl. CAR-T, Stem Cells)
- Gene-based Biologics (incl. AAV, mRNA)
- Multispecific & ADCs
- Other Products
- By Application
- Oncology
- Autoimmune & Inflammatory
- Infectious Diseases
- Metabolic & Endocrine
- Ophthalmology
- Rare & Genetic Disorders
- Other Applications
- By Source
- Mammalian Cell-Culture
- Microbial Expression
- Plant-based & Insect-cell Systems
- By Manufacturing Technology
- Single-use Bioreactors
- Stainless-steel Fed-Batch Systems
- Continuous Perfusion Platforms
- By End-user
- Pharmaceutical & Biotech Companies
- Contract Development & Manufacturing Organizations (CDMOs)
- Hospitals & Specialty Clinics
- Academic & Research Institutes
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America sustained leadership with 39.98% biologics market share in 2025, buoyed by robust reimbursement, venture capital depth, and an FDA that expedites breakthrough designations. The region channels more than USD 15 billion into new capacity, transforming the Research Triangle into a global hub anchored by Novo Nordisk, Eli Lilly, and Amgen. Although growth moderates to 9.56% CAGR as penetration matures, competitive intensity rises as biosimilars take hold.
Asia-Pacific delivers the quickest 11.32% CAGR as China, Japan, and India refine regulatory pathways and invest in biomanufacturing. China's streamlined approval timeline allows domestic players to launch innovative oncology biologics that challenge Western incumbents. Japan leverages tax incentives and public funding to support translational research, while South Korea's Samsung Biologics exports CDMO capacity globally. India capitalizes on low-cost talent for biosimilar and early-phase projects, further enlarging the region's footprint.
Europe maintains steady 9.05% CAGR on the back of mature biosimilar frameworks and high public health spending. Germany and Switzerland host high-value production for complex antibodies, whereas Ireland and Denmark entice multinational expansions via favorable corporate tax regimes. Aging demographics and chronic disease prevalence sustain underlying demand, and pan-EU harmonization of regulatory guidance reduces market entry friction.
- Abbvie
- Amgen
- Eli Lilly and Company
- Roche
- GlaxoSmithKline
- Johnson & Johnson
- Merck
- Pfizer
- Sanofi
- Bristol-Myers Squibb
- AstraZeneca
- Novartis
- Gilead Sciences
- Biogen
- Regeneron Pharmaceuticals
- Lonza Group
- Samsung Group
- Celltrion
- Takeda Pharmaceutical Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Chronic Disease Burden
- 4.2.2 Accelerated Regulatory Approvals and Designations
- 4.2.3 Expansion of Biosimilar Adoption Globally
- 4.2.4 Continuous Innovation in Biologic Modalities
- 4.2.5 Growth in Outsourced Biologics Manufacturing Capacity
- 4.2.6 Increasing Healthcare Expenditure in Emerging Markets
- 4.3 Market Restraints
- 4.3.1 High Manufacturing and Development Costs
- 4.3.2 Complex Regulatory and Quality Compliance Requirements
- 4.3.3 Supply Chain Constraints for Critical Raw Materials
- 4.3.4 Intensifying Environmental Sustainability Scrutiny
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Monoclonal Antibodies
- 5.1.2 Vaccines
- 5.1.3 Recombinant Proteins/Hormones
- 5.1.4 Cellular-based Biologics (incl. CAR-T, Stem Cells)
- 5.1.5 Gene-based Biologics (incl. AAV, mRNA)
- 5.1.6 Multispecific & ADCs
- 5.1.7 Other Products
- 5.2 By Application
- 5.2.1 Oncology
- 5.2.2 Autoimmune & Inflammatory
- 5.2.3 Infectious Diseases
- 5.2.4 Metabolic & Endocrine
- 5.2.5 Ophthalmology
- 5.2.6 Rare & Genetic Disorders
- 5.2.7 Other Applications
- 5.3 By Source
- 5.3.1 Mammalian Cell-Culture
- 5.3.2 Microbial Expression
- 5.3.3 Plant-based & Insect-cell Systems
- 5.4 By Manufacturing Technology
- 5.4.1 Single-use Bioreactors
- 5.4.2 Stainless-steel Fed-Batch Systems
- 5.4.3 Continuous Perfusion Platforms
- 5.5 By End-user
- 5.5.1 Pharmaceutical & Biotech Companies
- 5.5.2 Contract Development & Manufacturing Organizations (CDMOs)
- 5.5.3 Hospitals & Specialty Clinics
- 5.5.4 Academic & Research Institutes
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 AbbVie Inc.
- 6.3.2 Amgen Inc.
- 6.3.3 Eli Lilly and Company
- 6.3.4 F. Hoffmann-La Roche AG
- 6.3.5 GlaxoSmithKline plc
- 6.3.6 Johnson & Johnson
- 6.3.7 Merck & Co., Inc.
- 6.3.8 Pfizer Inc.
- 6.3.9 Sanofi SA
- 6.3.10 Bristol Myers Squibb
- 6.3.11 AstraZeneca plc
- 6.3.12 Novartis AG
- 6.3.13 Gilead Sciences Inc.
- 6.3.14 Biogen Inc.
- 6.3.15 Regeneron Pharmaceuticals
- 6.3.16 Lonza Group AG
- 6.3.17 Samsung Biologics
- 6.3.18 Celltrion Inc.
- 6.3.19 Takeda Pharmaceutical Co.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment