|
시장보고서
상품코드
2122642
택시 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Taxi - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
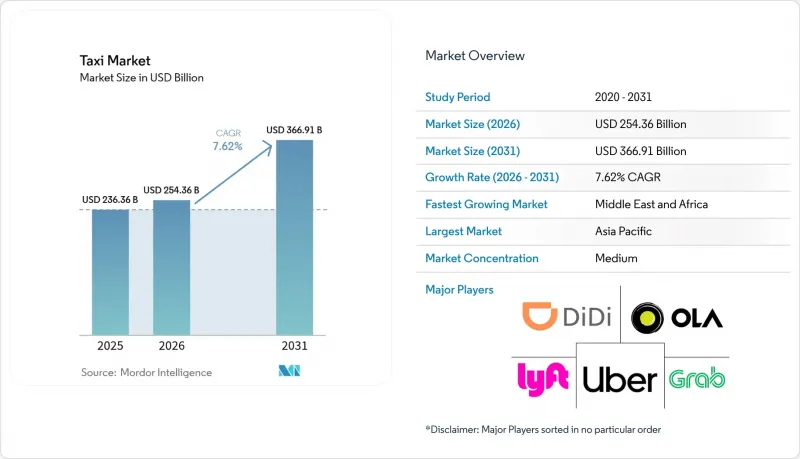
에 의하면, 택시 시장 규모는 2025년에 2,363억 6,000만 달러로 평가되었고, 2026년 2,543억 6,000만 달러에서 2031년까지 3,669억 1,000만 달러에 이를 것으로 추정되며, 예측 기간(2026-2031년) CAGR은 7.62%를 나타낼 전망입니다.
본 보고서는 예약 유형별(온라인 예약 및 오프라인 예약), 서비스 유형별(라이드 헤일링, 라이드 셰어링, 기업·기관용 계약), 차량 유형별(승용차, 오토바이·스쿠터, 밴·MPV, 오토릭샤·툭툭), 추진 방식별(내연기관, 전기, 하이브리드), 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 택시 시장 동향 및 인사이트
스마트폰 및 인터넷의 급속한 보급
주요 대도시권의 스마트폰 보급률이 5분의 4를 초과함에 따라, 플랫폼은 알고리즘을 활용해 승객과 운전자를 보다 신속하게 매칭할 수 있게 되었으며, 주요 도시에서는 평균 대기 시간이 15-20분에서 5분 미만으로 단축되었습니다. 5G의 광범위한 보급으로 인해 보다 상세한 위치 정보를 얻을 수 있게 되었으며, 이로 인해 차량 가동률이 향상되고 공차 주행 거리가 감소하고 있습니다. 데이터 통신 속도의 향상은 앱 내 동영상 광고 및 운전자에게 실시간 안내를 가능하게 하여 다양한 수익원 개척으로 이어지고 있습니다. 배차 앱에 통합된 모바일 지갑은 선진국 시장의 거래 중 5분의 4 이상을 차지하게 되어, 현금 취급의 위험을 줄이고 공항에서의 대기 시간을 단축하고 있습니다. 신흥국에서는 인터넷 환경의 개선으로 기존 배차 시스템을 뛰어넘어 디지털 예약이 비약적으로 보급되고 있습니다.
도시 지역의 교통 체증과 자가용 보유율 감소
인구 밀도가 높은 도시에서는 차량 이용률이 소폭 감소하는 경향이 있으며, 이에 따라 주민들은 주차 요금이 들지 않는 온디맨드 차량 호출 서비스로 자가용을 대체하고 있습니다. 지자체가 부과하는 정체 요금에 더해, 유류 가격 급등으로 인해 자동차 소유에 드는 총비용이 상승하면서 택시 서비스의 매력이 높아지고 있습니다. 특히, 1회당 운임을 최대 40%까지 절감할 수 있는 카풀 형태의 서비스가 인기를 끌고 있습니다. 25-35세의 젊은 소비자들은 이러한 추세에 가장 민감하며, 택시와 철도, 버스, 마이크로모빌리티를 하나의 앱에 통합한 ‘모빌리티 애즈 어 서비스(MaaS)’의 정액제 구독 서비스를 선호합니다. 미국에서는 교통 체증으로 인한 비용이 연간 1,000억 달러를 초과함에 따라, 도시 당국은 승차율이 높은 교통 수단을 우선시하라는 정치적 압력을 받고 있으며, 이는 간접적으로 택시 시장 수요를 끌어올리고 있습니다.
면허 제도의 변천과 규제 강화
각 도시의 규제 당국은 택시 영업권(메달리온) 제도의 현대화를 추진하는 동시에 신원 조사 규정을 엄격히 하고 있어, 앱 기반 사업자와 기존 사업자 모두에게 규정 준수 비용이 증가하고 있습니다. 시애틀시는 2026년 3월까지 메달리온 제도를 단계적으로 폐지할 계획인 반면, 뉴욕시는 2025년 3월까지 전체 택시의 절반이 휠체어 이용이 가능하도록 의무화하고 있습니다. 싱가포르 규제 당국은 독점 금지법상의 우려로 인해 Grab의 Trans-Cab 인수 계획을 저지했으며, 플랫폼 통합에 대한 감시가 강화될 조짐을 보이고 있습니다. 지역별로 상이한 기준은 법적 복잡성을 가중시키고 시장 진입을 지연시킬 가능성이 있어, 단기적인 성장 모멘텀을 저해할 우려가 있습니다.
부문 분석
2025년에는 온라인 채널이 택시 시장 점유율의 63.78%를 차지했으며, 앱 기반 수요 집약으로의 구조적 전환이 뚜렷해졌습니다. 디지털 예약의 부상으로 수요 예측의 정확도를 높이는 비즈니스 인텔리전스 루프가 강화되었으며, 그 결과 자산 활용도 향상과 승객 대기 시간 단축으로 이어졌습니다. 오프라인 부문은 고령층이나 여전히 메달리온 제도에 따라 길거리에서 택시를 잡는 것이 허용되는 지역에서 여전히 중요하지만, 그 성장 궤도는 택시 시장 전체에 비해 뒤처지고 있습니다. 따라서 사업자들은 앱에 더해 음성 기반 IVR 및 키오스크 인터페이스를 통합하여 기존 사용자를 유지하면서 디지털 이용으로 유도하고 있습니다.
향후 온라인 예약은 연평균 성장률(CAGR) 7.92%를 나타낼 것으로 예측됩니다. 모빌리티와 결제, 전자상거래를 통합한 슈퍼 앱이, 특히 스마트폰 보급률이 5분의 4를 넘는 아시아태평양의 메가시티에서 승차 횟수 증가를 뒷받침할 것입니다. 또한, 온라인 채널은 승차별 상세 데이터를 제공하고, 이를 활용한 타겟형 로열티 프로그램 및 동적 가격 책정을 가능하게 함으로써 시장 점유율 확대를 뒷받침하고 있습니다. 계약 기반의 법인 계정, 공항 내 영업권, 그리고 의무화된 접근성 서비스가 오프라인 채널의 연평균 성장률(CAGR)을 뒷받침하고 있습니다. 그러나 그 수익 비중은 2031년까지 택시 시장 규모의 3분의 1 미만으로 떨어질 것으로 예측됩니다.
라이드 헤일링은 보다 신속한 매칭과 투명한 가격 책정을 보장하는 네트워크 효과 덕분에 2025년에는 택시 시장 규모의 74.85%를 차지했습니다. 시장을 선도하는 각 플랫폼 기업들은 안전성 검증, 실시간 모니터링 및 운전자 교육에 막대한 투자를 하고 있으며, 이를 통해 비공식 경쟁사보다 서비스 신뢰도를 높이고 있습니다. 카풀 서비스는 교통 체증을 완화하고 승객들끼리 비용을 분담함으로써 좌석당 요금을 낮출 수 있기 때문에 연평균 성장률(CAGR) 7.78%로 택시 시장 전체의 성장률을 상회하는 성장이 예상됩니다. 기업들이 차량 전체의 이산화탄소 배출 감축 목표를 설정함에 따라, 환경 규정 준수 노력이 카풀 수요를 더욱 부추기고 있습니다.
한때 고급 차량(블랙카) 플릿이 지배하던 기업용 모빌리티 계약은 디지털 영수증과 좌석별 경비 배분을 제공하는 앱 기반 제공업체에 발주되는 사례가 늘고 있습니다. 내장된 데이터를 통해 ESG를 중시하는 이사회가 현재 요구하는 탄소 배출량 보고 대시보드를 쉽게 구축할 수 있습니다. 라이드헤일링은 총 예약액 측면에서 여전히 우위를 점하고 있지만, 카풀 방식은 특히 1인 탑승 시 추가 요금이 부과되는 피크 시간대에 더 높은 탑승률과 뛰어난 자산 생산성을 실현하고 있습니다.
지역별 분석
2025년, 아시아태평양은 택시 시장 점유율의 37.42%를 차지했습니다. 이는 급속한 도시화, 5분의 4를 넘는 스마트폰 보급률, 그리고 인구 밀집 지역에서 활발한 이륜 택시의 보급에 힘입은 결과입니다. EV(전기차)에 대한 보조금 및 영업 허가 면제 등 정부의 정책에 힘입어 인도, 베트남, 태국 전역에서 차량 교체 속도가 가속화되고 있습니다. 일본의 기존 택시 사업자들은 우버와 제휴하여 2만 대의 차량을 플랫폼에 통합함으로써 국경을 초월한 디지털 표준화를 강화하고 있습니다.
중동 및 아프리카은 각국의 디지털 경제 프로그램과 메가시티 인프라 구축에 힘입어 2031년까지 연평균 성장률(CAGR) 7.88%를 나타낼 것으로 예측됩니다. 두바이 택시 컴퍼니(Dubai Taxi Company)는 UAE의 ‘넷 제로 2050’ 로드맵에 따라 2029년까지 차량 호출 요청의 약 5분의 4를 전자 예약으로 전환하고, 차량의 4분의 1을 전기차로 전환하는 것을 목표로 하고 있습니다. 이집트, 사우디아라비아, 나이지리아에서는 젊고 기술에 정통한 인구층이 기존 예약 모델을 뛰어넘는 형태로 차량 호출 앱이 급속히 보급되고 있습니다. Careem과 같은 지역 횡단형 슈퍼앱은 결제, 배송, 교통을 하나의 플랫폼에 통합하여 사용자 유지율을 높이고 있습니다. 당국은 접근성 및 데이터 개인정보 보호에 관한 규제를 강화하고 있으며, 이에 대응하기 위해 막대한 규정 준수 비용이 필요하기 때문에 대규모 사업자에게 유리한 상황이 되고 있습니다. 2025년 4월 Lyft가 FREENOW를 인수함에 따라, 해당 기업의 유럽 내 사업 범위는 11개국으로 두 배로 확대되었으며, 연간 약 3,000억 건의 개인 차량 이용에 대한 접근성이 확보되었습니다. 한편, 독일 각지의 시의회는 제로 배출 구역의 시범 도입을 추진하고 있어, 이로 인해 전기차 보급 기준이 기업들의 계획보다 빠르게 상향 조정될 가능성이 있습니다. 결과적으로 성장세는 둔화되겠지만, 플랫폼이 배송 사업이나 구독형 모빌리티 패스로 사업을 다각화하고 있기 때문에 여전히 플러스 성장을 유지하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the taxi market size was valued at USD 236.36 billion in 2025 and estimated to grow from USD 254.36 billion in 2026 to reach USD 366.91 billion by 2031, at a CAGR of 7.62% during the forecast period (2026-2031).
This report is Segmented by Booking Type (Online Booking and Offline Booking), Service Type (Ride-Hailing, Ride-Sharing, and Corporate & Institutional Contracts), Vehicle Type (Passenger Cars, Motorcycles & Scooters, Vans & MPVs, and Auto-Rickshaws & Tuk-Tuks), Propulsion Type (ICE, Electric, and Hybrid), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Taxi Market Trends and Insights
Rapid Smartphone & Internet Penetration
Smartphone penetration above four-fifths in leading urban centers lets platforms algorithmically match riders and drivers faster, shrinking average wait times from 15-20 minutes to under 5 minutes in top-tier cities. Ubiquitous 5G coverage allows richer location data, which boosts fleet utilisation and lowers deadhead mileage. Higher data speeds also mean in-app video ads and real-time driver coaching, unlocking diversified revenue streams. Mobile wallets embedded in ride-hailing apps now account for more than four-fifths of transactions in developed markets, lowering cash-handling risk and reducing airport queue times. In emerging economies, internet upgrades bypass legacy dispatch systems, enabling leap-frog adoption of digital bookings.
Urban Congestion & Declining Private-Car Ownership
Vehicle utilisation in dense cities often falls slightly, motivating residents to replace private cars with on-demand rides that eliminate parking fees. Municipal congestion charges plus rising fuel prices raise the total cost of car ownership, reinforcing the appeal of taxi services, especially pooled formats that can cut per-trip fares by up to 40%. Younger consumers aged 25-35 are most receptive, preferring bundled mobility-as-a-service subscriptions integrating taxis with rail, bus, and micro-mobility in one app. Congestion costs topping USD 100 billion annually in the U.S. place political pressure on cities to privilege high-occupancy modes, indirectly boosting taxi market demand.
Evolving Licensing & Regulatory Crack-Downs
City regulators are modernising medallion structures and tightening background-check rules, raising compliance costs for app-based and traditional operators. Seattle plans to phase out its medallion regime by March 2026, while New York City requires half of all cabs to be wheelchair-ready by March 2025. The Singaporean watchdog blocked Grab's planned acquisition of Trans-Cab over antitrust concerns, signalling closer scrutiny of platform consolidation. Divergent regional standards increase legal complexity and can delay market entries, suppressing near-term growth momentum.
Other drivers and restraints analyzed in the detailed report include:
- Ride-Hailing Platform Expansion In Emerging Economies
- AI-Based Dynamic Routing & Pricing Optimisation
- Intensifying Price Wars Eroding Driver Earnings
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Online channels delivered 63.78% of the taxi market share in 2025, illustrating the structural pivot toward app-based demand aggregation. The dominance of digital bookings strengthened business intelligence loops that sharpen demand prediction, resulting in higher asset utilisation and lower passenger wait times. The offline segment remains relevant among older demographics and jurisdictions where medallion systems still confer street-hail privilege, yet its growth trajectory lags the broader taxi market. Operators are therefore integrating voice-based IVR and kiosk interfaces alongside apps to preserve legacy users while nudging them toward digital interactions.
Looking forward, online bookings are forecast to grow at an 7.92% CAGR. Super-apps bundling mobility with payments and e-commerce will underpin incremental trip volumes, especially in APAC megacities where smartphone penetration exceeds four-fifths. Online channels also furnish granular trip-level data that powers targeted loyalty and dynamic pricing, reinforcing share gains. Contractual corporate accounts, airport concessions, and mandated accessibility services sustain the offline channel's CAGR. Yet, its revenue mix is expected to shrink below one-third of the taxi market size by 2031.
Ride-hailing controlled 74.85% of taxi market size in 2025, owing to network effects that ensure quicker matches and transparent pricing. Market-leading platforms invest heavily in safety verification, real-time monitoring, and driver training that elevate service reliability above informal rivals. Pooled rides are projected to outpace overall taxi market expansion with an 7.78% CAGR because they ease congestion and lower per-seat fares by sharing costs among passengers. Environmental compliance agendas further catalyse pooled demand as corporates set fleet-wide carbon reduction targets.
Corporate mobility contracts, once dominated by black-car fleets, are increasingly awarded to app-based providers offering digital receipts and per-seat expense allocation. The embedded data facilitates carbon-reporting dashboards now demanded by ESG-focused boards. Although ride-hailing maintains gross-booking supremacy, pooled formats generate higher occupancy and superior asset productivity, especially during peak hours when single-occupancy trips face surge pricing.
Complete Report Scope:
- By Booking Type
- Online Booking
- Offline Booking
- By Service Type
- Ride-hailing
- Ride-sharing (pooled)
- Corporate & Institutional Contracts
- By Vehicle Type
- Passenger Cars
- Motorcycles & Scooters
- Vans & MPVs
- Auto-Rickshaws & Tuk-tuks
- By Propulsion Type
- Internal Combustion Engine (ICE)
- Electric
- Hybrid
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Vietnam
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific contributed 37.42% taxi market share in 2025, sustained by rapid urbanisation, smartphone usage above four-fifth, and widespread two-wheeler taxis that thrive in dense corridors. Government policies offering EV subsidies and medallion exemptions accelerate fleet turnover throughout India, Vietnam, and Thailand. Japan's taxi incumbents partner with Uber to integrate 20,000 vehicles on the platform, reinforcing cross-border digital standardisation.
The Middle East and Africa is projected to register an 7.88% CAGR through 2031, due to national digital-economy programmes and mega-city infrastructure. Dubai Taxi Company aims to migrate around four-fifth of rides to e-booking by 2029 while electrifying one-quarter of its fleet, aligning with the UAE Net-Zero 2050 roadmap. Ride-hailing apps proliferate in Egypt, Saudi Arabia, and Nigeria where youthful, tech-savvy populations leapfrog legacy dispatch models. Pan-regional super-apps such as Careem integrate payments, delivery, and transport under one umbrella, enhancing user retention. Authorities impose stricter accessibility and data-privacy mandates, requiring material compliance outlays that favor scaled operators. Lyft's acquisition of FREENOW in April 2025 doubled its European reach to 11 countries and opened access to nearly 300 billion annual personal vehicle trips. Meanwhile, city councils across Germany are testing zero-emission zones that could bump EV adoption thresholds earlier than corporate plans anticipate. Net effect: growth slows but remains positive as platforms diversify into deliveries and subscription mobility passes.
- Uber Technologies Inc.
- Beijing Xiaoju Technology Co. Ltd (DiDi)
- Lyft Inc.
- Grab Holdings Inc.
- Bolt Technology OU
- ANI Technologies Pvt Ltd (Ola)
- Gojek Tech
- FREE NOW (Intelligent Apps GmbH)
- BlaBlaCar
- Curb Mobility LLC
- Flywheel Software Inc.
- Kabbee Exchange Ltd
- Addison Lee Group
- Gett Inc.
- Yandex Go (Yandex NV)
- Careem Networks FZ-LLC
- Via Transportation Inc.
- Beat Mobility Services Ltd
- Easy Taxi (Tappsi SAS)
- Cabify Espana SL
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Smartphone & Internet Penetration
- 4.2.2 Urban Congestion & Declining Private-Car Ownership
- 4.2.3 Ride-Hailing Platform Expansion In Emerging Economies
- 4.2.4 AI-Based Dynamic Routing & Pricing Optimisation
- 4.2.5 Accessibility Mandates Driving Fleet Renewal
- 4.2.6 Super-App Api Integrations Boosting Embedded Demand
- 4.3 Market Restraints
- 4.3.1 Evolving Licensing & Regulatory Crack-Downs
- 4.3.2 Intensifying Price Wars Eroding Driver Earnings
- 4.3.3 Limited Public Ev-Charging Slowing E-Taxi Uptake
- 4.3.4 Data-Privacy Litigation Around Trip-Tracking
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Booking Type
- 5.1.1 Online Booking
- 5.1.2 Offline Booking
- 5.2 By Service Type
- 5.2.1 Ride-hailing
- 5.2.2 Ride-sharing (pooled)
- 5.2.3 Corporate & Institutional Contracts
- 5.3 By Vehicle Type
- 5.3.1 Passenger Cars
- 5.3.2 Motorcycles & Scooters
- 5.3.3 Vans & MPVs
- 5.3.4 Auto-Rickshaws & Tuk-tuks
- 5.4 By Propulsion Type
- 5.4.1 Internal Combustion Engine (ICE)
- 5.4.2 Electric
- 5.4.3 Hybrid
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Vietnam
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 GCC
- 5.5.5.2 Turkey
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Uber Technologies Inc.
- 6.4.2 Beijing Xiaoju Technology Co. Ltd (DiDi)
- 6.4.3 Lyft Inc.
- 6.4.4 Grab Holdings Inc.
- 6.4.5 Bolt Technology OU
- 6.4.6 ANI Technologies Pvt Ltd (Ola)
- 6.4.7 Gojek Tech
- 6.4.8 FREE NOW (Intelligent Apps GmbH)
- 6.4.9 BlaBlaCar
- 6.4.10 Curb Mobility LLC
- 6.4.11 Flywheel Software Inc.
- 6.4.12 Kabbee Exchange Ltd
- 6.4.13 Addison Lee Group
- 6.4.14 Gett Inc.
- 6.4.15 Yandex Go (Yandex NV)
- 6.4.16 Careem Networks FZ-LLC
- 6.4.17 Via Transportation Inc.
- 6.4.18 Beat Mobility Services Ltd
- 6.4.19 Easy Taxi (Tappsi SAS)
- 6.4.20 Cabify Espana SL
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment